4.05 Exhibit index, Part III and amendment drafting slips in both years: duplicate exhibit number, misdated credit amendment, Exhibit 19.1 described inconsistently
Company G · a US-listed specialty pharmaceutical company · Drafting slip
In brief
Drafting slips in Part III, the exhibit index and the Part III amendment (Form 10-K/A): exhibit number [n] is used for two plans; Amendment No. 2 to the Credit Agreement is dated [date] in this and the prior-year 10-K, although the Form 8-K that filed it dates it [date]; the insider trading policy (Exhibit 19.1) is indexed as incorporated from the [date] 10-K although it was filed again with this 10-K, and the 10-K/A says it is filed with the amendment while its own index again shows incorporation; the 10-K/A cover excludes [n] affiliate shares against [n] on this 10-K's cover for the same [date] float; the [n] carve-out sits under [n]; and a footnote reads 'Regulations S-K'.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Two exhibits numbered [n]+; Amendment No. 2 dated [date] (also in the prior-year 10-K); Exhibit 19.1 indexed as incorporated from the 10-K filed [date] in both this 10-K and the 10-K/A; affiliate shares excluded [n] (10-K) and [n] (10-K/A); Item 12 excludes the Item 402(v) information; 'Regulations S-K'. | Renumber the director compensation policy ([n]); date Amendment No. 2 [date]; mark Exhibit 19.1 as filed herewith (or stop re-filing it) and describe it the same way in the 10-K/A; one affiliate share count on both covers; move the Item 402(v) carve-out to Item 11; read 'Regulation S-K'. |
| What we checked. Exhibit numbers listed in sequence; amendment dates compared with the glossary and MD&A; Part III wording compared with the prior-year Form 10-K | |
Why it matters
Cosmetic: readers and hyperlink checks may confuse the two exhibits numbered [n], the amendment date points to the wrong instrument, and the exhibit and cover descriptions differ between the 10-K and its amendment.
Exposure
No exposure; drafting only.
Our workings
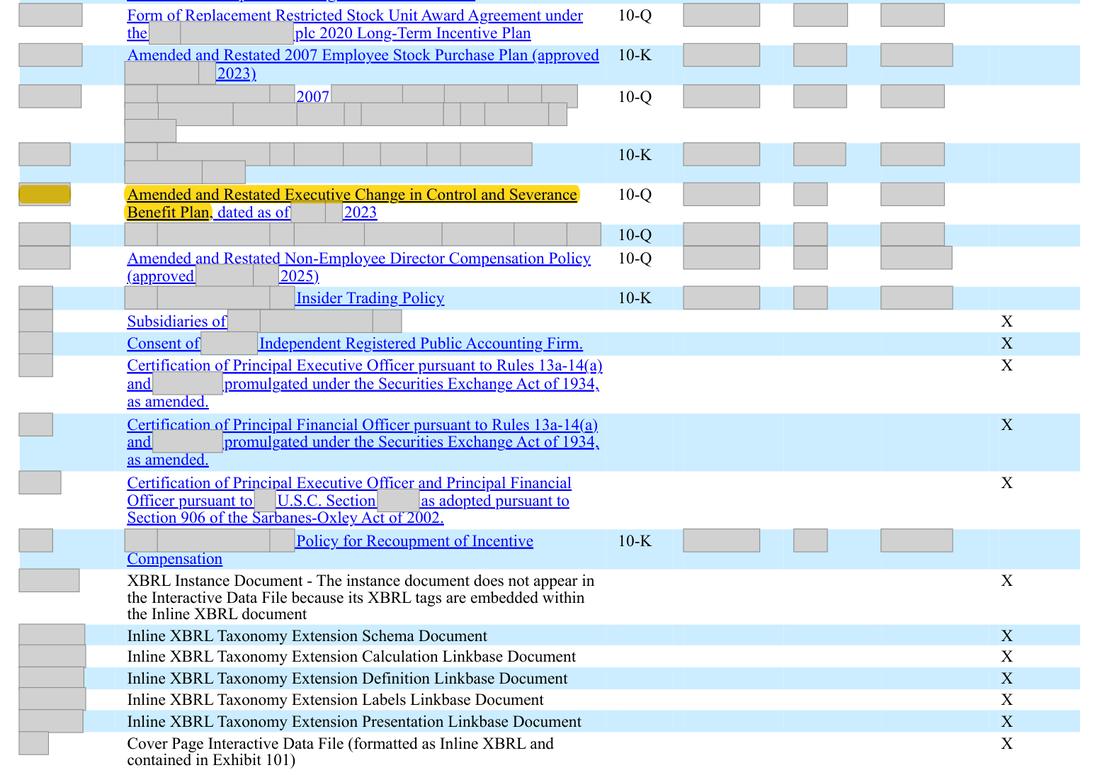
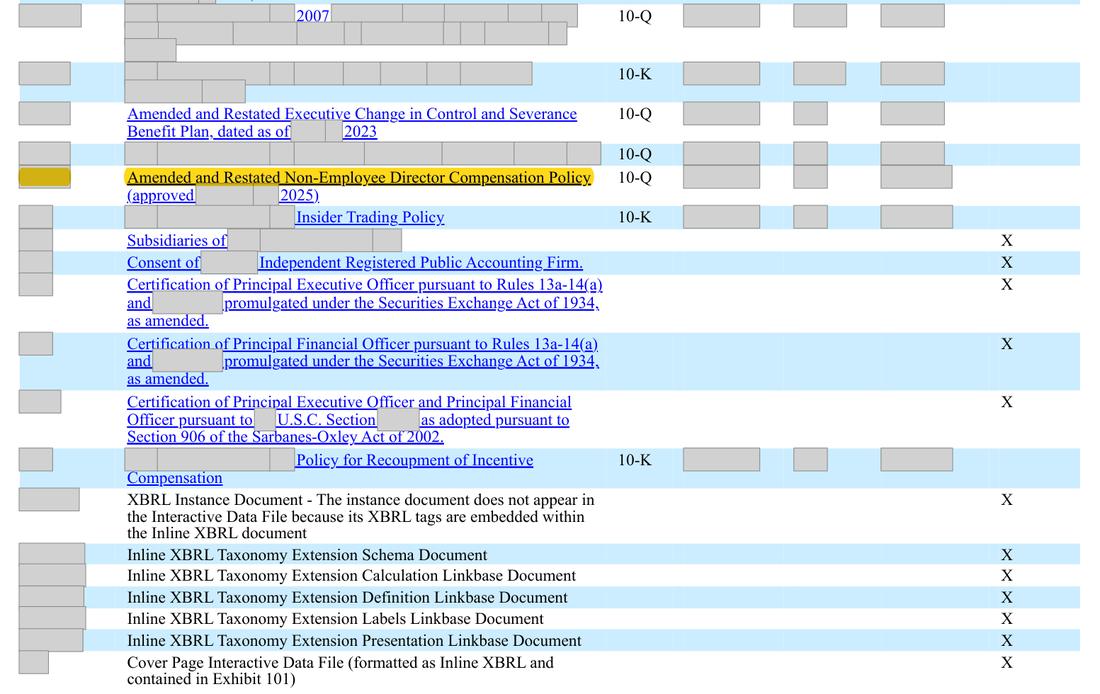
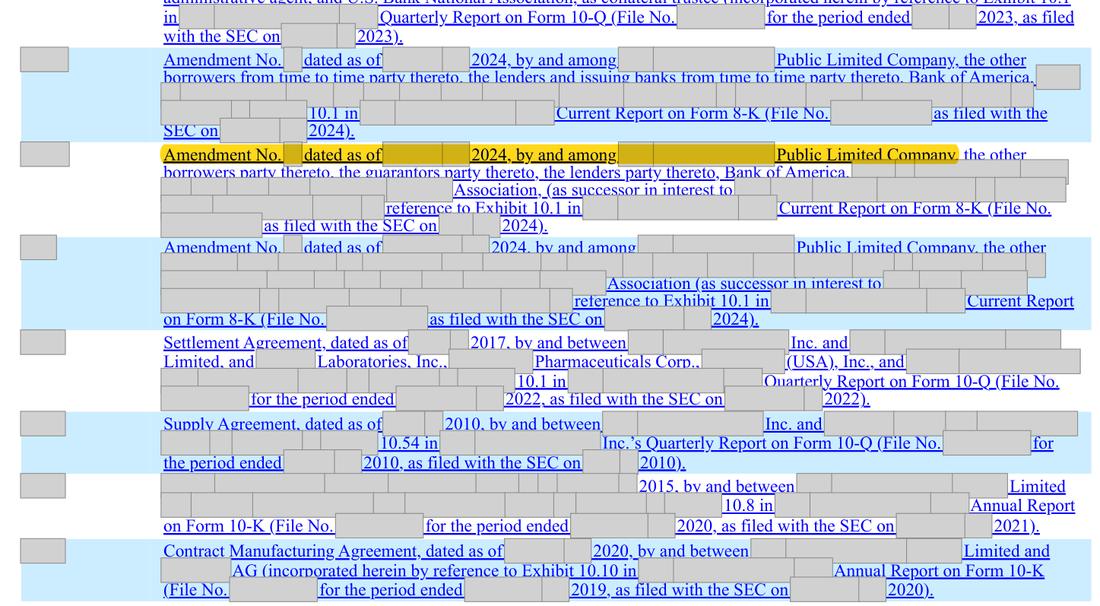
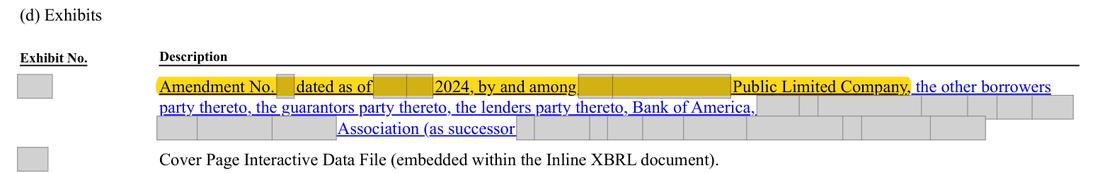
the exhibit index lists [n]+ for the Amended and Restated Executive Change in Control and Severance Benefit Plan and again for the Amended and Restated Non-Employee Director Compensation Policy, with [n]+ between them. The exhibit for Amendment No. 2 to the Credit Agreement gives the date [date], the same date as Amendment No. 1; the prior-year 10-K used the same date, while Item 7A says the Repricing Amendment No. 2 was entered into in [date] and the Form 8-K of [date] that filed it dates it [date]. Exhibit 19.1, the insider trading policy, is indexed as incorporated from the 10-K filed on [date] with no 'filed herewith' mark, yet the policy (the unchanged [date] version) was attached as Exhibit 19.1 to this [n] submission; the Part III amendment says the policy was filed with this [n] and is filed as Exhibit 19.1 to the amendment, while the amendment's own index again shows it as incorporated from the [date] [n]. The amendment's cover excludes [n] affiliate shares and this [n]'s cover [n] for the same [date] date and the same aggregate market value. [n] says its information is incorporated 'other than the information required by [n]', but pay-versus-performance information belongs to executive compensation ([n], and [n] to [n] already keeps it out of incorporation unless specifically incorporated. The redaction footnote reads 'Regulations S-K'.
none of these changes any figure, obligation or the float; they are drafting slips, two of which (the amendment date and the footnote) were also in the prior-year Form 10-K.
Management’s best defense, and our reply
The company could say these are clerical points that affect no disclosure obligation, the hyperlinks still open the right documents, the policy is filed either way, and a [n]-share difference does not change the float. That is accepted: the points are recorded as drafting slips only.
The fix
- Renumber the second [n] as [n]; describe Exhibit 10.[n]D as 'Amendment No. 2, dated as of [date]'; mark Exhibit 19.1 'filed herewith' when it is re-filed and describe it the same way in any amendment; use one affiliate share count on every cover for the same date; move the Item 402(v) carve-out to Item 11; correct 'Regulations S-K' to 'Regulation S-K'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | First use of exhibit number [n] | Document | Form 10-K 2025, page 114 |
| 2 | Second use of exhibit number [n], after [n] | Document | Form 10-K 2025, page 114 |
| 3 | Amendment No. 2 carries the date of Amendment No. 1 | Document | Form 10-K 2025, page 111 |
| 4 | The report itself dates Amendment No. 2 to [date] | Document | Form 10-K 2025, page 105 |
| 5 | Pay-versus-performance carve-out placed under Item 12 (security ownership) rather than Item 11 | Document | Form 10-K 2025, page 109 |
| 6 | Footnote misnames Regulation S-K | Document | Form 10-K 2025, page 114 |
| 7 | The prior-year 10-K gave Amendment No. 2 the same wrong date | Document | Form 10-K 2024 (prior year), page 107 |
| 8 | The Form 8-K of [date] that filed the amendment dates it [date] | Document | |
| 9 | Exhibit 19.1 indexed as incorporated from the 10-K filed [date], with no 'filed herewith' mark | Document | Form 10-K 2025, page 114 |
| 10 | The policy was attached again as Exhibit 19.1 to this 10-K submission | Document | |
| 11 | The re-filed policy is the unchanged [date] version | Document | |
| 12 | Part III amendment text: filed with the 10-K and filed again with the amendment | Document | |
| 13 | The amendment's own index again shows the policy as incorporated from the [date] 10-K | Document | |
| 14 | This 10-K's cover: affiliate shares excluded from the [date] float | Document | Form 10-K 2025, unnumbered page |
| 15 | The amendment's cover: a different affiliate share count for the same date and float | Document | |
| 16 | The fiscal 2024 exhibit-index redaction footnote has the same 'Regulations S-K' slip | Document | Form 10-K 2024 (prior year), page 113 |
| 17 | The 2024 Form 10-K gave Amendment No. 2 the same wrong date | Document | Form 10-K 2024 (prior year), page 107 |
| 18 | The Form 8-K of [date] that filed the amendment dates it [date] | Document | |
| 19 | Exhibit 19.1 is shown as incorporated by reference to the 2024 Form 10-K, with no 'filed herewith' mark | Document | Form 10-K 2025, page 114 |
| 20 | Yet the policy was attached again as Exhibit 19.1 to the 2025 Form 10-K submission | Document | |
| 21 | The re-filed policy is the unchanged [date] version, so the slip is in the index only | Document | |
| 22 | This 10-K's exhibit index: the insider trading policy is shown as incorporated from the 10-K filed on [date], with no 'filed herewith' mark | Document | Form 10-K 2025, page 114 |
| 23 | Part III amendment: says the policy was filed with this 10-K and is filed again with the amendment | Document | |
| 24 | Part III amendment's own exhibit index: the policy is again shown as incorporated from the [date] 10-K, not as filed with the amendment | Document | |
| 25 | This 10-K's cover: affiliate shares excluded from the [date] public float | Document | Form 10-K 2025, unnumbered page |
| 26 | Part III amendment's cover: a different affiliate share count for the same date and the same float | Document |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.