For audit committees.
An independent reading of the report the board will approve, released to the chair directly.
Independent comfort, with the evidence attached.
An independent reading of the whole report against the rules and the company’s own earlier filings. The chair receives it at the same moment as the CFO.
An observation is never deleted at the client’s request. Management can respond or dispute, and the response is recorded beside the point. The report counts how many points were raised, kept, put as questions and dropped.
We run a conflicts check before accepting and decline if there is a relationship that could compromise the review. We are not the company’s auditor and are not affiliated with it. Nobody who reviews a draft trades in, advises on or publishes about the company.
Each report opens with an executive summary: priority matters first, then compliance gaps, drafting points and questions for the company. The workbook gives the committee a closure record, point by point.
Every point carries its page, its highlighted extract and the rule. Each released report has a recorded fingerprint that anyone can check on the verify page.
Four things on every observation. Check them yourself.
- 1
The page
The page number and the highlighted words from your 10-K, so your team finds it in seconds.
- 2
The rule
The requirement quoted, in the version in force for the period, not today’s.
- 3
The challenge
Management’s best answer argued first. A point is a finding only at 99%; otherwise it is a question, or dropped and counted.
- 4
The review
Every report is reviewed by Sandeep Choudhary before release.
Real 10-K Pre-filing Checks on filed Forms 10-K, with the companies masked: every observation shows the rule, our workings, the likely defense and the evidence.
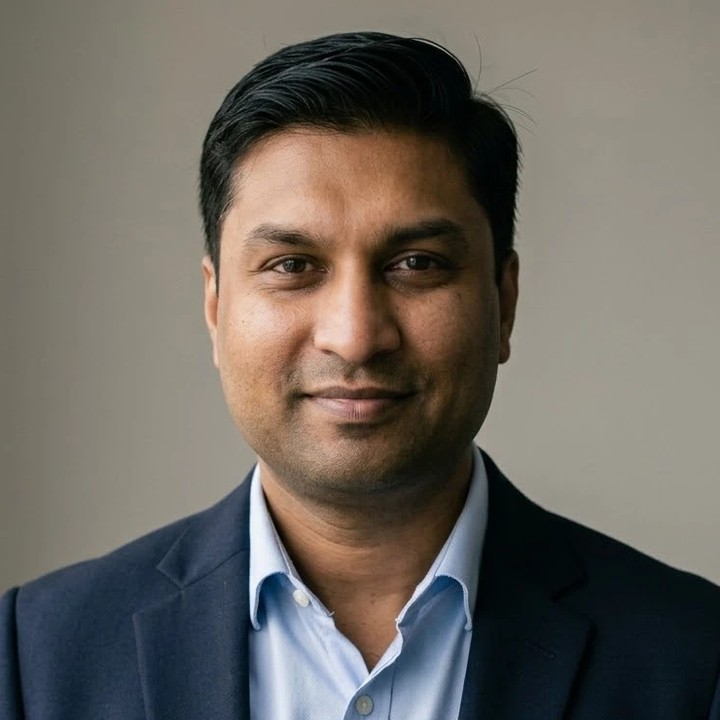
Every report is reviewed by Sandeep Choudhary before release.
Sandeep Choudhary, Founder, Pramanex. More than 17 years across treasury, record-to-report, finance centers of excellence for global groups, and finance transformation.
The objections we hear, answered.
Can the committee commission the review itself?
Yes. Tell us at the first call and the engagement is set up with the committee as the client, with the CFO receiving the report at the same time.
Does it replace the auditor or internal audit?
No. The auditor gives its opinion; internal audit tests controls. We read the published document against the rules and against itself. It complements both and replaces neither.
Can we use the report to challenge the auditor?
You can share it with the auditor, in full and with its declaration page intact. The auditor decides for itself what weight, if any, to give it.
Is this an audit?
No. Not an audit, review or other attestation or assurance engagement, and not legal advice. Pramanex is not a CPA firm and is not registered with the PCAOB. We report observations with evidence; the company and its directors keep every decision.
How accurate is it?
“99%” is the threshold a point must clear to be called a finding, not a measured accuracy rate, and we do not claim one. What you can check: every quotation is matched to the page image, every rule to its official text, a separate pass argues the company’s side, and the report counts how many points were kept, put as questions or dropped.
What if you find nothing?
Then the report says so, and shows what was read, which checks were run and how many candidate points were dropped and why. We do not pad a report to justify the fee. On the free teaser, if fewer than three points meet our standard, we tell you so.
Who is liable if you miss something?
Our liability for an engagement is limited to the fee paid for it, to the extent the law allows, and a report is not exhaustive: a matter not raised is not confirmed as compliant. That is why every point carries its evidence, so your team can check it rather than trust it. Professional liability cover for US engagements is put in place before the first paid US engagement.
Book a 20-minute call.
Tell us your year end and your timetable. We tell you what we would read, what it would cost and what we need from you. No documents, no obligation.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.