2.06 The reasons given for the rise in selling, general and administrative expenses add up to more than the rise itself
Company G · a US-listed specialty pharmaceutical company · SEC-style question
In brief
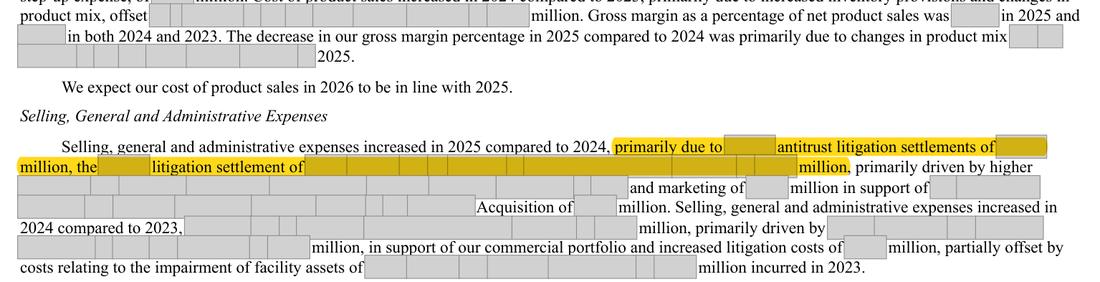
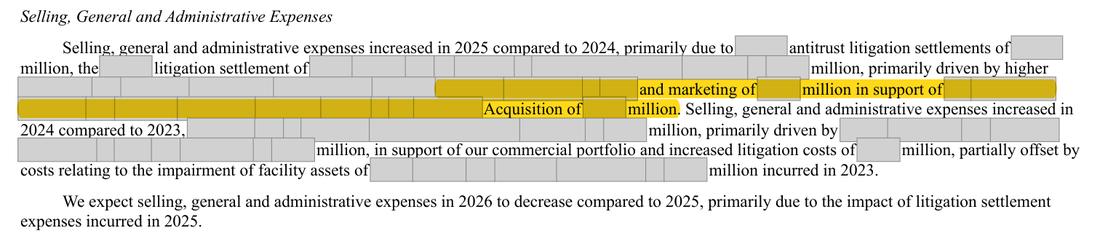
Selling, general and administrative (SG&A) expenses rose by [n] (USD thousands) in 2025. The MD&A names five reasons for the rise - two litigation settlements, higher compensation, more sales and marketing spend and [acquired business] integration costs - which add up to [n]. The difference of [n] means some costs fell during the year, but the MD&A does not say which. Management should explain the offsetting decreases or confirm that none of them is material.
The evidence, as filed
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
SG&A increase of [n] explained by named increases totalling [n]; offsetting decreases of [n] are not identified. | A discussion that also names any material decrease within the line (for example lower legal fees or lower costs in a program that ended), in amount, as Item 303(b) requires where material changes within a line item offset one another. |
| What we checked. Results of operations table (2025 and 2024 SG&A), the SG&A narrative and its five quantified drivers; the 2024 comparison against the prior-year Form 10-K as published. | |
The rule
Regulation S-K Item 303(b)
Where the financial statements reflect material changes from period-to-period in one or more line items, including where material changes within a line item offset one another, describe the underlying reasons for these material changes in quantitative and qualitative terms.
Version: Text in force at the date of this review · Source: Regulation S-K Item 303 (17 CFR 229.303), as amended by Release 33-10890
Why it applies here. Item 303(b) asks for the underlying reasons for material changes 'including where material changes within a line item offset one another'. A net offset of this size is about [n]% of the absolute pre-tax loss, so whether it is one material decrease (which must be described) or many small ones (which need not be) is a judgment only management can confirm.
Why it matters
A reader cannot see which SG&A costs fell in 2025, or whether the decrease will persist into 2026 alongside the expected fall in settlement costs.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, MD&A results of operations drew 239 of the 1,774 numbered comments (13.5%): the third most frequent topic.
Exposure
A question for management; if a material offsetting decrease exists, the staff could ask for it to be described in future filings.
Our workings
the results table shows SG&A of [n] in 2025 and [n] in 2024. The narrative attributes the increase to [product] antitrust litigation settlements of [amount], the [litigant] litigation settlement of [amount], higher compensation-related expenses of [amount], increased sales and marketing investment of [amount] and [acquired business] integration expenses of [amount].
the increase is [n]; the named drivers total [n], so other SG&A costs fell by [n] in aggregate. Even if the integration expenses were already inside the compensation or marketing figures, the named drivers would total [n] and a decrease of [n] would remain.
| Step | Computation | Result (USD thousands) |
|---|---|---|
| Reported SG&A increase | [n] - [n] = [n] | [n] |
| Named drivers | [n] + [n] + [n] + [n] + [n] = [n] | [n] |
| Unexplained net decrease | [n] - [n] = -[n] | -[n] |
| Excluding integration expenses | [n] + [n] + [n] + [n] = [n]; [n] - [n] = -[n] | -[n] |
| Share of absolute pre-tax loss | [n] / [n] = 5.98% | 5.98% |
| Share of prior-year SG&A | [n] / [n] = 2.71% | 2.71% |
Management’s best defense, and our reply
Management would say Item 303(b) asks only for material offsetting changes, and the residual is the sum of many small decreases across legal, consulting and other general costs, none of them material on its own. They would add that the word 'primarily' signals that the listed drivers are the main ones, not a full bridge. That reading is tenable, which is why this is put as a question rather than a gap. The answer still depends on facts only management holds: if one decrease of the order of [n] to [n] sits behind the residual, it is a material offset that the rule requires to be described.
The fix
- Add, for example: 'partially offset by lower [legal / consulting / other] expenses of $X million', naming each decrease that is material, so the drivers reconcile to the change in the line.
Question for the company
Which costs within selling, general and administrative expenses decreased in 2025 to offset the named increases (which total [n] against a reported increase of [n]), and was any single decrease material enough to require description under Item 303(b)?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Results table: SG&A of [n] in 2025 against [n] in 2024 | Document | Form 10-K 2025, page 91 |
| 2 | Prior-year SG&A in the same table | Document | Form 10-K 2025, page 91 |
| 3 | First three named drivers of the SG&A increase | Document | Form 10-K 2025, page 93 |
| 4 | Last two named drivers; no decrease is named in the 2025 explanation | Document | Form 10-K 2025, page 93 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.