4.01 The revenue policy no longer carries the rebate sentence the company told the SEC staff it would include
Company F · a US-listed networking equipment company · SEC-style question
In brief
To close the staff's 2024 review of the 2023 Form 10-K, the company wrote that, beginning with the 2024 Form 10-K, its revenue recognition policy would state that customer sales rebates are a reduction of revenue, accrued on the amount [wording masked]. The 2024 Form 10-K carried that sentence. The 2025 Form 10-K does not: the word 'rebate' appears nowhere in it, and the variable-consideration paragraph names returns and refund obligations but not rebates. We ask whether the change was deliberate.
The evidence, as filed
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Revenue recognition policy with no sentence on customer sales rebates; no mention of rebates anywhere in the 2025 Form 10-K | The rebate sentence promised to the staff in the letter of [date] and given in the 2024 Form 10-K, or a recorded reason why it is no longer needed |
| What we checked. Staff letters of [date], [date], [date] and the closing letter of [date]; company replies of [date], [date] and [date]; the 2024 and 2025 revenue recognition and receivables policies | |
The rule
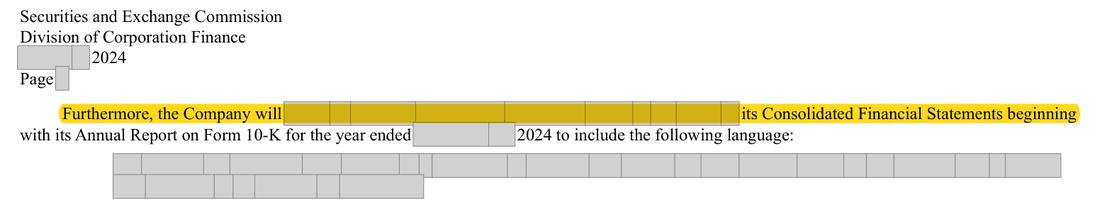
Company letter to the SEC staff of [date]
Why it applies here. the undertaking was phrased as continuing ('beginning with'), so its omission one year later is a departure from what the staff was told; whether it matters depends on whether rebates are still a significant policy, which the report does not say.
Why it matters
A staff review comparing the 2025 Form 10-K with the 2024-25 correspondence would see a commitment given and then dropped; the usual result is a further comment and a fresh future-filings undertaking.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, revenue recognition and disclosure drew 68 of the 1,774 numbered comments (3.8%): topic 7 of 25 by frequency.
Exposure
No penalty; at most a staff comment in a future review
Our workings
the staff's letter of [date] asked why sales rebates and return reserves [wording masked]. The company's reply of [date] said the amounts were immaterial ([amount] at the end of 2023), undertook to show them as a liability in future filings, to strike the rebate words from the receivables policy, and to add to the revenue recognition policy, beginning with the 2024 Form 10-K, the sentence: 'We account for [wording masked] for such rebates based on [wording masked] by customers.' The staff closed its review on [date].
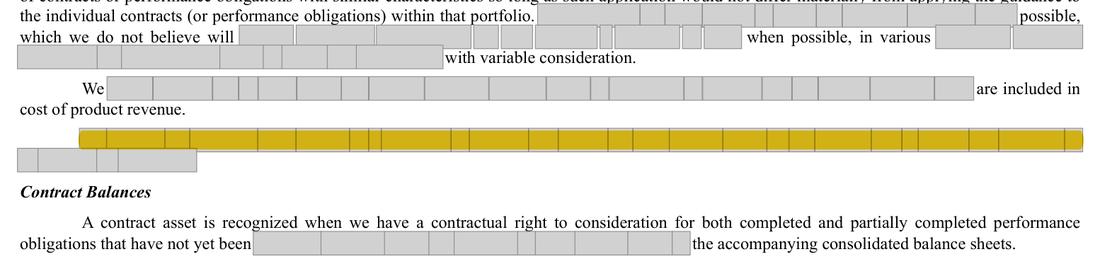
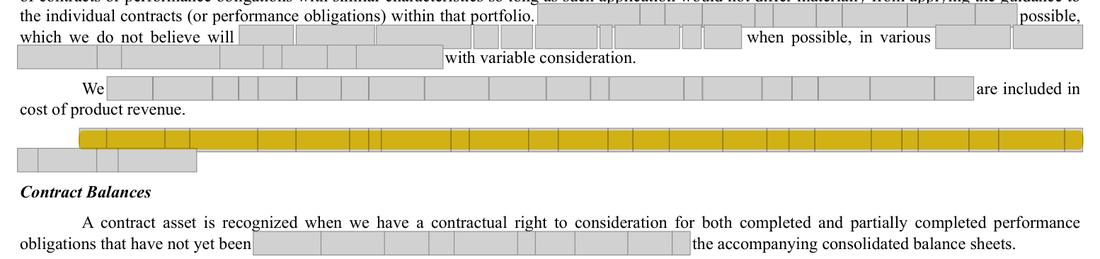
the 2024 Form 10-K gives the sentence. The 2025 Form 10-K keeps the struck receivables wording but its revenue policy goes straight from 'We report revenue net of sales taxes' to 'Contract Balances' with no rebate sentence, and the variable-consideration paragraph lists [wording masked] refund obligations only.
the Forms 10-Q for March and [date] do not mention rebates either.
| Commitment in the reply of [date] | Form 10-K for 2024 | Form 10-K for 2025 |
|---|---|---|
| Rebate sentence added to the revenue recognition policy | Given | Not given |
| Rebate and return words struck from the receivables policy | Done | Done |
| Rebates and return reserves shown as a liability, not netted against receivables | No contra-receivable caption | No contra-receivable caption; no rebate caption in liabilities |
Management’s best defense, and our reply
The company can say the sentence was editorial: rebates are variable consideration, the retained paragraph on variable consideration and refund obligations covers them, and the amounts were small (it told the staff they were [amount] at the end of 2023), so the accounting-policy standard does not demand a separate sentence. It can add that the staff's closing letter made no wording a continuing condition. However, the letter promised the wording 'beginning with' the 2024 report, which reads as continuing, and the 2025 list of variable-consideration items names returns and refund obligations but not rebates. Because the materiality argument is reasonable, the point is put as a question rather than a gap.
The fix
- Restore in the revenue recognition policy: 'We account for [wording masked] for such rebates based on [wording masked] by customers', or minute why the sentence is no longer needed.
Question for the company
Was the sentence on customer sales rebates, which the company told the SEC staff in [date] it would include beginning with the 2024 Form 10-K, removed from the 2025 revenue recognition policy on purpose; if so, on what basis (for example, that rebates are no longer a significant policy), and are rebate accruals still recorded as a liability rather than against receivables?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The company's undertaking to the staff to add wording to the revenue recognition policy, beginning with the 2024 Form 10-K | Document | |
| 2 | The exact sentence promised | Document | |
| 3 | The company's own measure of the amounts at the end of 2023 and 2022 | Document | |
| 4 | The staff closed the review after the company's undertakings | Document | |
| 5 | The 2024 Form 10-K delivered the sentence | Document | Form 10-K 2024 (prior year), page 85 |
| 6 | The 2025 variable-consideration paragraph does not name rebates | Document | Form 10-K 2025, page 78 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- We report revenue net of sales taxes
- What is missing
- the sentence on customer sales rebates that the 2024 report gave at this point
- Pages looked at
- p.68 (balance sheet), p.74 (receivables policy), p.77-78 (revenue recognition policy), p.61 (critical accounting estimates)
- Result
- none of the terms hits anywhere in the 2025 Form 10-K
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.