6.01 The exhibit index no longer lists the related-party leases filed as material contracts at the offering, and the 2025 Loft lease amendment was not filed
Company E · a US-listed home furnishings retailer · SEC-style question
In brief
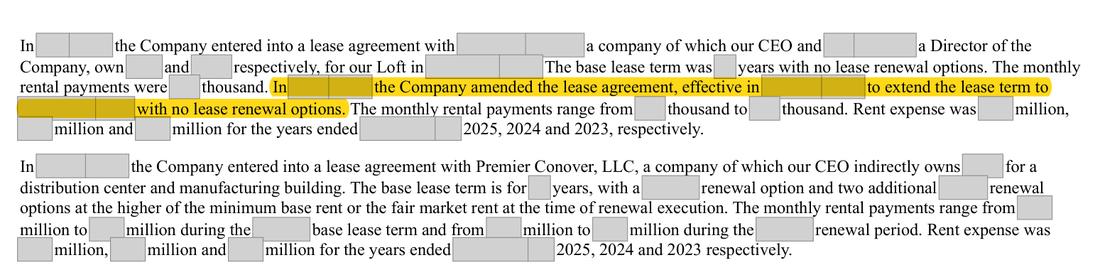
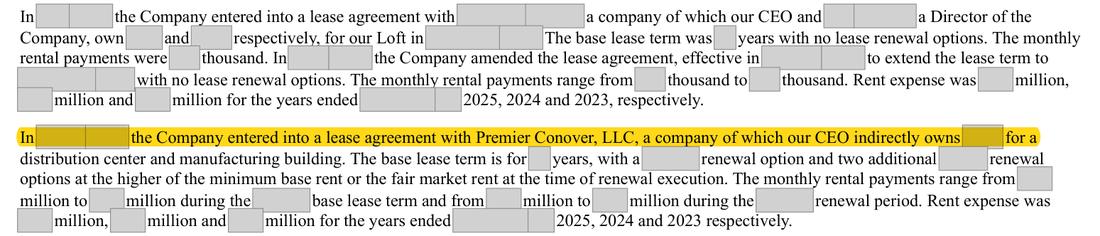
At the initial public offering the Company filed as material contracts its leases with entities in which the Chief Executive Officer (CEO) holds interests: the Conover distribution center, the Walton Hills warehouse and the [city], [state] Loft. All three remain in force (the Loft lease was extended in [date] to [n]), but the exhibit index of this Form 10-K lists none of them, and the [date] amendment was not filed with the quarterly report for that period. We ask whether management has concluded that these leases are no longer material contracts, and on what basis.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
The exhibit index lists no lease; Note 12 shows the three related-party leases in force, one amended in [date]; the registration statement for the offering filed them as exhibits. | Either the three leases and their amendments listed as material contracts, incorporated by reference to the registration statement, with the [date] Loft amendment filed; or a considered conclusion that they are immaterial in amount and significance. |
The rule
Regulation S-K Item 601(b)(10)(ii)
If the contract is such as ordinarily accompanies the kind of business conducted by the registrant and its subsidiaries, it will be deemed to have been made in the ordinary course of business and need not be filed unless it falls within one or more of the following categories, in which case it shall be filed except where immaterial in amount or significance:
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.601(b)(10)(ii) (eCFR current text)
Regulation S-K Item 601(b)(10)(ii)(A)
Any contract to which directors, officers, promoters, voting trustees, security holders named in the registration statement or report, or underwriters are parties
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.601(b)(10)(ii)(A) (eCFR current text)
Regulation S-K Item 601(b)(10)(ii)(D)
Any material lease under which a part of the property described in the registration statement or report is held by the registrant.
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.601(b)(10)(ii)(D) (eCFR current text)
Regulation S-K Item 601, Instruction 3 to paragraph (b)([n])
If a material contract is executed or becomes effective during the reporting period reflected by a Form 10-Q or Form 10-K, it must be filed as an exhibit to the Form 10-Q or Form 10-K filed for the corresponding period.
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.601(b)(10), Instruction 3 (eCFR current text)
Why it applies here. contracts the Company itself treated as material at the offering, with an entity part-owned by the CEO and covering a distribution center described in Item 1, remain fileable while they are being performed; nothing in the filing explains why they ceased to be material. Against this, the leases are ordinary-course real estate contracts whose combined rent is a small fraction of revenue, and the CEO holds his interests through entities rather than being a party himself, so whether the filing requirement still applies turns on a judgment of significance that only management can explain; the point is therefore put as a question. If the leases are still material contracts the remedy is simple, since earlier-filed exhibits can be incorporated by reference.
Why it matters
Investors cannot reach the terms of the founder-linked leases, including the Conover distribution center lease and the 2025 Loft extension to [n], from the current filing.
Exposure
A question for management; if the leases remain material contracts, the realistic outcome is a staff comment asking for them to be listed or filed with the next periodic report.
Our workings
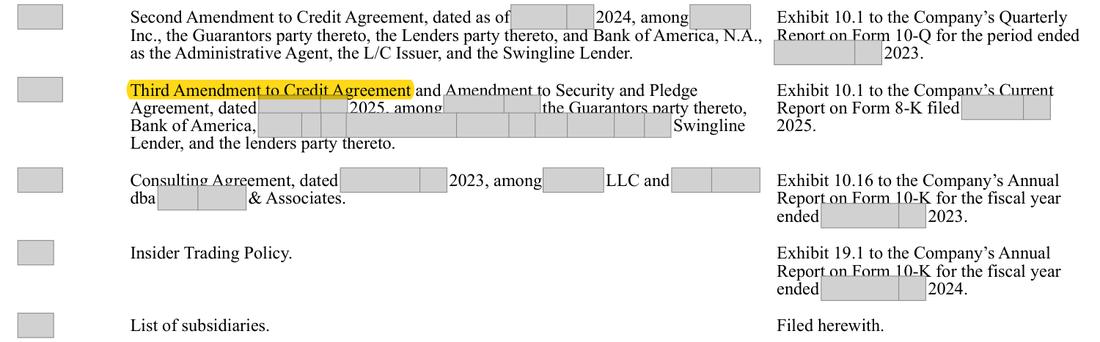
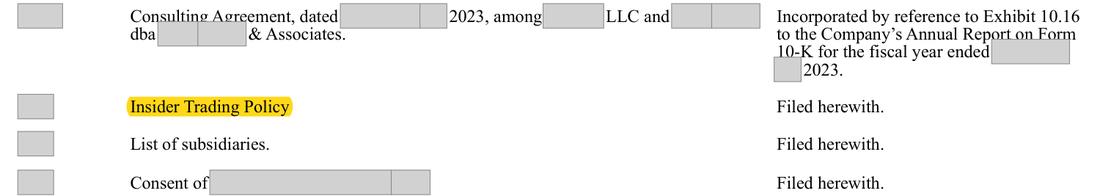
the registration statement for the initial public offering filed the Premier Conover lease, the Pagoda Partners warehouse lease and its amendments and the [city] the Company lease as exhibits. Note 12 of this Form 10-K shows the same three leases still in force; the Loft lease was amended in [date] to run to [date]. Item 1 describes the Conover facility as one of the Company's three distribution centers. The exhibit index of this Form 10-K lists no lease at all, and the Form 10-Q for the quarter ended [date] filed only an employment letter as a new contract. Law: a contract that ordinarily accompanies the business must still be filed, unless immaterial in amount or significance, when directors or officers are parties to it or when it is a material lease under which property described in the report is held; a material contract executed in a period is filed with the report for that period.
Management’s best defense, and our reply
Management could argue that real estate leases ordinarily accompany a retailer's business and that these three are now immaterial in amount, with combined rent well below one percent of revenue, so they no longer need to be filed; it could add that the CEO is not personally a party, only an entity in which he holds an interest. That reading is tenable for leases of this size, which is why the point is put as a question. However, the related-party category applies unless the contract is immaterial in amount or significance, and significance is the point for leases with entities part-owned by the CEO; the Conover lease also falls within the separate category for material leases of property described in the report, since Item 1 names Conover as one of three distribution centers, and the Company treated all three as material at the offering without the filing giving a reason for the change.
The fix
- If the leases remain material contracts, list the three leases and their amendments in the exhibit index, incorporated by reference to the exhibits of the registration statement, and file the [date] Loft lease amendment and any later amendment of the other two leases not yet filed.
Question for the company
Has management concluded that the leases with Premier Conover, Pagoda Partners and [city] the Company, and the [date] amendment of the Loft lease, are no longer material contracts that must be listed or filed, and if so on what basis, given that the Company filed all three as material contracts at the offering?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | registration statement: the Conover distribution center lease filed as a material contract | Document | |
| 2 | registration statement: the Walton Hills warehouse lease filed | Document | |
| 3 | registration statement: the [city], [state] lease filed | Document | |
| 4 | the Loft lease was amended in [date] | Document | Form 10-K 2025, page 80 |
| 5 | the Conover lease is with an entity part-owned by the CEO and remains in force | Document | Form 10-K 2025, page 80 |
| 6 | Item 1 describes the distribution centers, Conover among them | Document | Form 10-K 2025, page 9 |
| 7 | the only contract filed with the Form 10-Q for the quarter in which the Loft lease was amended | Document |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Third Amendment to Credit Agreement
- What is missing
- the related-party leases (Premier Conover, Pagoda Partners, [city] the Company) and their amendments among the material contracts
- Pages looked at
- p.89-92
- Result
- 'Premier Conover' and '[city] the Company' hit only p.80 and 'Pagoda' only p.79, all in Note 12 describing the leases, not in the exhibit index; 'Lease, dated' and 'Industrial Real Estate Lease' do not hit anywhere in the report.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.