7.01 Forepart drafting slips: one table-of-contents page number and two risk-factor wording errors
Company E · a US-listed home furnishings retailer · Drafting slip
In brief
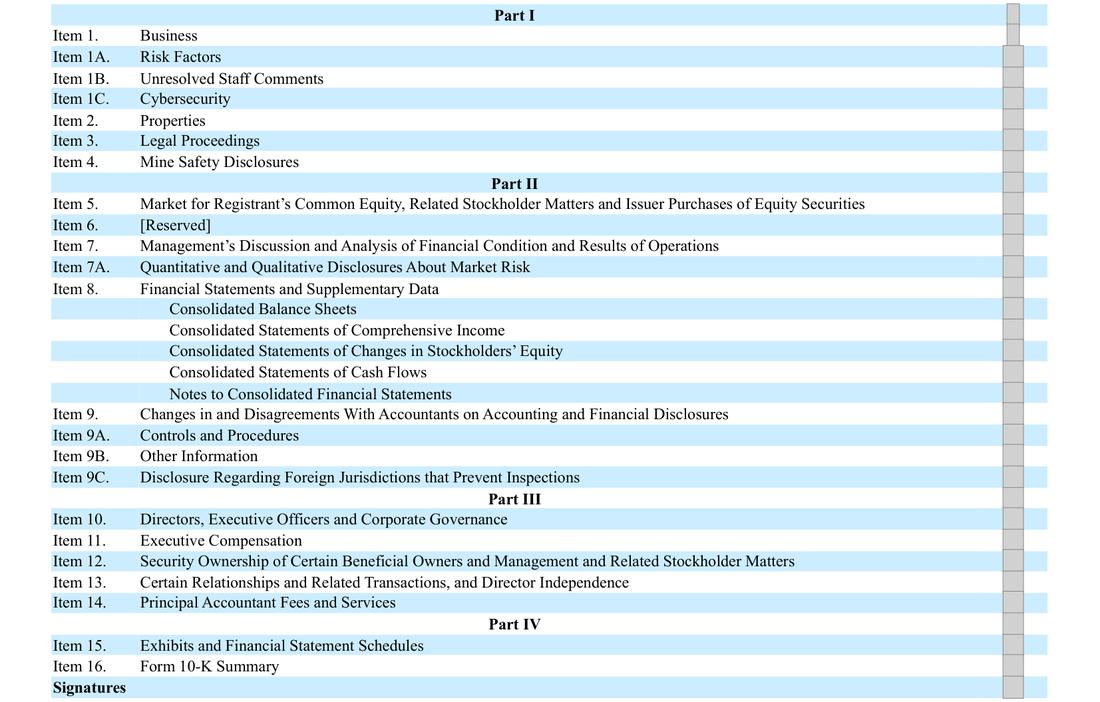
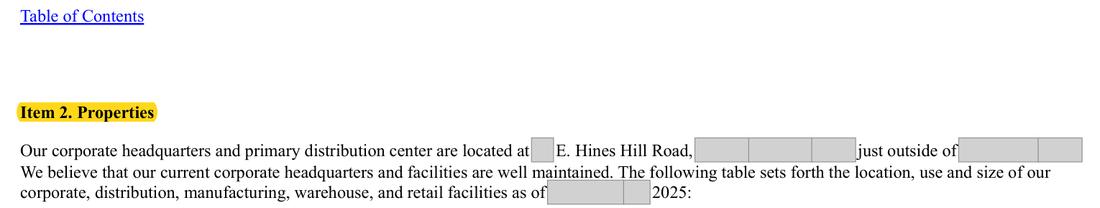
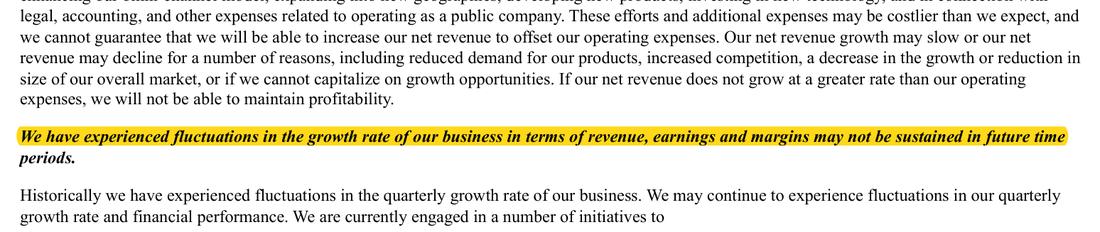
The table of contents sends the reader to page 38 for Item 2 Properties, but the Item 2 heading is printed on page 39. In Item 1A, one summary bullet reads 'as a result of our the continued integration', and the sub-caption of the growth-fluctuation risk factor lost words in editing and no longer reads as a sentence.
The evidence, as filed
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Table of contents: Item 2 Properties at page 38 (heading on page 39). Summary bullet: 'as a result of our the continued integration'. Sub-caption: 'We have experienced fluctuations in the growth rate of our business in terms of revenue, earnings and margins may not be sustained in future time periods.' | Item 2 Properties at page 39. 'as a result of the continued integration'. 'We have experienced fluctuations in the growth rate of our business in terms of revenue, earnings and margins, which may not be sustained in future periods.' |
Why it matters
A reader following the table of contents lands one page early; the two wording slips read as careless drafting in a section the staff reads closely.
Exposure
No requirement breached; cosmetic.
Our workings
every other table-of-contents page number agrees with the page on which its item starts; Item 2 is the only one that does not. The prior-year table of contents gave the right page for Item 2.
the summary bullet carries the same doubled word as in the prior-year report.
the prior-year sub-caption read 'our business and our high rates of growth in terms of revenue, earnings and margins may not be sustained'; this year's edit removed 'and our high rates of growth' without adding 'which', so the sentence no longer parses (the matching summary bullet does include 'which').
these are cosmetic slips; no figure or required disclosure is affected.
Management’s best defense, and our reply
The company could say that the table of contents is a navigation aid that is hyperlinked in the filed document, so a one-page offset has no effect on an electronic reader, and that the wording slips do not change the meaning of the risks. That is fair as to substance; however, the points are still worth correcting before the next filing because they are trivial to fix and the doubled word has now been carried for two years.
The fix
- Change the Item 2 page reference to [n]; delete 'our' before 'the continued integration'; insert ', which' after 'earnings and margins' in the sub-caption.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Table of contents gives page 38 for Item 2 Properties | Document | Form 10-K 2025, page 1 |
| 2 | Item 2 heading is printed on page 39 | Document | Form 10-K 2025, page 39 |
| 3 | Summary bullet with the doubled word 'our the' | Document | Form 10-K 2025, page 12 |
| 4 | Risk-factor sub-caption missing 'which' | Document | Form 10-K 2025, page 12 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.