5.01 How far does the net revenue analysis meet the [date] undertaking to the SEC staff to quantify each factor?
Company E · a US-listed home furnishings retailer · SEC-style question
In brief
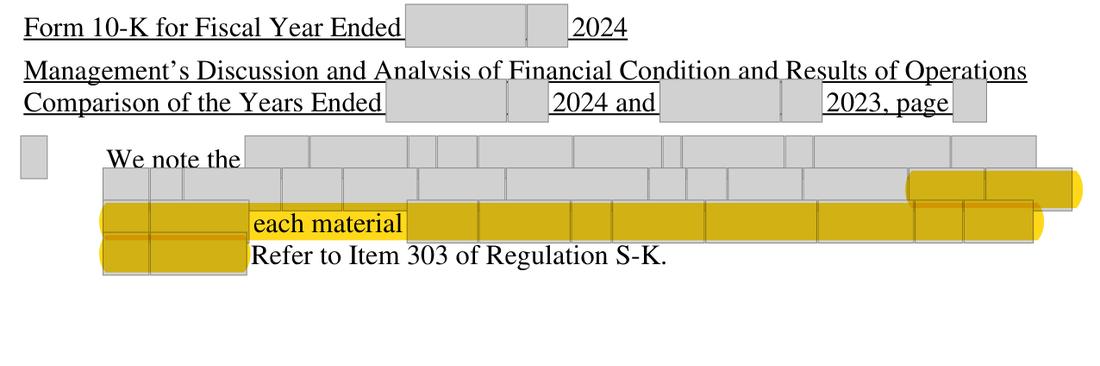
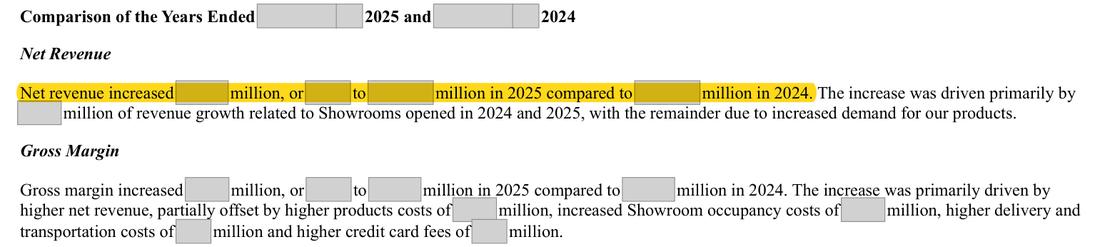
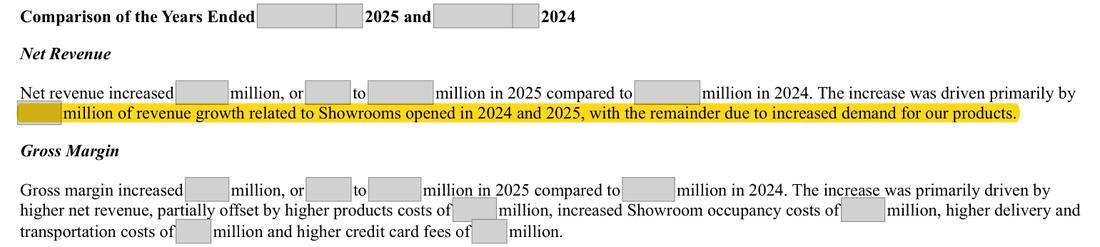
In [date] the SEC staff asked the company to [wording masked] behind the change in net revenue, including factors that offset one another, and the company undertook to do so in future filings. The fiscal 2025 MD&A explains the [amount] increase by [amount] from Showrooms opened in 2024 and 2025, 'with the remainder due to increased demand'. That remainder works out to [amount], about two-fifths of the change, and is given one qualitative label. We ask how management assessed this paragraph against its undertaking.
The evidence, as filed
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Net revenue up [amount]: [amount] new Showrooms; the remaining [amount] (computed) described only as 'increased demand' | Each material driver of the remaining change quantified (for example comparable Showroom and eCommerce volume, pricing, delivery timing), or a statement that the remainder cannot be split further |
| What we checked. Staff letter of [date], company response of [date], staff completion letter of [date]; FY2025 MD&A net revenue paragraph; revenue by sales channel in the segment note | |
The rule
Regulation S-K Item 303(b)
Where the financial statements reflect material changes from period-to-period in one or more line items, including where material changes within a line item offset one another, describe the underlying reasons for these material changes in quantitative and qualitative terms.
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.303, as amended by Release 33-10890 (2020)
Regulation S-K Item 303(b)(2)(iii)
describe the extent to which such changes are attributable to changes in prices or to changes in the volume or amount of goods or services being sold or to the introduction of new products or services.
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.303, as amended by Release 33-10890 (2020)
Why it applies here. the paragraph follows the format of the sample disclosure the company gave the staff and quantifies one driver, so it is responsive in form; whether 'increased demand' is a single material factor, or a blend of comparable-Showroom volume, eCommerce growth, pricing and delivery timing that the company's own data could separate, is a judgment only management can explain.
Why it matters
If the staff selects the next Form 10-K for review, an undertaking given to it and met only in part is a likely subject of a further comment.
Exposure
No penalty; at most a further staff comment asking for the remaining drivers to be quantified in future filings.
Our workings
the staff letter of [date] asked the company, to the extent possible, to [wording masked] in net revenue, including changes that offset one another. The company's response of [date] undertook, from the Form 10-Q for the quarter ending [date] and in future filings, to describe and quantify [wording masked]; the staff completed its review on [date]. The fiscal 2025 MD&A states that net revenue increased [amount] and attributes [amount] [wording masked] 2024 and 2025, with the remainder due to increased demand. The segment note shows retail revenue of [n] against [n] and eCommerce of [n] against [n] (thousand), and the MD&A table gives comparable delivered sales of [n]%.
the remainder is [n] - [n] = [n], or [n] / [n] = 40.4% of the change; retail grew [n] and eCommerce [n].
| Step | Computation | Result |
|---|---|---|
| Remainder attributed to increased demand ($ million) | [n] - [n] = [n] | [n] |
| Share of the change carried by the remainder | [n] / [n] = 40.4% | 40.4% |
| Retail channel change (USD thousand) | [n] - [n] = [n] | [n] |
| eCommerce channel change (USD thousand) | [n] - [n] = [n] | [n] |
Management’s best defense, and our reply
Management would say the paragraph does what was promised: it isolates and quantifies the largest identifiable driver, new Showrooms, and the remainder is arithmetically fixed and is itself a single factor, organic demand, which the comparable delivered sales figure in the same table already measures. The undertaking was given 'to the extent possible', the paragraph follows the sample wording the company showed the staff, and the staff closed its review on that basis. That reading is tenable, so the point is put as a question; however, the remainder is about two-fifths of the change and the company's own channel and comparable-sales data suggest it could be split further.
The fix
- Split the remainder in the next filing, for example: 'The remaining increase of [amount] reflects comparable Showroom and eCommerce growth of $x million and pricing of $y million, partially offset by ...'; or state that it cannot be split further and why.
Question for the company
Of the [amount] of the 2025 net revenue increase attributed to increased demand, how much came from comparable Showrooms, eCommerce, price changes and delivery timing, and how did management conclude that the paragraph meets the undertaking given to the SEC staff on [date]?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | the staff's comment on the fiscal 2024 Form 10-K MD&A | Document | |
| 2 | the company's undertaking for the Q2-2025 Form 10-Q and future filings | Document | |
| 3 | the staff closed the review on [date] | Document | |
| 4 | the change to be explained | Document | Form 10-K 2025, page 47 |
| 5 | one driver quantified; the remainder labelled increased demand | Document | Form 10-K 2025, page 47 |
| 6 | comparable delivered sales growth given in the same section | Document | Form 10-K 2025, page 47 |
| 7 | retail channel revenue 2025, 2024, 2023 | Document | Form 10-K 2025, page 78 |
| 8 | eCommerce channel revenue 2025, 2024, 2023 | Document | Form 10-K 2025, page 78 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.