4.03 No one signs the Form 10-K as controller or principal accounting officer
Company C · a US-listed specialty healthcare products company · Compliance or disclosure gap
In brief
Form 10-K must be signed by the principal executive officer, the principal financial officer, the controller or principal accounting officer, and a majority of the board; a person who holds two of these positions must state each capacity. The signature page lists the Chief Executive Officer as principal executive officer and the Chief Financial Officer as principal financial officer, then the directors. No signature is given in the capacity of controller or principal accounting officer, and the 2024 Form 10-K has the same gap.
The evidence, as filed
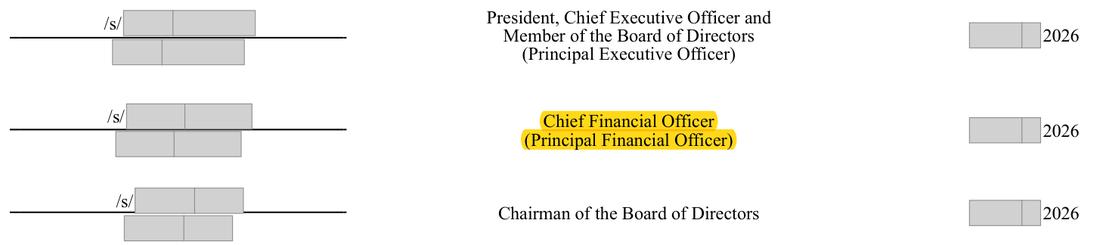
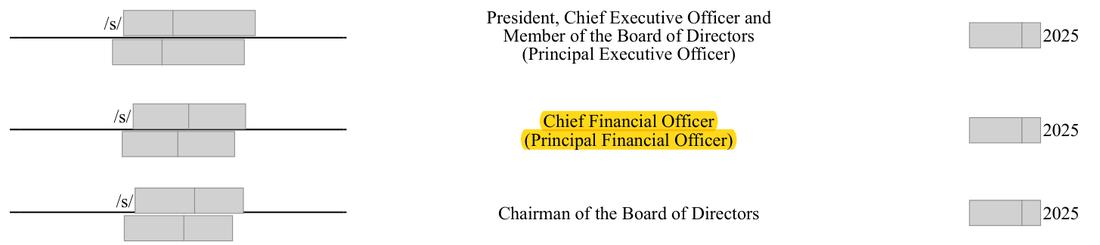
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Signatures page: the Chief Financial Officer signs as 'Chief Financial Officer (Principal Financial Officer)'; no signatory is designated controller or principal accounting officer; the 2024 Form 10-K is the same. | The officer who acts as principal accounting officer signs in that capacity; if it is the Chief Financial Officer, the title reads 'Chief Financial Officer (Principal Financial Officer and Principal Accounting Officer)'. |
| What we checked. Signatures page of the 2025 and 2024 Forms 10-K; the whole 2025 report searched for the capacity; the 2026 proxy statement list of executive officers. | |
The rule
Form 10-K, General Instruction D(2)(a) and (b) (Signatures)
Any person who occupies more than one of the specified positions shall indicate each capacity in which he signs the report.
Version: Text in force at the date of this review · Source: Form 10-K General Instructions (SEC Form 10-K, OMB 3235-0063, current revision)
Form 10-K, General Instruction D(2)(a)
controller or principal accounting officer, and by at least the majority of the board
Version: Text in force at the date of this review · Source: Form 10-K General Instructions (SEC Form 10-K, OMB 3235-0063, current revision)
Why it applies here. the Chief Financial Officer probably performs the principal accounting officer function, but the report does not say so, and General Instruction D(2)(b) requires a person holding more than one of the listed positions to state each capacity. Board majority is met: all six directors sign. The grey area: the staff has treated an omitted principal accounting officer capacity as a signature deficiency and asks the registrant to confirm who performs the function; where that officer already signed in another capacity, the staff usually accepts a commitment to correct the caption in future filings rather than an amendment.
Why it matters
The report does not show that the officer responsible for the accounting records has signed it, which General Instruction D(2) requires; the same caption has now been used in two consecutive annual reports.
Exposure
A staff comment asking who performs the principal accounting officer function and a commitment to correct the signature caption in future filings; in a strict case, a Form 10-K/A with a complete signature page.
Our workings
the signatures page of the Form 10-K for 2025 shows seven signatures: the President and Chief Executive Officer (also a director) as principal executive officer, the Chief Financial Officer as principal financial officer, the Chairman and four directors. The words 'principal accounting officer', 'accounting officer', 'controller' and 'chief accounting officer' do not appear anywhere in the report except the Item 14 heading ('Principal Accounting Fees and Services'). The 2026 proxy statement lists three executive officers (Chief Executive Officer, Chief Financial Officer, Chief Medical Officer), so no separate controller or chief accounting officer is named. The 2024 Form 10-K signature page has the same pattern (Chief Financial Officer signing only as principal financial officer).
Management’s best defense, and our reply
Management would say the Chief Financial Officer is in fact the principal accounting officer, has signed the report and certified it under sections 302 and 906, so the person the instruction is aimed at has signed and nothing of substance is missing. They would add that the caption has been used for years without comment and that the board majority is met. However, the instruction does not only require the right person to sign; it requires a person who holds two of the listed positions to indicate each capacity, and no capacity of controller or principal accounting officer appears anywhere on the page. The answer: a caption change in the next report cures it; it does not undo the omission in the reports already filed.
The fix
- Caption the Chief Financial Officer's signature 'Chief Financial Officer (Principal Financial Officer and Principal Accounting Officer)', or add the signature of the officer who serves as controller or principal accounting officer.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The Chief Financial Officer signs only as principal financial officer | Document | Form 10-K 2025, unnumbered page |
| 2 | The Chief Executive Officer signs as principal executive officer and director; no accounting-officer capacity | Document | Form 10-K 2025, unnumbered page |
| 3 | The 2026 proxy statement table of executive officers lists three: the Chief Executive Officer, the Chief Financial Officer and the Chief Medical Officer; none is a controller or chief accounting officer | Document | |
| 4 | The signature table of the 2025 Form 10-K | Document | Form 10-K 2025, unnumbered page |
| 5 | The chief financial officer signs as principal financial officer only | Document | Form 10-K 2025, unnumbered page |
| 6 | The 2024 Form 10-K signature table had the same capacity | Document | Form 10-K 2024 (prior year), unnumbered page |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- SIGNATURES
- What is missing
- A signature in the capacity of controller or principal accounting officer (or that capacity stated against an officer who already signs)
- Pages looked at
- unnumbered page (signatures), p.102 (exhibit index), p.1-3 (cover and contents)
- Result
- Only 'principal accounting' hits, on roman-numbered front matter, in the contents line for Item 14 ('Principal Accounting Fees and Services'): that is a heading, not a signature capacity. 'accounting officer', 'controller' and 'chief accounting' have no hits.
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Signature
- What is missing
- A signature in the capacity of controller or principal accounting officer
- Pages looked at
- unnumbered page (signatures); Form 10-K 2024 (prior year) unnumbered page
- Result
- No term hits anywhere in the report.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.