4.02 Neither Form 10-K lists the [date] amendment that doubled the share reserve of the inducement plan, which stockholders did not approve
Company C · a US-listed specialty healthcare products company · Compliance or disclosure gap
In brief
The Board adopted the 2023 [wording masked] Nasdaq inducement exemption, without stockholder approval, and on [date] amended it to raise the share reserve from [n] to [n]. The amendment was filed only as an exhibit to the Form S-8 of [date]. The exhibit index of this Form 10-K, like that of the 2024 Form 10-K, lists only the original plan (exhibit [n]), and no Form 10-Q since has filed the amendment. Item 601(a)(4) requires an amendment to a previously filed exhibit to be filed with a Form 10-Q and Form 10-K, and Item 601(b)(10)(iii)(B) requires a plan adopted without stockholder approval to be filed. The separate point on the former Chief Marketing Officer's employment and separation agreements is carried by another observation.
The evidence, as filed
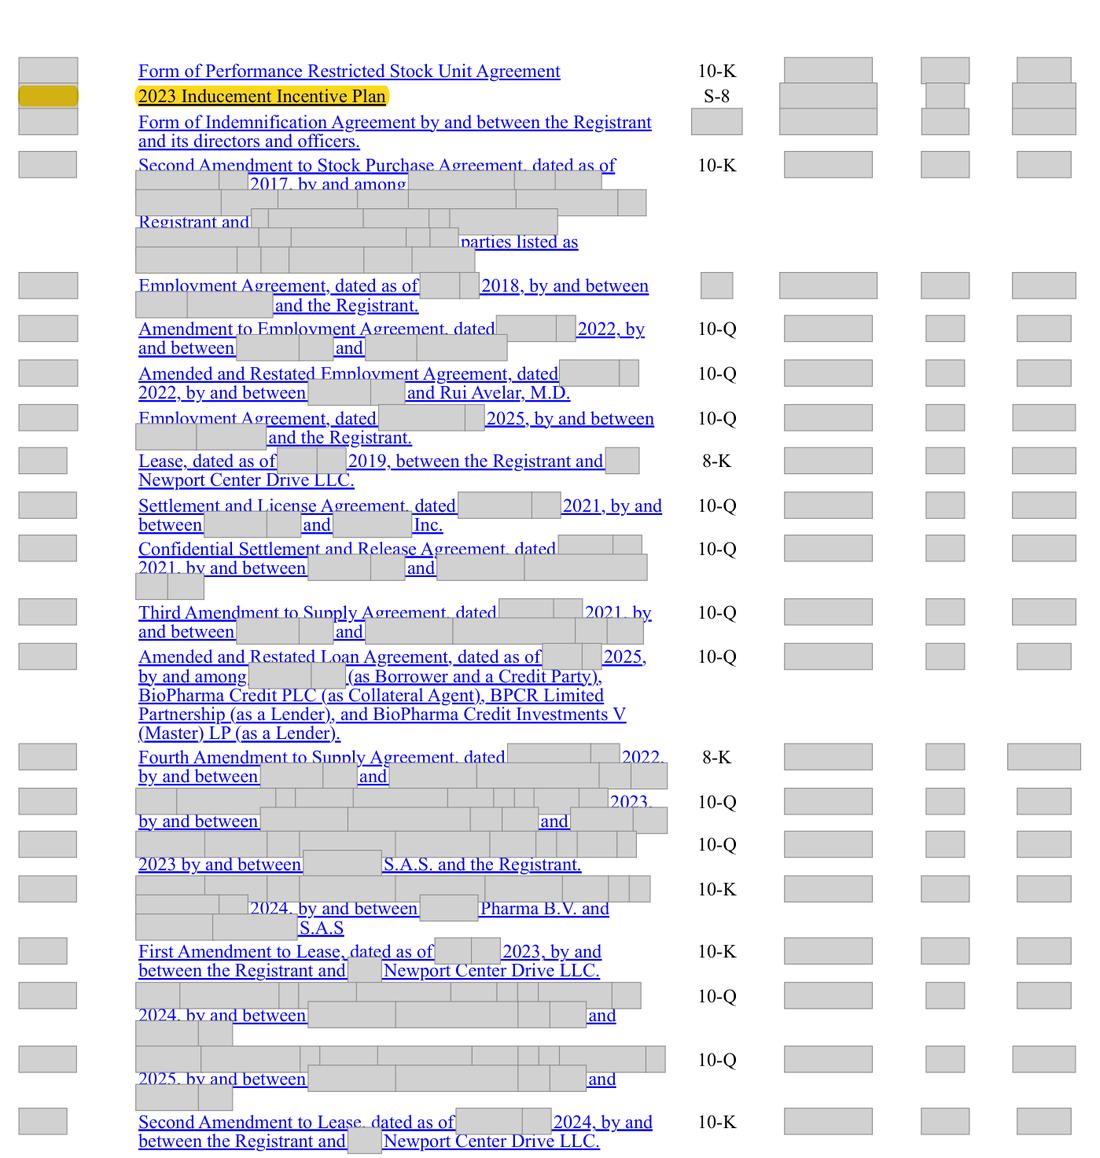
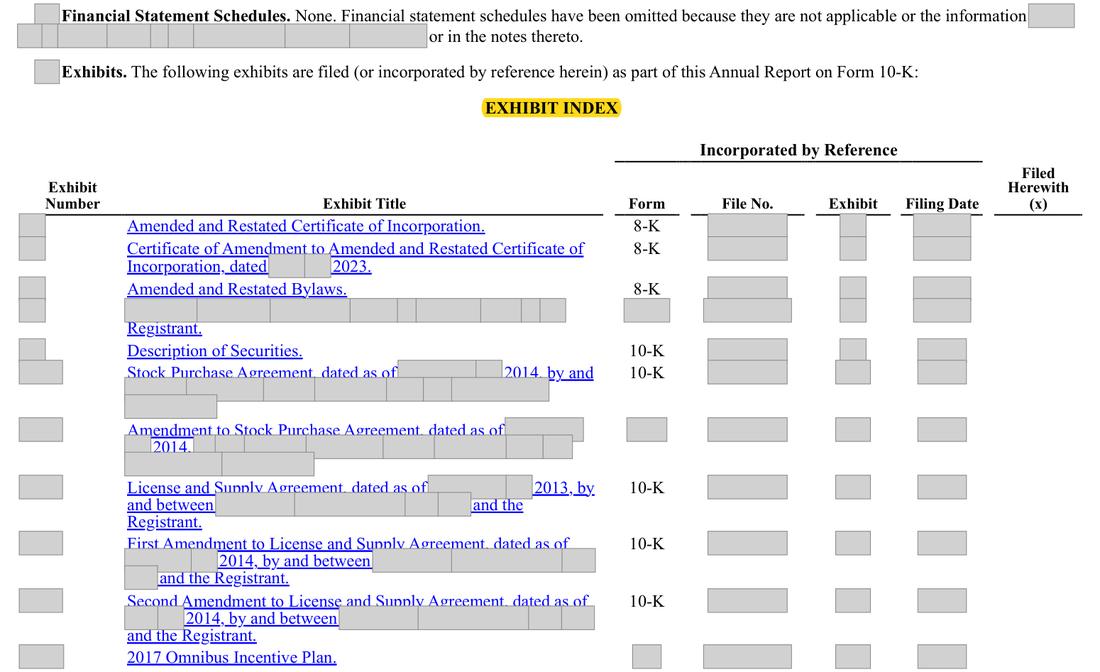
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Exhibit index: exhibit [n] '2023 Inducement Incentive Plan', incorporated from the Form S-8 of [date] (exhibit [n]); no amendment listed. The 2024 Form 10-K index is the same. Equity note: the plan was adopted by the Board under Nasdaq Listing Rule 5635(c)(4) with [n] shares, and a further [n] were reserved on [date]; [n] were available at [date]. | The exhibit index incorporates by reference the First Amendment to the 2023 Inducement Incentive Plan (Form S-8 filed [date], exhibit [n]), marked as a compensatory plan, next to exhibit [n]. |
| What we checked. Exhibit indexes of both Form 10-Ks; the equity note; the Form S-8 amendment exhibit; the exhibit indexes of the five Forms 10-Q filed from [date] to [date] | |
The rule
Regulation S-K Item 601(b)(10)(iii)(B)
Any compensatory plan, contract or arrangement adopted without the approval of security holders pursuant to which equity may be awarded, including, but not limited to, options, warrants or rights (or if not set forth in any formal document, a written description thereof), in which any employee (whether or not an executive officer of the registrant) participates shall be filed unless immaterial in amount or significance.
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.601(b)(10)(iii)(B)
Regulation S-K Item 601(a)(4)
Any amendment or modification to a previously filed exhibit to a Form 10, 10-K or 10-Q document shall be filed as an exhibit to a Form 10-Q and Form 10-K. Such amendment or modification need not be filed where such previously filed exhibit would not be currently required.
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.601(a)(4)
Why it applies here. Plan amendment missing from the exhibit index in both years
Why it matters
A reader of the exhibit index sees a plan capped at [n] shares although awards under it already exceed that cap; the current terms of an equity plan that stockholders did not approve are not in the report.
Exposure
A staff comment asking for the amendment to be filed or incorporated, usually met in the next periodic report; no fixed penalty.
Our workings
the equity note (p.86, printed [n]) says the Board adopted the Inducement Plan in [date] in accordance with Nasdaq Listing Rule 5635(c)(4), the exemption for plans not approved by stockholders, and reserved [n] shares; on [date] a further [n] were reserved (p.87, printed [n]). The First Amendment, adopted by the Board on [date], restates the plan limit as [n] shares and was filed as exhibit [n] to the Form S-8 of [date]. Exhibit 10.[n] in both Form 10-Ks is the original plan only, and the exhibit indexes of the Forms 10-Q for the quarters from [date] to [date] do not add the amendment.
[n] authorized less [n] available at [date] = [n] shares granted or used under the plan, which is [n] more than the original [n] reserve, so awards already depend on the amendment; the added [n] shares are 1.54% of the [n] shares outstanding.
the plan is a required exhibit under Item 601(b)(10)(iii)(B), as the company itself treats it by listing exhibit [n], and Item 601(a)(4) requires any amendment to a previously filed exhibit to be filed with a Form 10-Q and Form 10-K; the amendment became effective in fiscal 2024, so it was due in the 2024 Form 10-K and remained missing in the 2025 Form 10-K. Filing it with a Securities Act registration statement does not satisfy the Exchange Act report, though incorporation by reference from that filing would.
| Item | Figure | Computation | Result |
|---|---|---|---|
| Inducement plan limit after the First Amendment | [n] | [n] + [n] | [n] |
| Shares granted or used under the plan at [date] | [n] - [n] | [n] - [n] | [n] ([n] above the original [n]) |
| Added reserve as share of common stock outstanding | [n] / [n] | [n] / [n] | 1.54% |
| Document | Where filed | 2024 Form 10-K index | 2025 Form 10-K index | Forms 10-Q, [date] to [date] |
|---|---|---|---|---|
| 2023 Inducement Incentive Plan, original | Form S-8, [date], exhibit [n] | Listed ([n]) | Listed ([n]) | Not needed |
| First Amendment ([date]) | Form S-8, [date], exhibit [n] | Not listed | Not listed | Not filed |
Management’s best defense, and our reply
The company can argue that the amendment is public on EDGAR with the Form S-8, that it only raises the share reserve and is described in the equity note, and that [n] shares, 1.54% of the stock outstanding, are immaterial in amount, which Item 601(b)(10)(iii)(B) allows as an exception. It may add that the plan text other than the share limit is unchanged and is already exhibit [n]. However, Item 601(a)(4) expressly requires an amendment to a previously filed exhibit to be filed with the Form 10-Q and Form 10-K, and lifts that only where the original exhibit is no longer required, which the company contradicts by still listing exhibit [n]. The immateriality exception is hard to apply when [n] shares have already been used against a plan the index shows as capped at [n], so the listed exhibit now misstates the plan in force.
The fix
- Add to the exhibit index: '[n].x+ First Amendment to the 2023 Inducement Incentive Plan (Form S-8, [date], Ex. [n])'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Exhibit 10.[n] is the original inducement plan; no amendment is listed | Document | Form 10-K 2025, page 101 |
| 2 | The Board adopted the plan under the Nasdaq inducement exemption, without stockholder approval | Document | Form 10-K 2025, page 86 |
| 3 | The plan was amended in [date] | Document | Form 10-K 2025, page 87 |
| 4 | Shares still available under the plan at the 2025 year end | Document | Form 10-K 2025, page 87 |
| 5 | Common stock outstanding, used for the size of the added reserve | Document | Form 10-K 2025, page 86 |
| 6 | The First Amendment, filed only with the [date] Form S-8 | Document | |
| 7 | The 2024 Form 10-K index also lists only the original plan | Document | Form 10-K 2024 (prior year), page 102 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- EXHIBIT INDEX
- What is missing
- the First Amendment to the 2023 Inducement Incentive Plan
- Pages looked at
- p.100-102 (exhibit index), p.86-87 (equity note)
- Result
- 'First Amendment' hits p.100 and [n] (first amendments to the [supplier 1] agreement and the office lease, not the plan); 'Inducement Incentive Plan' hits p.86 and [n] (the equity note) and p.101, the original 2023 plan only; '[n]' and 'Amendment to the 2023' do not hit
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.