2.07 MD&A no longer says when the [amount] term loan falls due, or how it will be met beyond the next twelve months
Company C · a US-listed specialty healthcare products company · SEC-style question
In brief
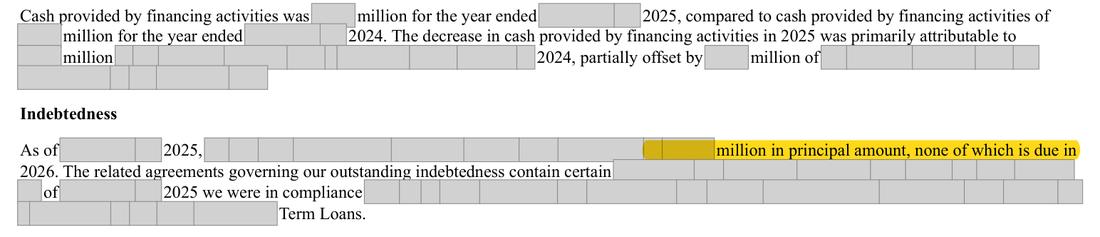
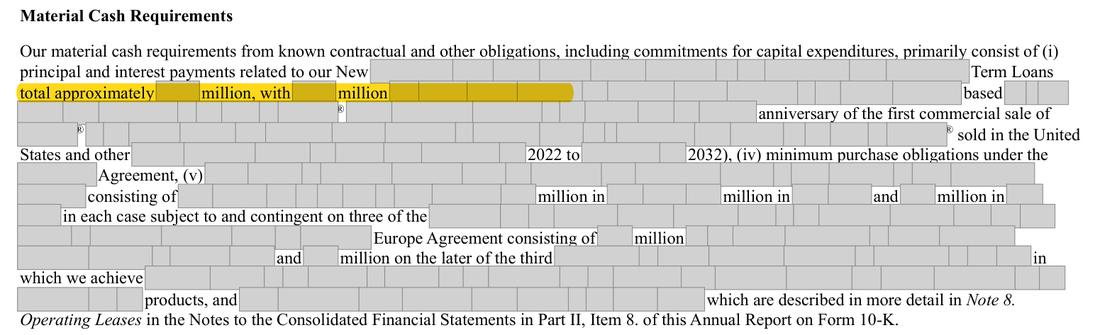
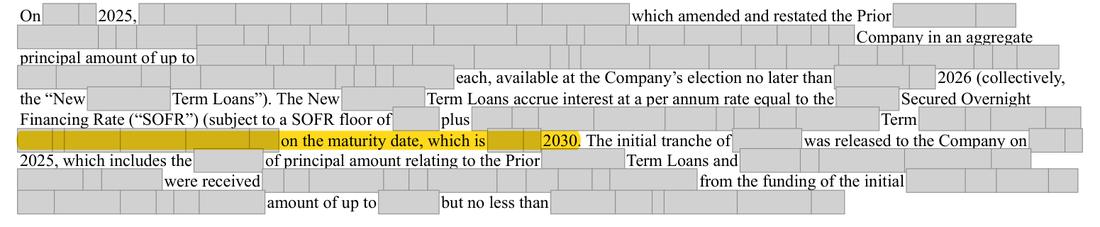
The liquidity discussion lists 'principal and interest payments' on the term loans as a material cash requirement and says none of the [amount] principal is due in 2026, but never says that the whole principal falls due in a single payment on [date]; that date is only in the term loan note. The 2024 Form 10-K's MD&A did give the repayment schedule of the earlier loans. With cash of [amounts] used in operations in 2025, the long-term part of the liquidity analysis is a general statement that the company may access the markets.
The evidence, as filed
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
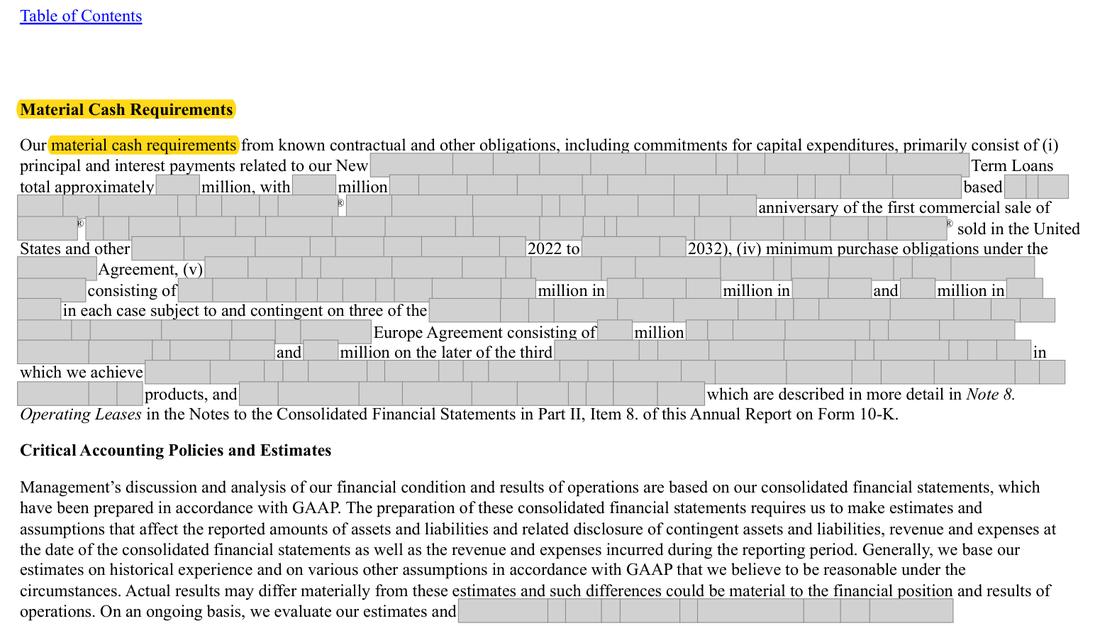
Indebtedness paragraph: [amount] principal, none due in 2026; material cash requirements: interest of about [amounts] within twelve months; no maturity date or repayment profile for the principal in MD&A; long-term funding addressed only in general terms. | The type and timing of the principal requirement (a single payment of [amount] on [date], subject to mandatory prepayment terms) and a long-term analysis of how management expects to meet it. |
| What we checked. MD&A liquidity sections against the term loan note and the 2024 Form 10-K MD&A | |
The rule
Regulation S-K Item 303(b)(1)
Analyze the registrant's ability to generate and obtain adequate amounts of cash to meet its requirements and its plans for cash in the short-term (i.e., the next 12 months from the most recent fiscal period end required to be presented) and separately in the long-term (i.e., beyond the next 12 months). The discussion should analyze material cash requirements from known contractual and other obligations. Such disclosures must specify the type of obligation and the relevant time period for the related cash requirements.
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.303(b)(1), as amended by Release 33-10890
Why it applies here. Maturity and long-term funding analysis for the principal not in MD&A
Why it matters
A reader of MD&A alone cannot see that the company's largest obligation is a single payment more than twice its year-end cash, nor management's plan for it.
Exposure
None while the point is a question; if the cross-reference is found insufficient, a staff comment and future-filings undertaking.
Our workings
MD&A states total indebtedness of [amount] in principal, 'none of which is due in 2026', lists principal and interest on the term loans among the material cash requirements and quantifies only the interest, and for the long term says the company [wording masked]. The term loan note says the loans are interest-only [wording masked] [date]. The 2024 Form 10-K's MD&A described the earlier loans' amortization and maturity (Form 10-K 2024 (prior year) p.55). Cash at year end was [amount] and operations used [amount] in 2025.
Item 303(b)(1) asks for the type of each material cash requirement and its relevant time period, and for a separate long-term analysis; the largest requirement's timing now sits only in the notes. Whether a cross-reference to the note is enough is a judgment the company should explain.
| Item | Amount ($ million) | Where | Due |
|---|---|---|---|
| Term loan principal | [n] | MD&A p.55; Note 7 p.81 | [date] (note only) |
| Future interest on the term loans | [n] | MD&A p.56 | [n] within twelve months |
| Cash and cash equivalents at year end | [n] | MD&A p.51 | |
| Net cash used in operating activities, 2025 | [n] | MD&A p.51 |
Management’s best defense, and our reply
The company can say that MD&A cross-refers to the term loan note, which gives the maturity, that the material cash requirements paragraph names principal and interest, and that Instruction 3 discourages repeating note disclosure. It can add that 2030 is four years away and that the long-term statement about accessing the markets is its honest plan. That is a tenable reading, which is why this is put as a question: the rule asks for the relevant time period of each requirement, and the 2024 MD&A showed the company itself thought the schedule belonged there.
The fix
- Add to Indebtedness: 'The New [former lender] Term Loans are interest-only, with the full [amount] principal due on [date]. We expect to meet this obligation from [operating cash flows / refinancing / the undrawn tranches], and [describe the plan].'
Question for the company
Beyond the next twelve months, how does management expect to meet the [amount] principal due on [date], and why was the repayment profile given in the 2024 MD&A not repeated for the new loans?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | MD&A says only that no principal is due in 2026 | Document | Form 10-K 2025, page 55 |
| 2 | Material cash requirements quantify interest only | Document | Form 10-K 2025, page 56 |
| 3 | The maturity appears only in the term loan note | Document | Form 10-K 2025, page 81 |
| 4 | Long-term funding addressed in general terms | Document | Form 10-K 2025, page 53 |
| 5 | Year-end cash | Document | Form 10-K 2025, page 51 |
| 6 | Operating cash use | Document | Form 10-K 2025, page 51 |
| 7 | The 2024 MD&A gave the earlier loans' maturity | Document | Form 10-K 2024 (prior year), page 55 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Material Cash Requirements
- What is missing
- the due date of the [n] principal and a long-term analysis of how it will be met
- Pages looked at
- p.48-57 (MD&A)
- Result
- '2030' hits p.43 and [n] (office lease expiry), 83-87 (notes, including the term loan maturity on p.81); 'maturity' hits p.52 (the 2026 revolving facility, also described as maturing in three years on p.48), [n] (definition of liquidity) and notes; 'balloon' hits only p.81 (term loan note); 'long-term cash requirements' hits p.53, the general statement quoted above
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.