2.08 The shareholder derivative lawsuit is called ongoing in the risk factors and liquidity discussion but has disappeared from the contingencies note and Item 3 without any statement of how it ended
Company C · a US-listed specialty healthcare products company · SEC-style question
In brief
Last year's Form 10-K described a consolidated shareholder derivative suit in both Item 3 and the contingencies note, stayed until the court ruled on the securities class action, which ended in final judgment for the defendants on [date]. This year's note drops the derivative suit without saying it was dismissed or settled, and Item 3 says the Company is not a party to any material legal proceeding. Yet the risk factor says the Company is [wording masked] and continues a vigorous defense, and the liquidity discussion lists the cost of the ongoing shareholder derivative lawsuit. The quarterly reports for the first three quarters of 2025 (the last filed [date]) still said [wording masked]; the suit first drops out in this Form 10-K, and the 2026 quarterly reports and current reports to [date] say nothing of a dismissal or settlement. Only management can say which description is right.
The evidence, as filed
3 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
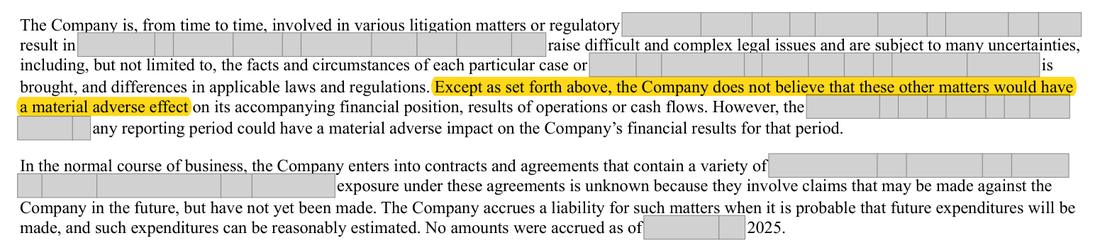
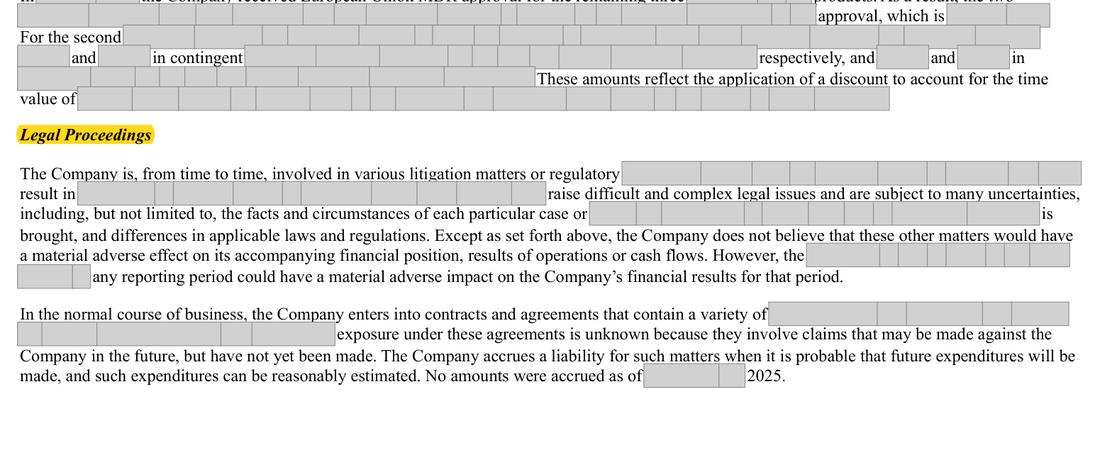
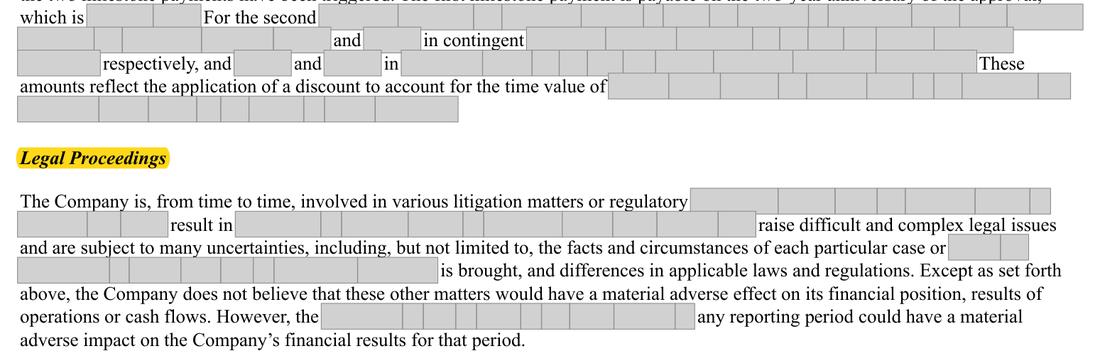
Note 9 has no description of any specific legal matter yet still says 'Except as set forth above'; Item 3: not a party to any material legal proceeding; Item 1A: [wording masked], vigorous defense continues; Item 7: cost of 'our ongoing shareholder derivative lawsuit'. | One consistent position across Note 9, Item 1A, Item 3 and Item 7: either the derivative suit is pending (then described, with its status and the loss-estimate statement) or it has ended (then the date and disposition stated where required, and the risk factor and liquidity bullet updated). |
| What we checked. Whole Form 10-K searched for the derivative suit, the books-and-records demand and the stay; prior-year note and Item 3; Form 10-Q filings for March and [date]. | |
The rule
Regulation S-K Item 103(a), 17 CFR [n](a)
Describe briefly any material pending legal proceedings, other than ordinary routine litigation incidental to the business, to which the registrant or any of its subsidiaries is a party
Version: In force from [date] · Source: Regulation S-K, 17 CFR 229.103, as amended by Release 33-10825
Form 10-K, Part I, Item 3(b)
As to any proceeding that was terminated during the fourth quarter of the fiscal year covered by this report, furnish information similar to that required by Item 103
Version: Text in force at the date of this review · Source: Form 10-K General Instructions and Items, Securities and Exchange Commission, current form
Why it applies here. either the derivative suit ended in 2025 and the risk factor and liquidity bullet were not updated, or it is still pending and the note and Item 3 treat it as immaterial without saying so. Law: Item 103 of Regulation S-K reaches material pending proceedings; Item 3(b) of Form 10-K asks for the date and disposition of a proceeding terminated in the fourth quarter; the US GAAP loss-contingency disclosure guidance requires the nature and a loss estimate, or a statement that none can be made, for reasonably possible losses. A derivative suit is brought on the Company's behalf, so its direct loss exposure is mainly defense cost and indemnification, which is why materiality is the Company's likely answer; the inconsistency between the four places remains either way.
Why it matters
A reader cannot tell whether the Company still faces the derivative suit. The SEC staff commonly asks registrants to reconcile Item 3, the contingencies note and risk factors; a risk factor describing a risk that has already ended, or a note silent on a pending matter, invites a comment and a future-filings undertaking.
Exposure
A question for management; if the staff raised it, the realistic outcome is a comment and an undertaking to revise future filings, with no money exposure.
Our workings
the prior-year note (fiscal 2024) carried three matters - the securities class action (final judgment for the defendants on [date]), the consolidated shareholder derivative suit (stayed by stipulation pending the ruling on the class action) and a books-and-records demand under [state] law.
the fiscal 2025 note keeps only the generic paragraph, including the words 'Except as set forth above', although no legal matter is now set forth above it (only the milestone commitments precede the Legal Proceedings heading); Item 3 states that the Company is not a party to any material legal proceeding required to be disclosed under Item 103 of Regulation S-K.
the risk factor headed 'Derivative lawsuits have been filed against us' says the Company is [wording masked] and continues [wording masked], and the liquidity discussion lists 'the cost [wording masked]'.
| Place in the Form 10-K | Printed page | What it says about the derivative suit |
|---|---|---|
| Note 9 Legal Proceedings | [n] | Nothing; generic paragraph with 'Except as set forth above' |
| Item 3 Legal Proceedings | [n] | Not a party to any material legal proceeding under Item 103 |
| Item 1A risk factor | [n] | [wording masked]; vigorous defense continues |
| Item 7 liquidity | [n] | Cost of 'our ongoing shareholder derivative lawsuit' |
Management’s best defense, and our reply
The Company would say that the derivative suit, brought on the Company's own behalf with the Company as nominal defendant, carries no material loss for the Company, so it falls outside Item 103 and needs no loss-contingency disclosure; the risk factor and the liquidity bullet are cautionary language that does no harm. It might add that the matter ended before or during 2025 and that a concluded, immaterial matter need not be narrated. However, the four places in the same filing still contradict each other: a risk factor that says vigorous defense continues and a liquidity bullet about an 'ongoing' lawsuit cannot both stand beside an Item 3 that says there is no material proceeding, and the note's 'Except as set forth above' points to nothing. The defense is credible on materiality, which is why this is raised as a question rather than a compliance gap.
The fix
- State the status in Note 9 and Item 3 (for example: 'On [date], the consolidated derivative action was [voluntarily dismissed / dismissed]; the Company made no payment') and conform the risk factor and the liquidity bullet; if the suit is pending, describe it in Note 9 with the loss-estimate statement.
Question for the company
What is the status of the consolidated shareholder derivative action that was stayed pending the class-action ruling, and of the books-and-records demand? If either ended in 2025, when and how; if the derivative action is still pending, why does Item 3 say there is no material proceeding while the risk factor and liquidity discussion call it ongoing?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Note 9 refers to matters 'set forth above', but no specific legal matter is described above it in the fiscal 2025 note | Document | Form 10-K 2025, page 85 |
| 2 | Item 3 says there is no material pending proceeding | Document | Form 10-K 2025, page 44 |
| 3 | Item 1A says the Company is [wording masked] | Document | Form 10-K 2025, page 37 |
| 4 | Item 1A treats the derivative litigation as continuing | Document | Form 10-K 2025, page 37 |
| 5 | Item 7 liquidity discussion calls the derivative lawsuit ongoing | Document | Form 10-K 2025, page 54 |
| 6 | Prior-year note: the securities class action ended in final judgment on [date] | Document | Form 10-K 2024 (prior year), page 87 |
| 7 | Prior-year note: the derivative suit was stayed pending the class-action ruling, so its fate turned on that ruling | Document | Form 10-K 2024 (prior year), page 87 |
| 8 | Item 1A sub-caption presents the derivative lawsuits as current | Document | Form 10-K 2025, page 37 |
| 9 | the risk factor cross-refers to Item 3 for the description of these lawsuits | Document | Form 10-K 2025, page 37 |
| 10 | Item 3, the section cross-referred to, describes no lawsuit at all | Document | Form 10-K 2025, page 44 |
| 11 | prior-year Item 3 did describe the derivative suit, so the cross-reference was last true a year earlier | Document | Form 10-K 2024 (prior year), page 44 |
| 12 | first-quarter 2026 Form 10-Q (filed [date]): the liquidity list no longer carries the 'ongoing shareholder derivative lawsuit' item that the Form 10-K listed between these two items | Document | |
| 13 | The 2024 Form 10-K described the stayed derivative suit in Item 3 itself | Document | Form 10-K 2024 (prior year), page 44 |
| 14 | The 2025 risk factor still sends the reader to Item 3, which no longer describes the suit | Document | Form 10-K 2025, page 37 |
| 15 | First-quarter 2025 Form 10-Q (filed [date]): the derivative suit is described and remains stayed | Document | |
| 16 | Second-quarter 2025 Form 10-Q (filed [date]): unchanged | Document | |
| 17 | Third-quarter 2025 Form 10-Q (filed [date]): the last filing that describes the suit, still stayed | Document | |
| 18 | Third-quarter 2025 risk factor still names the company as nominal defendant | Document | |
| 19 | First-quarter 2026 Form 10-Q: Item 1 refers to Note 9, which no longer mentions the derivative suit | Document |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Legal Proceedings
- What is missing
- any description of the shareholder derivative suit or the books-and-records demand carried last year, or a statement of when and how they ended
- Pages looked at
- p.37, [n], 84-85 (page images)
- Result
- 'derivative' hits only p.37 (the risk factor) and p.54 (the liquidity bullet), both quoted here and both calling the suit current; any hits of 'stay' or 'dismiss' are in other subjects, not a legal matter in the note; 'books and records', 'Section 220' and 'Derivative Litigation' as a caption give no hit.
Absence check
- Document
- Company document
- Where it would appear
- Legal Proceedings
- What is missing
- Any description of the derivative suit or the books-and-records demand, or of their dismissal or settlement
- Pages looked at
- First-quarter 2026 Form 10-Q p.40 (Note 9 legal proceedings), p.63 (Part II Item 1); second-quarter 2026 Form 10-Q p.44 and [n]
- Result
- None of the terms hits anywhere in the first-quarter or the second-quarter 2026 Form 10-Q.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.