2.06 The operating cash flow discussion cites a 'higher operating loss' although loss from operations fell, and names its drivers without amounts
Company C · a US-listed specialty healthcare products company · SEC-style question
In brief
Cash used in operating activities rose from [amount] to [amount]. The MD&A puts this down mostly to 'a higher operating loss' and more inventory purchases, but the loss from operations shown earlier in the MD&A fell, from [amount] to [amount]. None of the drivers is given an amount, although the prior-year report quantified each one.
The evidence, as filed
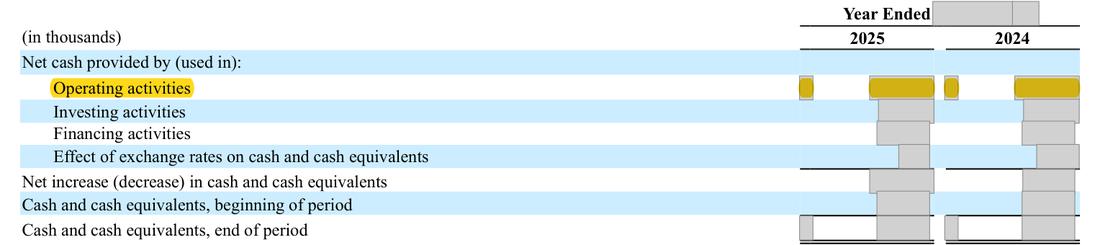
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Increase in cash used of [n] attributed to 'a higher operating loss' and inventory purchases, with no amounts; loss from operations was [n] against [n]. | The measure behind 'operating loss' named (for example the loss after non-cash items, which rose by [n]), and the main drivers quantified: inventories (a [n] swing) and accrued expenses (a [n] swing). |
The rule
Regulation S-K Item 303(b) (full fiscal years), 17 CFR 229.303(b)
Where the financial statements reflect material changes from period-to-period in one or more line items, including where material changes within a line item offset one another, describe the underlying reasons for these material changes in quantitative and qualitative terms.
Version: In force from [date] · Source: Regulation S-K Item 303, 17 CFR [n], as amended by Release No. 33-10890
Regulation S-K Item 303(a) (objective), 17 CFR 229.303(a)
The objective of the discussion and analysis is to provide material information relevant to an assessment of the financial condition and results of operations of the registrant including an evaluation of the amounts and certainty of cash flows from operations and from outside sources.
Version: In force from [date] · Source: Regulation S-K Item 303, 17 CFR [n], as amended by Release No. 33-10890
Why it applies here. the statement holds for net loss ([n] against [n]) or for the loss after non-cash items, but not for loss from operations, the caption the MD&A uses earlier; the measure meant is not named. Item 303(b) asks for the reasons for material changes in quantitative and qualitative terms, and the swings in inventories and accrued expenses together exceed the whole increase in cash used.
Why it matters
A reader comparing the two MD&A pages sees the operating loss described as both lower and higher, and cannot size the inventory build for the Product line 2 launch and tariffs against the timing of payments.
Exposure
A question for management; no penalty is engaged until the answer is known.
Our workings
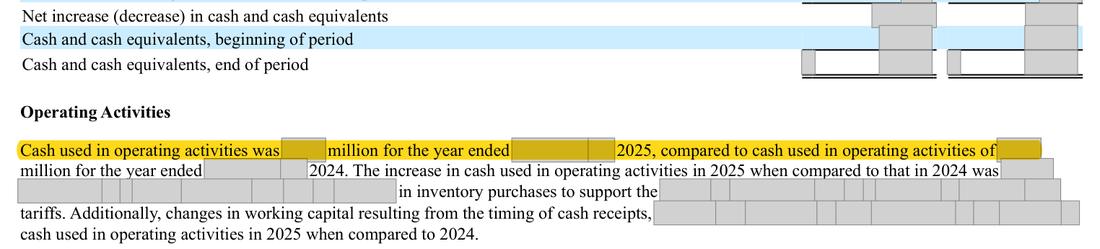
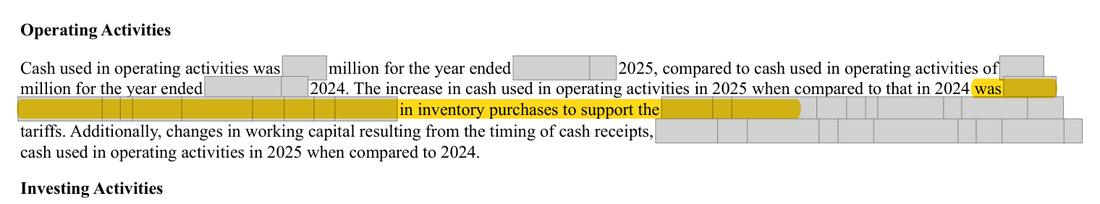
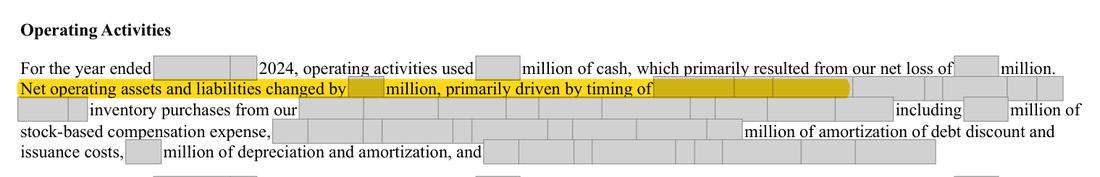
p.55 says the increase in cash used in operating activities 'was mostly attributable to a higher operating loss [wording masked] of Product line 2 and as a response to potential U.S. tariffs', with working-capital timing as a further factor, and gives no amounts. The results table on p.49 shows loss from operations of ([n]) in 2025 against ([n]) in 2024. The cash flow statement (p.65) shows inventories ([n]) against [n] and accrued expenses ([n]) against [n]. The 2024 report quantified its operating cash flow drivers.
cash used rose by [n]; loss from operations fell by [n]; net loss after the non-cash adjustments was [n] against [n], a rise of [n], mainly because the royalty obligation revaluation was a non-cash gain of [n] in 2025 after a non-cash loss of [n] in 2024.
| Item | 2025 | 2024 | Computation | Result |
|---|---|---|---|---|
| Cash used in operating activities | [n] | [n] | [n] - [n] | [n] |
| Loss from operations | [n] | [n] | [n] - [n] | [n] smaller in 2025 |
| Non-cash adjustments 2025 | [n] + [n] + [n] + [n] + [n] + [n] - [n] + [n] | [n] | ||
| Non-cash adjustments 2024 | [n] + [n] + [n] + [n] + [n] - [n] + [n] + [n] | [n] | ||
| Net loss after non-cash items | [n] - [n] = [n] | [n] - [n] = [n] | [n] - [n] | [n] |
| Inventories (cash flow statement) | ([n]) | [n] | [n] + [n] | [n] |
| Accrued expenses (cash flow statement) | ([n]) | [n] | [n] + [n] | [n] |
Management’s best defense, and our reply
Management would say 'operating loss' was meant as the cash loss from operations after non-cash items, which did rise by [n] because the royalty revaluation was a non-cash gain in 2025 and a non-cash loss in 2024. It would add that the cash flow statement gives every working-capital line and Instruction 2 to Item 303(b) excuses reciting amounts readily computable from the statements. That is a reasonable reading, which is why this is put as a question; but the same MD&A tells the reader earlier that loss from operations fell, so the measure needs naming, and the 2024 report gave the driver amounts that this year's text leaves to the reader.
The fix
- Next Form 10-K: 'Cash used in operating activities increased by [amount], mainly because inventories increased by [amount] (against a [amount] decrease in 2024) to support the Product line 2 launch and ahead of tariffs, and accrued expenses decreased by [amount]; our net loss after non-cash items increased by [amount].'
Question for the company
Which measure does 'a higher operating loss' on the cash flow page refer to, given that loss from operations fell by [n] while net loss rose slightly and the net loss after non-cash items rose by [n]? How much of the [n] increase in cash used came from inventory purchases (a [n] swing in inventories) and from the timing of accruals (a [n] swing in accrued expenses)?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Cash flow summary: cash used in operating activities by year | Document | Form 10-K 2025, page 55 |
| 2 | MD&A states the change in cash used | Document | Form 10-K 2025, page 55 |
| 3 | The drivers MD&A gives, without amounts | Document | Form 10-K 2025, page 55 |
| 4 | Loss from operations was smaller in 2025 | Document | Form 10-K 2025, page 49 |
| 5 | MD&A itself tells the reader the operating loss fell | Document | Form 10-K 2025, page 51 |
| 6 | Cash flow statement: net loss, start of the reconciliation | Document | Form 10-K 2025, page 65 |
| 7 | The non-cash item that reverses direction between the years | Document | Form 10-K 2025, page 65 |
| 8 | Inventory build in 2025 | Document | Form 10-K 2025, page 65 |
| 9 | Accrued expenses fell in 2025 after rising in 2024 | Document | Form 10-K 2025, page 65 |
| 10 | Prior-year report quantified the operating cash flow drivers | Document | Form 10-K 2024 (prior year), page 57 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.