4.11 Should the self-insurance risk factor say that [wording masked] was settled in 2025?
Company B · a US-listed transportation and logistics company · SEC-style question
In brief
MD&A says the 2025 rise in insurance and claims cost includes [wording masked], and the adjusted operating income reconciliation removes [amount] of 'one-time insurance expenses', more than twice the year's pre-tax income. The self-insurance risk factor still speaks of claims expense that 'may exceed historical levels' and of past accrual adjustments in general terms, without saying that the risk materialised in 2025.
The evidence, as filed
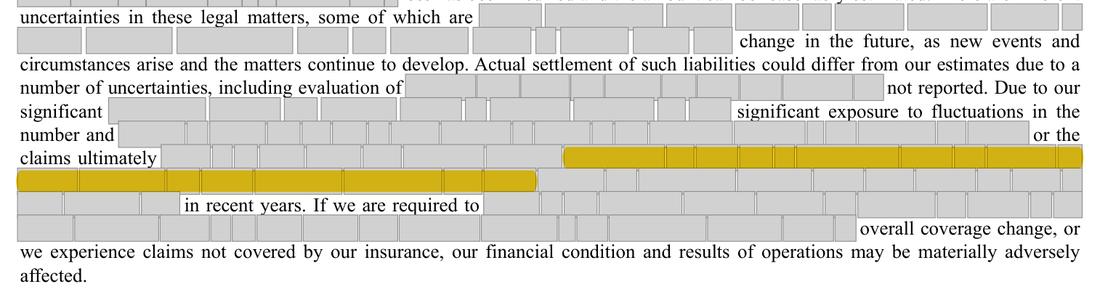
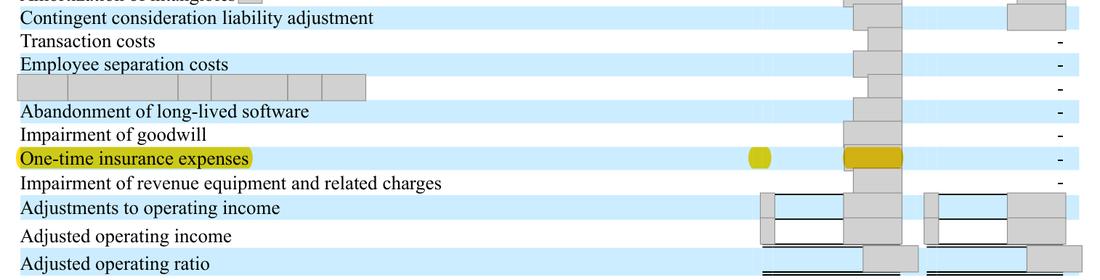
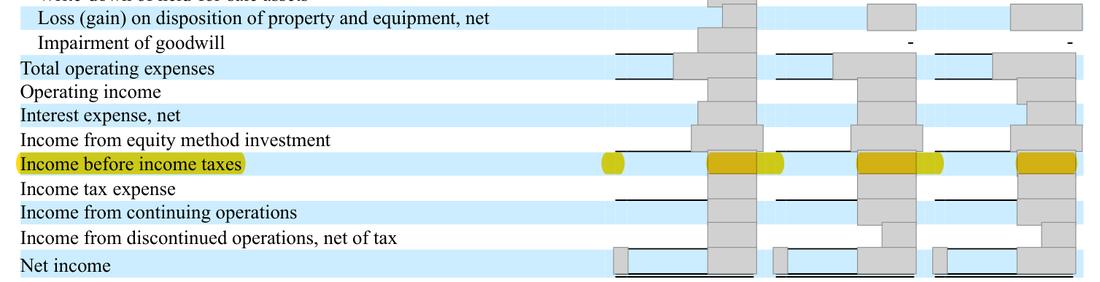
5 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Risk factor: 'Our future insurance and claims expenses may exceed historical levels'; 'Historically, we have had to significantly adjust our accruals on several occasions'. MD&A: '[wording masked] 2025'; reconciliation: 'One-time insurance expenses [n]'. Item 1A makes no reference to the 2025 settlement. | Either a sentence in the risk factor stating that in 2025 the company settled [wording masked] that increased insurance and claims expense (with a cross-reference to MD&A), or management's confirmation that the event does not change the risk as described. |
The rule
Regulation S-K Item 105(a) (17 CFR 229.105(a))
provide under the caption “Risk Factors” a discussion of the material factors that make an investment in the registrant or offering speculative or risky
Version: In force from [date] · Source: Regulation S-K, Item 105, as amended by Release 33-10825
Regulation S-K Item 105(b) (17 CFR 229.105(b))
Concisely explain how each risk affects the registrant or the securities being offered.
Version: In force from [date] · Source: Regulation S-K, Item 105, as amended by Release 33-10825
Why it applies here. a risk presented as something that 'may' happen, in a year in which it happened on a scale that the company itself treats as exceptional, is the pattern the staff most often raises under Item 105 (a risk described as hypothetical although it has occurred). The risk factor is not silent: it says accident lawsuits 'have resulted' in substantial settlements and that accruals have been adjusted in the past, so whether a specific update is needed is a judgment for management, hence a question.
Why it matters
If the staff reads the risk factor as presenting a materialised risk as hypothetical, it may issue a comment asking for revised disclosure in future filings.
Exposure
No penalty; possible staff comment and future-filings undertaking.
Our workings
the quotations above are on the pages cited.
the one-time insurance expenses of [n] are 207.2% of 2025 income before income taxes of [n] (workings).
| Measure | Amount (USD thousand) | Where |
|---|---|---|
| One-time insurance expenses removed in the adjusted operating income reconciliation | [n] | MD&A non-GAAP table |
| Income before income taxes, 2025 | [n] | Consolidated statement of operations |
| One-time insurance expenses as % of pre-tax income | [n] / [n] = 207.2% |
Management’s best defense, and our reply
Management would say the risk factor already discloses that accident lawsuits have resulted in substantial settlements and that accruals have been significantly adjusted in the past, and that the 2025 settlement is fully described in MD&A and the reconciliation. It would add that Item 105 asks for the risk, not a log of events, and that the factor is accurate as written. That position is tenable, which is why this is a question; the answer is whether a specific reference to the 2025 event, which the company itself treats as exceptional in its adjusted results, would make the factor less generic.
The fix
- Add after the first sentence of the risk factor: 'For example, in 2025 we settled [wording masked], which significantly increased our insurance and claims expense; see Insurance and claims under Item 7.'
Question for the company
Was the [wording masked] settled in 2025 (and how much of the [n] of one-time insurance expenses it accounts for) within the self-insured retention or did it reach or erode an insurance layer, and does management intend to update the self-insurance risk factor to state that this risk materialised in 2025?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Risk factor states the claims-cost risk as a possibility | Document | Form 10-K 2025, unnumbered page |
| 2 | Past adjustments mentioned only in general terms | Document | Form 10-K 2025, unnumbered page |
| 3 | The erosion risk factor refers only to the 2018-2021 policy period | Document | Form 10-K 2025, page 17 |
| 4 | MD&A: [wording masked] was settled in 2025 | Document | Form 10-K 2025, unnumbered page |
| 5 | MD&A non-GAAP reconciliation removes [n] of one-time insurance expenses | Document | Form 10-K 2025, page 39 |
| 6 | 2025 pre-tax income used for scale | Document | Form 10-K 2025, page 55 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- [wording masked]
- What is missing
- any statement that [wording masked] was settled in 2025, or of the one-time insurance expense recorded
- Pages looked at
- p.26-26 (whole of Item 1A, text), page images p.30-17
- Result
- 'large auto liability' and 'settlement of a large' appear only in MD&A (unnumbered page); 'One-time insurance' appears only in the MD&A non-GAAP reconciliation; 'large claim' has no hit. None of the hits is in Item 1A.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.