4.10 Adjusted operating income excludes [amount] of 'one-time insurance expenses' in a business where claims recur
Company B · a US-listed transportation and logistics company · SEC-style question
In brief
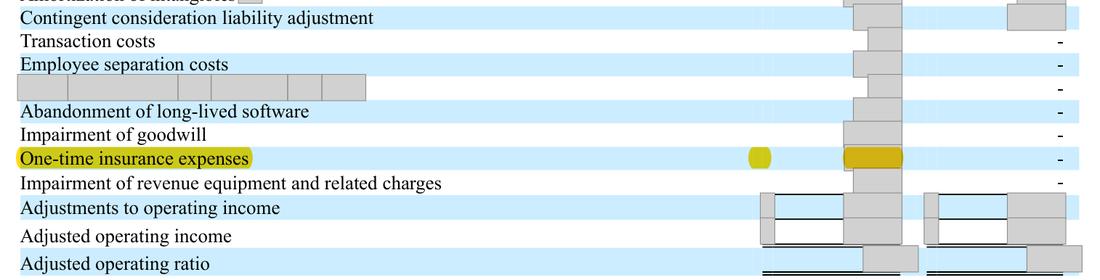
The adjusted operating ratio reconciliation adds back [amount] labelled 'One-time insurance expenses'. Insurance and claims is a standing operating cost of a trucking business: MD&A explains the 2025 rise partly by [wording masked] and says it expects insurance and claims expense to remain volatile. Item 10(e) of Regulation S-K bars calling an item non-recurring when a similar charge is reasonably likely within two years, and the staff treats expenses that occur occasionally or at irregular intervals as recurring. The 10-K does not say what the [amount] is or why it will not recur.
The evidence, as filed
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
'One-time insurance expenses [n]' added back to operating income for 2025 (none for 2024); no description of the item; the definition refers only to 'certain other costs and expenses specified in the tables above' | Either a description of the item showing it meets the two-year test for a 'one-time' label, or the label removed (and, if the adjustment is kept, a clear explanation of what was excluded and why excluding a claims cost is not misleading) |
The rule
Regulation S-K Item 10(e)(1)(ii)(B)
Adjust a non-GAAP performance measure to eliminate or smooth items identified as non-recurring, infrequent or unusual, when the nature of the charge or gain is such that it is reasonably likely to recur within two years or there was a similar charge or gain within the prior two years;
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.10(e), as amended by Release 33-8176 (2003); text in force throughout fiscal 2025
SEC Division of Corporation Finance, Non-GAAP Financial Measures interpretation, Question [n]
The staff would view an operating expense that occurs repeatedly or occasionally, including at irregular intervals, as recurring.
Version: Text in force at the date of this review · Source: SEC Division of Corporation Finance, Non-GAAP Financial Measures Compliance and Disclosure Interpretations, Question [n] ([date])
Why it applies here. a claims cost of a motor carrier is, on its face, a normal operating expense that recurs at irregular intervals; whether this particular amount is different is a matter only management can show.
Why it matters
If the add-back is an ordinary claims cost, adjusted operating income and adjusted operating ratio overstate core profitability by more than a point of operating ratio and present a recurring cost as 'one-time'.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, non-GAAP measures drew 317 of the 1,774 numbered comments (17.9%): the most frequent topic.
Exposure
A question for management; if the item proves to be an ordinary claims cost, a staff comment asking the company to remove the label or the adjustment, with a future-filings undertaking; the same measure in the earnings release falls under Regulation G. No fixed penalty.
Our workings
the reconciliation on p.39 adds back 'One-time insurance expenses' of [n] for 2025 and nothing for 2024; the 2024 10-K made no insurance adjustment for 2024 or 2023. The definition of adjusted operating ratio refers to 'certain other costs and expenses specified in the tables above', and the phrase 'one-time' appears nowhere else in the 10-K. MD&A says insurance and claims expense rose '[wording masked] 2025' and that management expects it 'to continue to be volatile over the long-term'.
the add-back equals 16.5% of the insurance and claims line and 207.2% of pre-tax income; without it, adjusted operating ratio would be [n]% rather than [n]%.
| Item | Amount (USD thousand) / ratio | Working |
|---|---|---|
| One-time insurance expenses added back | [n] | reconciliation, p.39 |
| In millions (for the text) | [n] | [n] / [n] = [n] |
| Share of insurance and claims expense | 16.5% | [n] / [n] = 16.5% |
| Against pre-tax income | 207.2% | [n] / [n] = 207.2% |
| Adjusted operating income without the add-back | [n] | [n] - [n] = [n] |
| Adjusted operating ratio without the add-back | [n]% | [n] / [n] = [n]%; 100% - [n]% = [n]% |
| Adjusted operating ratio as reported | [n]% | reconciliation, p.39 |
Management’s best defense, and our reply
Management could argue that the [amount] is a specific, outsized settlement and related premium effect well outside the company's normal claims experience, that nothing similar was adjusted in 2023 or 2024, and that excluding it gives investors a clearer view of run-rate margins, as several carriers do for exceptional verdicts. It could also note that the staff permits an adjustment even where the label is not allowed. Outside the 10-K, the fourth-quarter earnings release furnished on Form 8-K on [date] describes the item as claims costs primarily related to the settlement of [wording masked], and the Forms 10-Q for the first two quarters of 2026 make no similar adjustment. That case is tenable if the item is truly exceptional, so this is put as a question; but the 10-K gives no facts to support it, the company itself expects claims expense to remain volatile, and the staff's view is that expenses occurring occasionally or at irregular intervals are recurring.
The fix
- Describe the item ('settlement of a single auto liability claim arising from a [year] accident, in excess of our normal claims experience') and drop 'one-time' unless the two-year test is met; if the item is ordinary claims development, stop adjusting for it and recast.
Question for the company
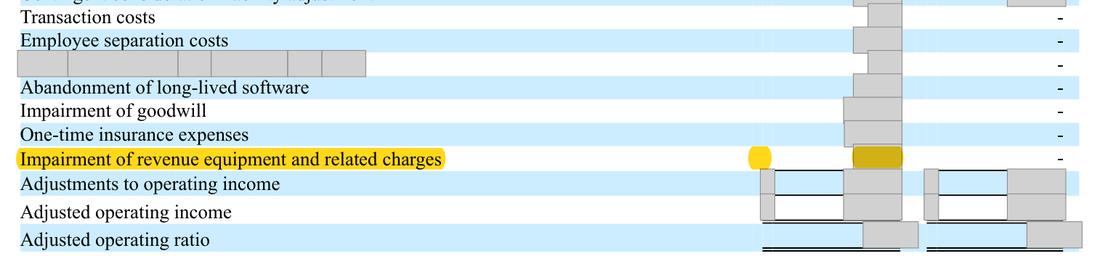
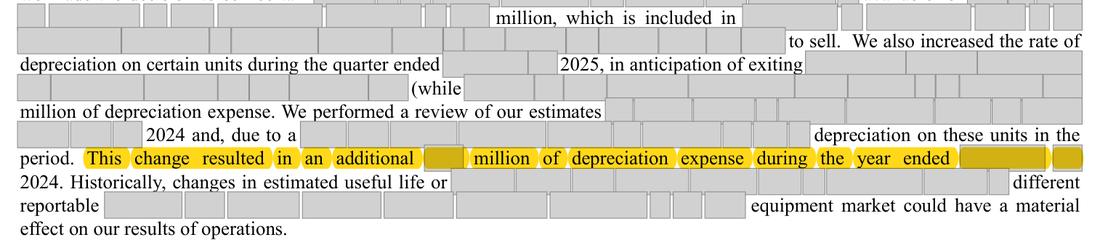
What does the [amount] of 'one-time insurance expenses' consist of (claim settlements, reserve development on prior-year claims, premium adjustments), and on what basis did management conclude that no similar charge is reasonably likely within two years, given that insurance and claims expense arises every year and the 10-K expects it to remain volatile? Separately, the [n] 'Impairment of revenue equipment and related charges' added back for 2025 appears to include the extra depreciation from a higher depreciation rate, while the [amount] of extra depreciation from a similar rate increase in 2024 was not adjusted: what does the [n] comprise, and why is the treatment consistent between the two years?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
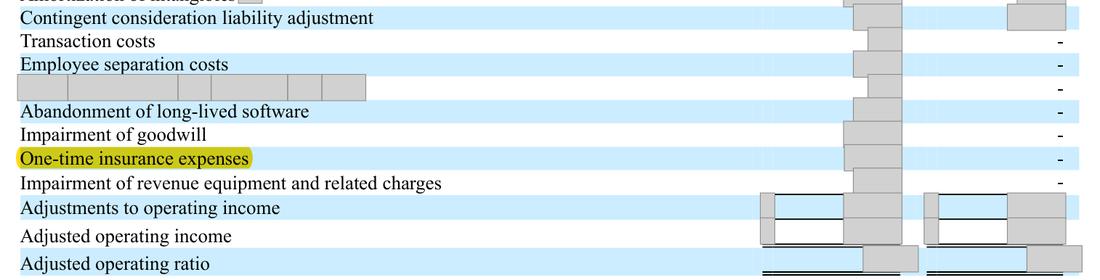
| 1 | The add-back and its label | Document | Form 10-K 2025, page 39 |
| 2 | A second [n]-only add-back for equipment charges | Document | Form 10-K 2025, page 39 |
| 3 | A similar depreciation-rate increase in 2024 was not adjusted | Document | Form 10-K 2025, page 40 |
| 4 | Adjusted operating income after the add-back | Document | Form 10-K 2025, page 39 |
| 5 | Reported adjusted operating ratio | Document | Form 10-K 2025, page 39 |
| 6 | Denominator of adjusted operating ratio | Document | Form 10-K 2025, page 39 |
| 7 | Insurance and claims, a standing operating expense line | Document | Form 10-K 2025, unnumbered page |
| 8 | MD&A cause of the 2025 rise | Document | Form 10-K 2025, unnumbered page |
| 9 | Management expects the cost to keep moving | Document | Form 10-K 2025, unnumbered page |
| 10 | Definition does not describe the insurance item | Document | Form 10-K 2025, unnumbered page |
| 11 | Prior-year reconciliation: adjustments were amortization and contingent consideration only, no insurance item | Document | Form 10-K 2024 (prior year), page 39 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- One-time insurance expenses
- What is missing
- a description of what the one-time insurance expenses consist of and why they are not expected to recur
- Pages looked at
- p.28-29, 58-33, 39-40, [n], 134-76
- Result
- 'one-time' and 'insurance expenses' hit only p.39 (the reconciliation line itself); 'non-recurring' and 'unusual' have no hits; 'large auto liability' hits unnumbered page, which names a claim settlement as one cause of higher insurance and claims expense but does not link it to the add-back or give its amount.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.