1.21 The debt note drops, without explanation, the cross-default exception for certain installment notes
Company B · a US-listed transportation and logistics company · SEC-style question
In brief
The fiscal 2024 debt note said the revenue equipment installment notes carry no events of default except certain notes totaling [amount] that are [wording masked], and the Form 10-Q for the quarter to [date] still gave [amount]. The fiscal 2025 note removes the exception and states without qualification that the notes have no events of default. The 10-K does not say whether those notes were repaid, refinanced or released.
The evidence, as filed
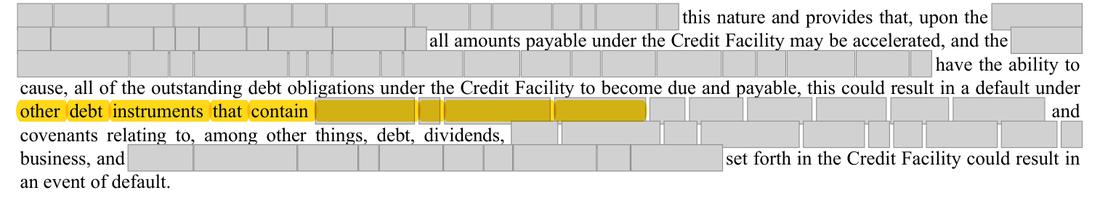
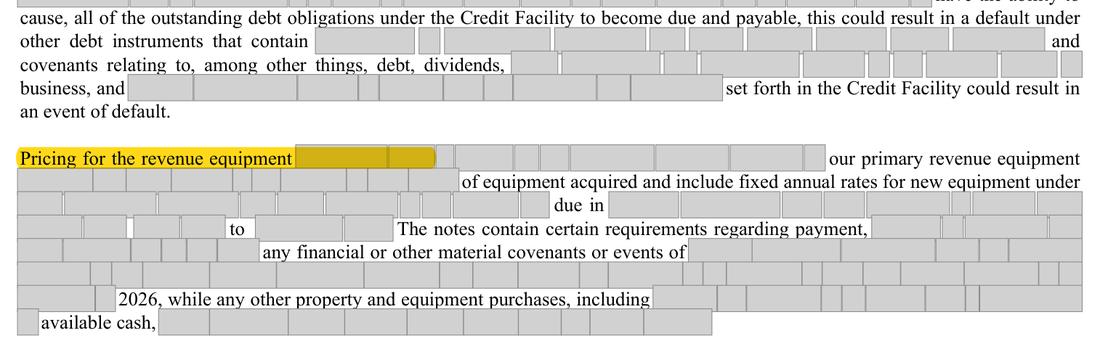
3 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 10 (page 72): the installment notes 'do not have any financial or other material covenants or events of default' - no exception and no word on the notes that were [wording masked] ([amount] at [date]). | Either the exception with its year-end amount, or a sentence that the cross-defaulted notes were repaid or released during 2025. |
| What we checked. Debt note of both [n]-Ks, the Form 10-Q debt notes for June and [date], and a whole-report search for the cross-default wording and amounts. | |
The rule
Exchange Act Rule 12b-20
there shall be added such further material information, if any, as may be necessary to make the required statements, in the light of the circumstances under which they are made not misleading
Version: Text in force at the date of this review · Source: 17 CFR 240.12b-20
Why it applies here. either the cross-defaulted notes were settled or released in the fourth quarter of 2025 (and the change is correct but unexplained), or some remain and the unqualified sentence overstates the independence of the installment notes from the Credit Facility. The filing does not let a reader tell which.
Why it matters
If cross-defaulted notes remained at year end, the note tells readers that a Credit Facility default would not reach the installment notes when part of them would accelerate with it; liquidity readers would underrate the linkage.
Exposure
No exposure unless cross-defaulted notes remained at [date]; the realistic outcome is then a corrected sentence in the next filing.
Our workings
the fiscal 2024 note qualified the no-default statement with an exception for notes totaling [amount] that are [wording masked]; the [date] Form 10-Q kept the exception at [amount]; the fiscal 2025 note drops it. The Credit Facility paragraph on the same page still says a Credit Facility default could cause a default under other debt instruments that contain acceleration or cross-default provisions.
none - no figure is restated.
| Date | Cross-defaulted installment notes | Where stated |
|---|---|---|
| [date] | [amount] | Fiscal 2024 10-K, debt note |
| [date] | [amount] | Form 10-Q for the third quarter of 2025, debt note |
| [date] | not stated; exception removed | Fiscal 2025 10-K, debt note |
Management’s best defense, and our reply
The cross-defaulted notes may have been repaid, refinanced or released in the fourth quarter of 2025, in which case the sentence is simply up to date, and the Credit Facility paragraph on the same page still warns that a default could trigger other instruments with cross-default provisions. No default existed at [date], so the rule on defaults asks for nothing. However, a quantified exception that stood at [amount] three months earlier disappears without a word, and a reader cannot tell whether the new unqualified sentence is accurate; only management can answer that, which is why this is a question and not a finding.
The fix
- State the position at year end: either 'except certain notes totaling $X million are [wording masked]' or 'the notes previously [wording masked] were repaid (or released) during 2025'.
Question for the company
Were the revenue equipment installment notes that were [wording masked] ([amount] at [date]) repaid, refinanced or released from the cross-default before [date]? If any remained, should the debt note have kept the exception with its year-end amount?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Fiscal 2025 note: the no-default statement now carries no exception | Document | Form 10-K 2025, page 72 |
| 2 | The Credit Facility paragraph still refers to instruments with cross-default provisions | Document | Form 10-K 2025, page 72 |
| 3 | Fiscal 2024 note: the exception for [amount] of cross-defaulted notes | Document | Form 10-K 2024 (prior year), page 72 |
| 4 | Third-quarter 2025 Form 10-Q: [amount] still cross-defaulted at [date] | Document |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Pricing for the revenue equipment installment notes
- What is missing
- Any statement of what happened to the installment notes that were [wording masked] (repaid, refinanced, released or still outstanding)
- Pages looked at
- p.28-42 (MD&A, liquidity), 125-128 (debt and lease notes)
- Result
- 'cross-defaulted' and '[n]' have no hits. 'cross-default' hits p.41-22 (risk factors on cross-defaults in general), p.72 (the Credit Facility paragraph on other instruments with cross-default provisions) and p.73 (leases with cross-default provisions); none says whether installment notes remain cross-defaulted. '[n]' hits only p.75, the 2023 equity income from the leasing investee.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.