6.01 The Exhibit 32 certification filed with the fiscal 2025 Form 10-K certifies the Form 10-K 'for the year ended [date]'
Company A · a US-listed consumer leisure company · Compliance or disclosure gap
In brief
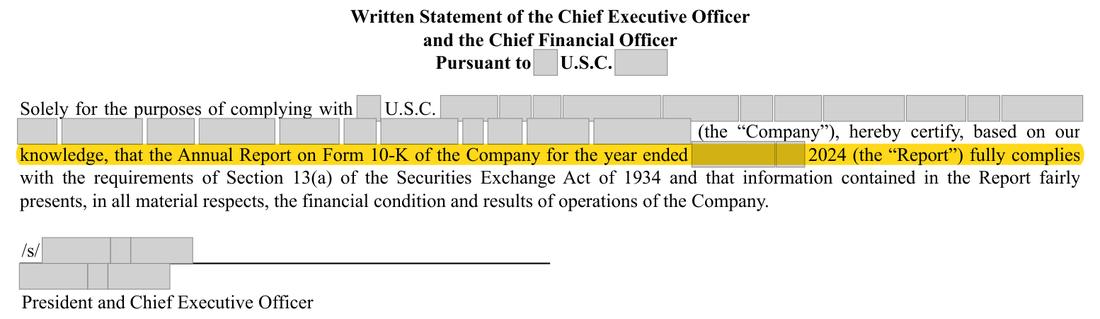
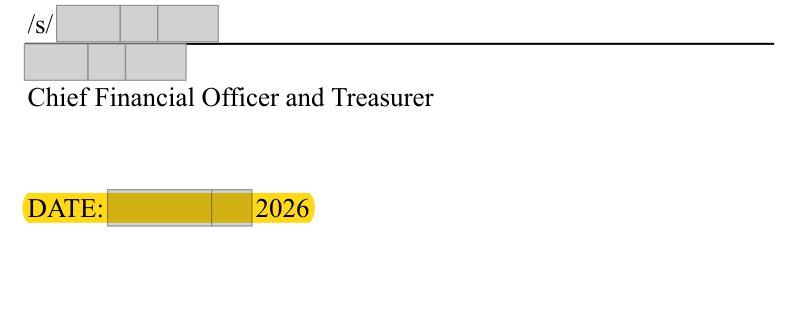
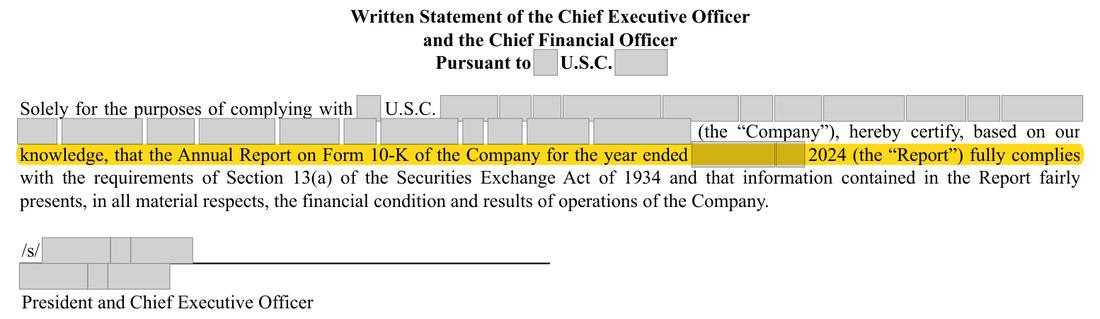
Section 906 of the Sarbanes-Oxley Act (18 U.S.C. 1350) requires each periodic report to be accompanied by a statement of the chief executive officer and chief financial officer certifying that report. The Exhibit 32 filed with this Form 10-K, dated [date], certifies 'the Annual Report on Form 10-K of the Company for the year ended [date]'. Apart from its date, it is word for word the exhibit filed with the prior-year Form 10-K, so the fiscal 2025 report carries no certification of itself.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Exhibit 32 dated [date] certifies 'the Annual Report on Form 10-K of the Company for the year ended [date]'. | Exhibit 32 certifying 'the Annual Report on Form 10-K of the Company for the year ended [date]', signed by both officers, filed by a Form 10-K/A that carries the corrected certification. |
| What we checked. The 10-K filing index and exhibit index; the Exhibit 31 and [n] certifications as filed with this Form 10-K; Exhibit 32 to the fiscal 2024 Form 10-K; the cover and statements for the fiscal year end; EDGAR for any Form 10-K/A. | |
The rule
18 U.S.C. 1350(b) (Sarbanes-Oxley Act section 906)
The statement required under subsection (a) shall certify that the periodic report containing the financial statements fully complies with the requirements of section [n](a) or [n](d)
Version: Text in force at the date of this review · Source: United States Code, Title 18, section [n], as enacted by the Sarbanes-Oxley Act of 2002 section 906
Regulation S-K Item 601(b)(32)(i)
The certifications required by Rule 13a-14(b) (17 CFR 240.13a-14(b)) or Rule 15d-14(b) (17 CFR 240.15d-14(b)) and Section 1350 of Chapter 63 of Title 18 of the United States Code
Version: Text in force at the date of this review · Source: 17 CFR 229.601 (eCFR, as amended; in force for fiscal 2025)
Why it applies here. The prior-year exhibit was carried forward with only the date changed. Section 1350(b) requires the statement to certify 'the periodic report containing the financial statements', meaning the report it accompanies. A statement naming a different, earlier report does not do that, so the section [n] certification for the fiscal 2025 Form 10-K was not given. Staff practice treats a defective certification as needing an amendment that files a corrected certification.
Why it matters
The fiscal 2025 Form 10-K is not accompanied by the section [n] certification of that report; a defective certification is a deficiency the staff ordinarily asks the company to cure by amendment.
Exposure
Realistic consequence: a staff comment requiring a Form 10-K/A that files a corrected Exhibit 32 (with the full report or the required parts). Criminal penalties under section [n](c) attach only to knowing or wilful false certification and are not suggested here.
Our workings
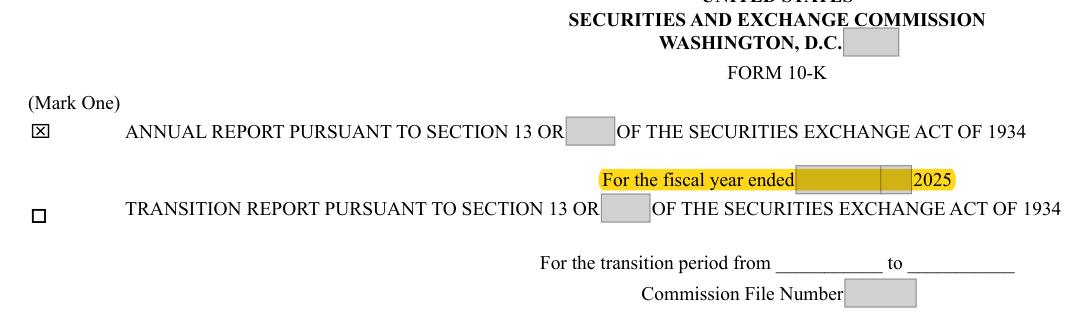
The exhibit index lists Exhibit 32 as the written statement of the Chief Executive Officer and Chief Financial Officer under 18 U.S.C. 1350. The exhibit filed on [date] is dated [date] but certifies the Form 10-K 'for the year ended [date]'. This Form 10-K covers the fiscal year ended [date]. The Exhibit 32 filed with the fiscal 2024 Form 10-K, dated [date], has identical wording, including the same year-end. The section 302 certifications correctly refer to 'this Annual Report on Form 10-K'. EDGAR shows no Form 10-K/A for fiscal 2025.
None needed: the comparison is of wording and dates (workings).
| Item | Fiscal 2025 Form 10-K (filed [date]) | Fiscal 2024 Form 10-K (filed [date]) |
|---|---|---|
| Period on the cover | fiscal year ended [date] | fiscal year ended [date] |
| Period named in Exhibit 32 | year ended [date] | year ended [date] |
| Date of Exhibit 32 | [date] | [date] |
| Result | certifies the prior-year report | correct |
Management’s best defense, and our reply
The company can argue that the slip is clerical: the exhibit is dated [date], is attached to the fiscal 2025 report, and both officers plainly intended to certify that report, as their section 302 certifications do. It may add that the staff reviewed this Form 10-K in [date] and did not raise the exhibit. The answer: section [n](b) requires the statement to certify the periodic report it accompanies, and a statement that expressly names a different report does not do so on its face; the Exhibit 31 certifications are made under section 302, not section 906; and the staff's comment concerned only the debt-conversion accounting, while its closing letter leaves responsibility for the filing with the company.
The fix
- File a Form 10-K/A with a new Exhibit 32 reading: 'the Annual Report on Form 10-K of the Company for the year ended [date] (the "Report") fully complies ...', dated and signed by both officers; add a check to the filing checklist that the period in Exhibits 31 and [n] matches the cover page.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Exhibit 32 filed with the fiscal 2025 Form 10-K names the fiscal 2024 report | Document | |
| 2 | The exhibit is dated for this filing | Document | |
| 3 | The prior-year Exhibit 32 has the same wording | Document | |
| 4 | Prior-year exhibit date: only the date was changed | Document | |
| 5 | The report under review covers the fiscal year ended [date] | Document | Form 10-K 2025, unnumbered page |
| 6 | The exhibit index lists Exhibit 32 as the section [n] statement | Document | Form 10-K 2025, page 92 |
| 7 | The section 302 certifications refer correctly to this report | Document |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.