5.01 A named executive officer's retirement notice of [date] was reported on Form 8-K only in [date], yet the cover page says all reports were filed
Company A · a US-listed consumer leisure company · Compliance or disclosure gap
In brief
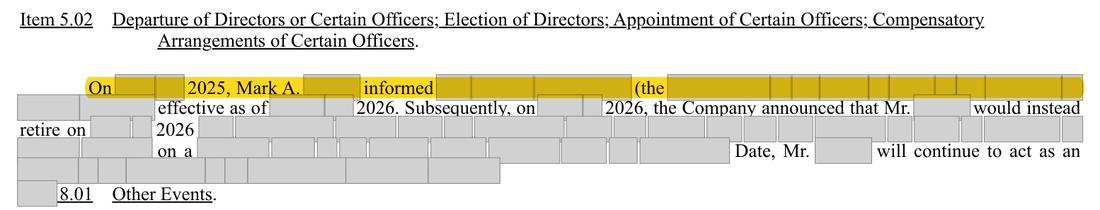
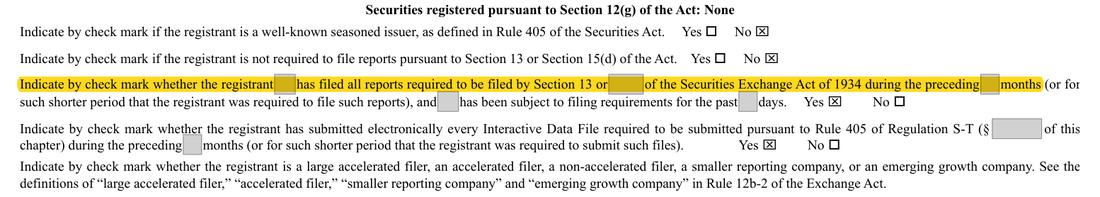
On [date] the President of the Company venues, a named executive officer in the 2025 proxy statement, gave notice of his decision to retire. Item 5.02(b) of Form 8-K called for a current report within four business days, by [date]; the company filed it on [date], 307 days late. This Form 10-K, filed on [date] while that report was still outstanding, answers 'Yes' to having filed every report required in the preceding 12 months.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Cover page: 'Yes' to having filed all Section 13 reports in the preceding 12 months. The Item 5.02(b) report of the [date] retirement notice was filed on [date], 307 days after it fell due. | An Item 5.02(b) Form 8-K filed by [date]. With that report outstanding at [date], a cover-page answer that reflects it, and a fresh check of Form S-3 eligibility before the shelf is used. |
| What we checked. EDGAR filing index for every Form 8-K from [date] to today; the late Form 8-K and its two press-release exhibits; the Summary Compensation Table of the 2025 proxy statement; Part II Item 5 of the June- and September-quarter Forms 10-Q; the 10-K cover page, the executive-officer biographies and Item 9B; Form S-3 General Instruction I.A.3. | |
The rule
Form 8-K Item 5.02(b)
If the registrant’s principal executive officer, president, principal financial officer, principal accounting officer, principal operating officer, or any person performing similar functions, or any named executive officer, retires, resigns or is terminated from that position
Version: Text in force at the date of this review · Source: Form 8-K (SEC [n]), General Instructions and Items, as amended
Form 8-K Instruction 4 to Item 5.02
For purposes of this Item, the term “named executive officer” shall refer to those executive officers for whom disclosure was required in the registrant’s most recent filing with the Commission
Version: Text in force at the date of this review · Source: Form 8-K (SEC [n]), Instructions to Item 5.02, as amended
Form 8-K General Instruction B.1
Unless otherwise specified, a report is to be filed or furnished within four business days after occurrence of the event.
Version: Text in force at the date of this review · Source: Form 8-K (SEC [n]), General Instruction B.1, as amended
SEC Corporation Finance interpretation, Exchange Act Form 8-K, Question [n]
the Item 5.02(b) Form 8-K filing obligation is triggered by the old principal accounting officer's notice of a decision to retire or resign or by the notice of termination, whether or not such notice is written
Version: Text in force at the date of this review · Source: SEC Division of Corporation Finance, Compliance and Disclosure Interpretations: Exchange Act Form 8-K ([date], as updated)
Form 10-K cover page
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months
Version: Text in force at the date of this review · Source: Form 10-K (SEC [n]), cover page, as revised
Form S-3 General Instruction I.A.3(b)
has filed in a timely manner all reports required to be filed during the twelve calendar months and any portion of a month immediately preceding the filing of the registration statement, other than a report that is required solely pursuant to Item 1.01, 1.02, 1.04, 1.05, [n], 4.02(a) or [n](e) of Form 8-K
Version: Text in force at the date of this review · Source: Form S-3 (SEC [n]), General Instructions, as amended (official copy, sec.official text)
Why it applies here. Item 5.02(b) reaches 'any named executive officer', and Instruction 4 fixes that group by the most recent filing with Item 402(c) disclosure, which is the 2025 proxy statement. The staff's interpretation is that the obligation runs from the officer's notice of a decision to retire, not from the effective date. The company's own report adopts [date] as the event date. The report was therefore due by [date], and at [date] a required Section 13 report had not been filed, so the cover-page 'Yes' was not accurate. Item 5.02(b) is not among the Form 8-K items excepted from the timeliness condition for Form S-3, so the late report also bears on the use of the company's shelf registration statement (file [file no.]).
Why it matters
The cover page carries an inaccurate statement, and a required current report reached investors through EDGAR ten months after the event. The late report is not one of the Form 8-K items excepted from the Form S-3 timeliness condition, so the company could not meet that condition for twelve calendar months after the [date] due date, which covers the [date] annual update of its shelf registration statement.
Exposure
No fixed penalty. Realistic consequences: a staff comment asking for a corrected cover answer or an undertaking for future filings; and loss of Form S-3 eligibility at the [date] annual update, so any shelf takedown would need counsel's analysis and possibly a new or amended registration statement; the timeliness condition can be met again only once the [date] due date falls outside the twelve-calendar-month look-back (from [date]).
Our workings
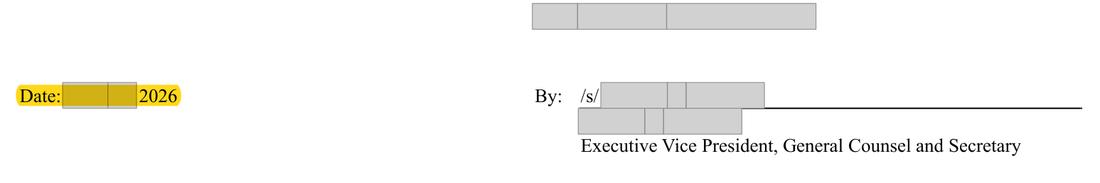
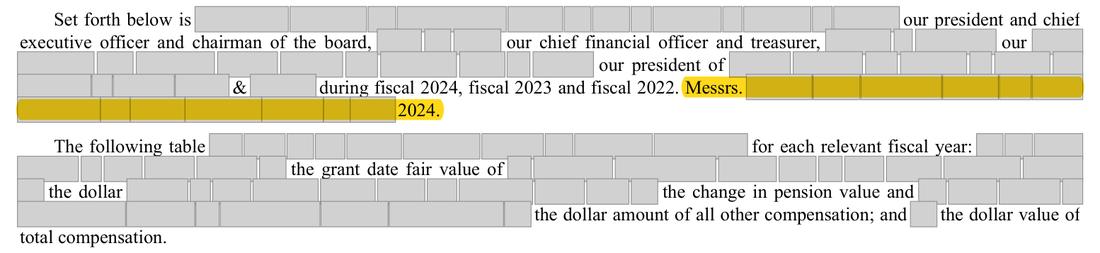
The Form 8-K filed on [date] gives [date] as the date of the earliest event reported and states that on that day the President of the Company venues informed the company of his intent to retire, effective [date]. The 2025 proxy statement (filed [date]) lists him in the Summary Compensation Table among the named executive officers for fiscal 2024. The company announced the retirement by press release on [date], but that release was not filed on Form 8-K until it became an exhibit to the [date] report. Part II Item 5 of the June-quarter Form 10-Q carries only the trading-arrangement statement. The Form 10-K, filed on [date], ticks 'Yes' to having filed all reports required by Section 13 in the preceding 12 months, and its executive-officer biography says the retirement was announced in [date].
Four business days from Monday [date] end on Friday [date]. The report was filed 307 days after that date; the 10-K was filed 245 days after it, so the missed due date sits inside the 10-K's 12-month look-back (workings).
| Step | Date | Computation |
|---|---|---|
| Notice of decision to retire received | [date] (Monday) | date of earliest event reported on the Form 8-K |
| Form 8-K due (four business days) | [date] (Friday) | [n] and [date] = 4 business days |
| Press release announcing the retirement | [date] | [date] - [date] = 129 days after the notice |
| This Form 10-K filed, cover answer 'Yes' | [date] | [date] - [date] = 245 days after the due date (inside the 12-month look-back) |
| Item 5.02 Form 8-K filed | [date] | [date] - [date] = 307 days late |
Management’s best defense, and our reply
The company can argue that the officer heads a division rather than the registrant, that the [date] conversation was an early statement of intent nine months ahead of the retirement date rather than a notice of a decision, and that investors received the news through the [date] press release and the 10-K biography, so nothing was concealed. It may add that the staff reviewed this Form 10-K in [date] and closed its review without raising the point. However, Instruction 4 makes every officer in the most recent Summary Compensation Table a named executive officer, and the 2025 proxy names him; the company's own Form 8-K adopts [date] as the date of the event it reports under Item 5.02, which is its own reading that a notice was given that day; a press release is not a filed report, and Item 5.02(b) is not in the Form S-3 exception list; and the staff's letter dealt only with the debt-conversion accounting, while its closing letter reminds the company that it remains responsible for its disclosures.
The fix
- Record in the disclosure-controls procedures that any notice by a director or named executive officer of a decision to retire or resign goes to the General Counsel on the day received, with the Item 5.02(b) Form 8-K filed within four business days; before any shelf takedown before [date], confirm Form S-3 eligibility with counsel; in future cover pages answer the reports-filed question against the full EDGAR record.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The late Form 8-K: the notice of the decision to retire was given on [date] and reported under Item 5.02 | Document | |
| 2 | The Item 5.02 report was signed and filed on [date] | Document | |
| 3 | The 2025 proxy statement, the most recent filing with Summary Compensation Table disclosure before [date], names him a named executive officer | Document | |
| 4 | The retirement was announced by press release on [date], which reached EDGAR only as an exhibit to the [date] report | Document | |
| 5 | Part II Item 5 of the June-quarter Form 10-Q carries only the trading-arrangement statement | Document | |
| 6 | The cover-page statement on reports filed in the preceding 12 months | Document | Form 10-K 2025, unnumbered page |
| 7 | The box is ticked 'Yes' | Document | Form 10-K 2025, unnumbered page |
| 8 | The 10-K's executive-officer biography records the retirement announced in [date] | Document | Form 10-K 2025, page 22 |
| 9 | The company's Form S-3 shelf registration statement filed in [date] | Document |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.