4.03 Item 7A gives market risk information only at the latest year end: no preceding-year comparison and no reason for the move into variable-rate debt
Company A · a US-listed consumer leisure company · Compliance or disclosure gap
In brief
Item 7A (quantitative and qualitative disclosures about market risk) points to an MD&A (management's discussion and analysis) section that gives the interest-rate position only at [date]: variable-rate debt of [amount] ([n]% of debt), fixed-rate debt of [amount] and a maturity table at that date. Regulation S-K Item 305(a)(3) also requires summarized information for the preceding year and the reasons for material changes. Neither is given, although the company moved from no variable-rate debt a year earlier to [amount]. The prior-year 10-K had the same gap.
The evidence, as filed
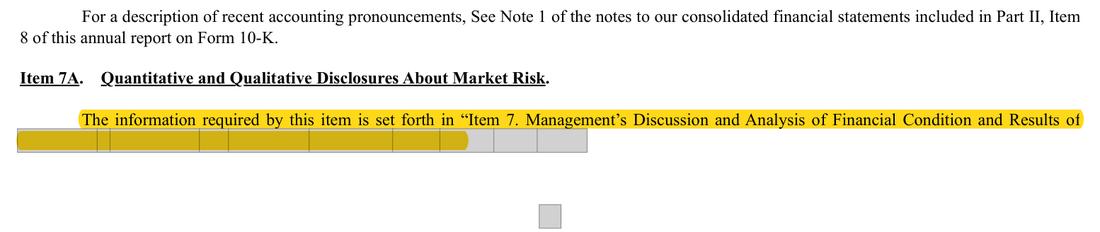
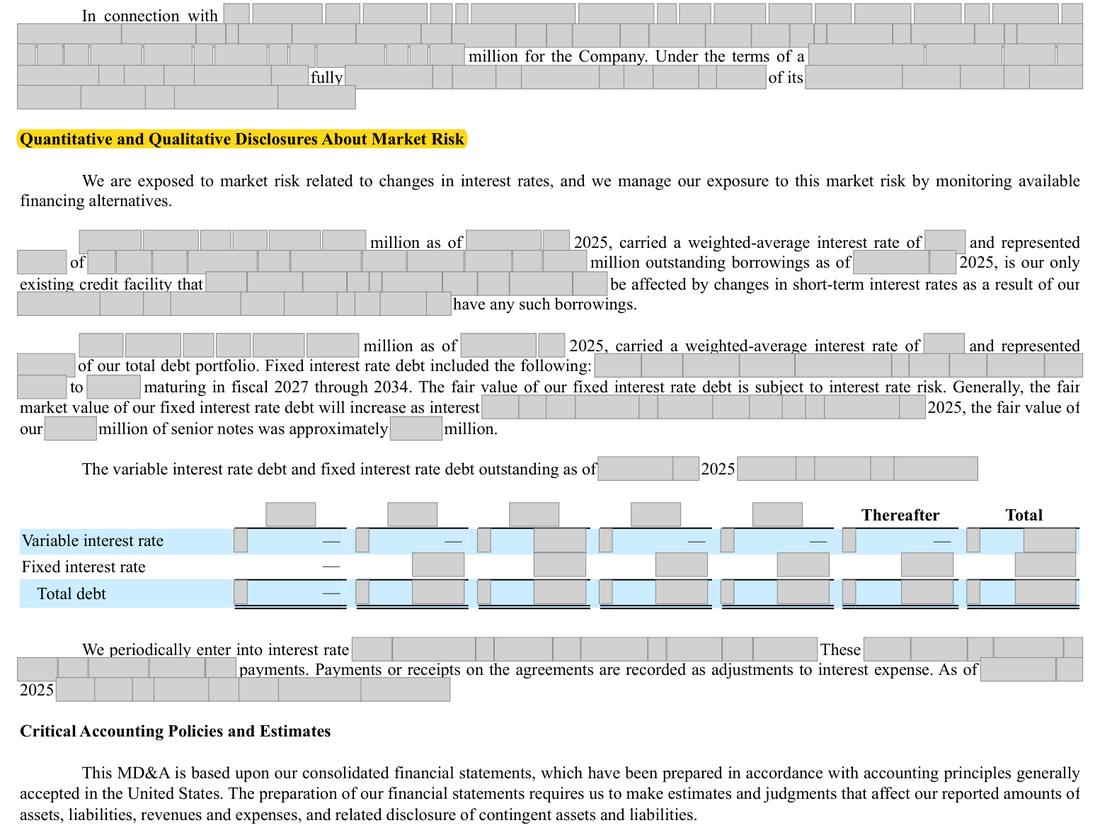
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Market risk information at [date] only (variable-rate debt [amount], fixed-rate debt [amount], senior notes fair value approximately [amount]); no figures at [date] and no discussion of the change. The prior-year 10-K likewise gave only its own year end. | A summarized comparison with the preceding year end (variable-rate debt nil and fixed-rate debt [amount] at [date]; senior notes fair value [amount] against [amount]) and the reason for the change: the revolving facility drawn to [amount] at the year end. |
| What we checked. The Item 7A cross-reference, the whole market-risk section of the MD&A, the liquidity and debt discussion, the debt and fair-value notes, and the prior-year 10-K's market-risk section. | |
The rule
Regulation S-K Item 305(a)(3)
Registrants shall present summarized market risk information for the preceding fiscal year. In addition, registrants shall discuss the reasons for material quantitative changes in market risk exposures between the current and preceding fiscal years.
Version: Text in force at the date of this review · Source: 17 CFR 229.305, Regulation S-K Item 305, as amended
Regulation S-K Item 305(e)
A smaller reporting company, as defined by § [n](f)(1), is not required to provide the information required by this Item.
Version: Text in force at the date of this review · Source: 17 CFR 229.305, Regulation S-K Item 305, as amended
Why it applies here. paragraph (a)(1) of the market-risk Item sets the latest-year disclosure and paragraph (a)(3) adds a second, separate requirement to present summarized market risk information for the preceding fiscal year and to discuss the reasons for material quantitative changes. Neither exemption in paragraph (a)(3) applies: the company gives current-year disclosure and has presented Item 305 information for many years, and it is not a smaller reporting company, so paragraph (e) does not relieve it. The omission recurs in both [n]-Ks. The size of the exposure is modest: a one percentage point rise in rates on [amount] of variable-rate debt changes annual interest by about [n] (USD thousand; workings), so the point is low in severity, but the paragraph is mandatory.
Why it matters
Readers cannot see from Item 7A that the company moved from an all-fixed debt book into variable-rate borrowing during the year, or how the fair-value position of the notes changed; Item 305 comparatives are a routine subject of staff comment.
Exposure
A staff comment letter asking for the comparison in future filings; an amended filing is unlikely at this exposure size.
Our workings
Item 7A states that the information is set forth in the MD&A market-risk section. That section gives variable-rate debt of [amount] at a weighted-average rate of [n]%, [n]% of total debt, fixed-rate debt of [amount] at [n]%, the senior notes' fair value of approximately [amount], and a maturity table, all as of [date]. Nothing in it gives the [date] position. The prior-year 10-K's section reported zero variable-rate debt and fixed-rate debt of [amount] at [date], with no figures for the year before.
variable-rate debt moved from nil to [amount] ([n] - [n] = [n]), and the senior notes moved from a fair value below carrying amount ([n] - [n] = -[n]) to one above it ([n] - [n] = [n]); see workings.
| Item | [date] | [date] | Change |
|---|---|---|---|
| Variable-rate debt (USD million) | [n] | [n] | [n] - [n] = [n] |
| Fixed-rate debt (USD million) | [n] | [n] | [n] - [n] = -[n] |
| Variable-rate share of debt | [n]% | 0.0% | [n] / [n] = [n]% |
| Senior notes: fair value less carrying amount (USD million) | [n] - [n] = [n] | [n] - [n] = -[n] | [n] - (-[n]) = [n] |
| Illustrative effect of a 1 percentage point rate rise on variable-rate debt (USD thousand) | [n] x 1% = [n] | 0 | [n] / [n] = 1.15% of pre-tax income |
Management’s best defense, and our reply
Management would say the prior-year figures are on public record in the previous 10-K and that the debt note and the balance sheet in this 10-K show the [date] debt balances, so a reader loses nothing. It would add that [amount] of variable-rate debt is immaterial, so no material quantitative change needed discussing. However, [n](a)(3) asks for the summarized prior-year market risk information in the Item itself, whatever the size of the change, and the debt note shows the prior-year balances (revolving credit nil, senior notes [n]) but no prior-year fair value of the senior notes and no discussion of the change, and the market-risk Item asks for its information outside the financial statements; the size argument goes to severity, which is why the point is rated low.
The fix
- Add to the market-risk section: 'As of [date], we had no variable interest rate debt; fixed interest rate debt totaled [amount], and the fair value of our [amount] of senior notes was approximately [amount]. Variable-rate exposure increased in fiscal 2025 because of borrowings of [amount] under the revolving credit facility at year end.' Add the prior-year maturity table or a summarized total.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Item 7A relies wholly on the MD&A market-risk section | Document | Form 10-K 2025, page 49 |
| 2 | Variable-rate debt at the latest year end only | Document | Form 10-K 2025, page 47 |
| 3 | Variable-rate share of debt at the latest year end | Document | Form 10-K 2025, page 47 |
| 4 | Fixed-rate debt at the latest year end only | Document | Form 10-K 2025, page 47 |
| 5 | Fair value of the senior notes at the latest year end only | Document | Form 10-K 2025, page 47 |
| 6 | Prior-year 10-K: no variable-rate debt a year earlier | Document | Form 10-K 2024 (prior year), page 46 |
| 7 | Prior-year 10-K: fixed-rate debt a year earlier, given for its own year end only | Document | Form 10-K 2024 (prior year), page 46 |
| 8 | Prior-year 10-K: senior notes fair value a year earlier | Document | Form 10-K 2024 (prior year), page 46 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Quantitative and Qualitative Disclosures About Market Risk
- What is missing
- Summarized market risk information at [date] and the reasons for the change in exposure (Item 305(a)(3))
- Pages looked at
- p.44-49 (MD&A liquidity, market risk, Item 7A), p.60 and 68-69 (fair value and debt notes)
- Result
- 'preceding fiscal year' and '[date], the fair value' have no hits. 'variable interest rate' hits p.46-47: the contractual-obligations footnote and the market-risk section, both at [date] only. 'fair value of our' hits p.47 (the 2025 senior notes fair value) and p.48 (goodwill reporting unit), not market-risk comparatives. 'market risk' hits p.94 (contents), p.47 (the section heading and opening sentence) and p.49 (the Item 7A cross-reference).
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.