1.05 Other accrued liabilities of [amount] (35.4% of current liabilities) are referred to Note 1, which contains no analysis of the caption
Company A · a US-listed consumer leisure company · SEC-style question
In brief
The balance sheet shows other accrued liabilities of [amount] and points to Note 1, but Note 1 contains no breakdown. Other notes say that part of deferred revenue and [amount] of pension liability sit in the caption, leaving about [amount] undescribed even if all deferred revenue is there. Regulation S-X asks for any item above 5% of current liabilities (about [amount]) to be shown separately; the note does not show whether such an item exists, for example self-insurance reserves.
The evidence, as filed
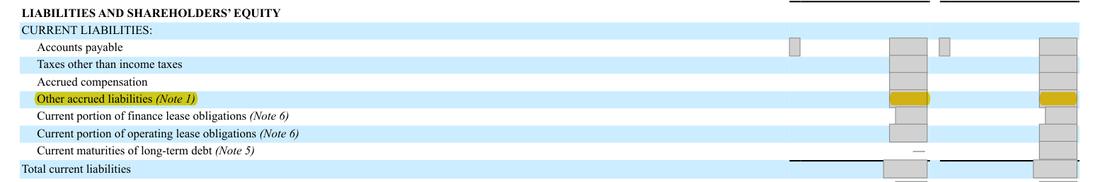
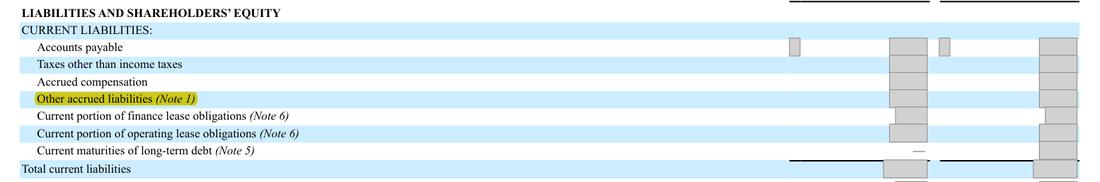
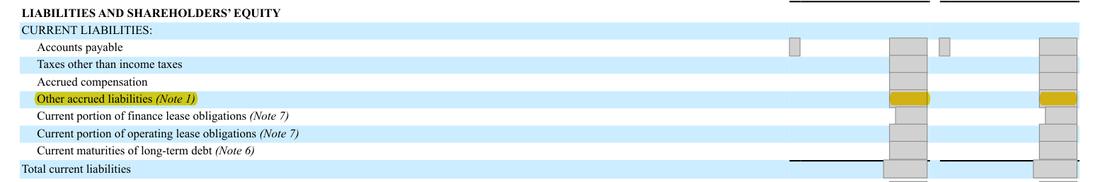
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
One caption of [n] ([n] in 2024) with a reference to a note that has no analysis; components identifiable elsewhere: deferred revenue ([n] in total, location partly stated) and the current pension liability ([n]). | An analysis of the caption, in the balance sheet or a note, showing separately each item above 5% of total current liabilities (for example deferred revenue, self-insurance reserves, accrued interest), with the remainder in one amount. |
| What we checked. Balance sheet, Note 1 (all policies), Note 2 deferred revenue, Note 8 pension, the cash-flow statement, and the prior-year Form 10-K. | |
The rule
Regulation S-X Rule 5-02, caption [n] (other current liabilities)
State separately, in the balance sheet or in a note thereto, any item in excess of 5 percent of total current liabilities.
Version: Text in force at the date of this review · Source: 17 CFR 210.5-02, Regulation S-X (eCFR text in force for fiscal 2024 and 2025)
Why it applies here. Regulation S-X Rule 5-02, caption [n], requires any item in excess of 5% of total current liabilities to be stated separately in the balance sheet or a note. Deferred revenue arguably meets that through Note 2, but the residual is about twice the threshold and is not described, so a reader cannot confirm that it holds no single item above [n].
Why it matters
The largest current-liability caption after accounts payable is not analyzed, and a self-insurance or similar accrual above the threshold, if there is one, is not visible.
Exposure
None until the composition is known; if an item exceeds the threshold, a staff comment answered by future-filing disaggregation.
Our workings
the balance sheet reports 'Other accrued liabilities (Note 1)' of [amount] against total current liabilities of [amount]. Note 1 has no table or sentence analyzing the caption. Note 2 gives total deferred revenue of [amount] and says the advance-ticket and lodging properties gift-card parts are included in other accrued liabilities, but for the venues gift cards ([amount]) it says only that they are 'part of deferred revenues', while also expecting redemption over two years. Note 8 places [amount] of pension liability in the caption. Note 1 describes self-insurance for workers' compensation, health and general liability without any amount.
5% of current liabilities is [n] ([n] x 5%); the caption is 35.4% of current liabilities ([n] / [n]); after deducting all deferred revenue and the pension amount, [n] remains ([n] - [n] - [n]).
| Measure | Working | Result |
|---|---|---|
| 5% of total current liabilities | [n] x 5% = [n] | [n] |
| Caption as a share of current liabilities | [n] / [n] = 35.4% | 35.4% |
| Residual after deferred revenue and pension | [n] - [n] - [n] = [n] | [n] |
Management’s best defense, and our reply
Management can argue that the largest component, deferred revenue, is already quantified in Note 2 and the pension component in Note 8, which together meet the rule for those items. It can add that the remainder is made up of many accruals each below 5% of current liabilities, which the rule allows to be shown in one amount. That is a tenable reading, so the point is a question. The answer still needed: the balance sheet refers readers to Note 1 for an analysis that is not there, the location of the venues gift cards is not stated, and the residual of about [n] is roughly twice the threshold.
The fix
- Add to Note 1 (as the balance sheet already promises) a table: deferred revenue [x], self-insurance reserves [y], accrued interest [z], current pension liability [n], other [w], total [n].
Question for the company
What are the components of other accrued liabilities of [amount] at [date] (and [amount] at [date]), where are the venues gift-card liabilities presented, and does any component other than deferred revenue exceed 5% of total current liabilities (about [amount])?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The caption and its reference to Note 1 | Document | Form 10-K 2025, page 54 |
| 2 | Base of the 5% threshold | Document | Form 10-K 2025, page 54 |
| 3 | Total deferred revenue, the largest identifiable component | Document | Form 10-K 2025, page 66 |
| 4 | Venues gift cards: no balance-sheet caption stated | Document | Form 10-K 2025, page 66 |
| 5 | Pension component of the caption | Document | Form 10-K 2025, page 76 |
| 6 | Self-insurance liabilities exist; no amount or caption given | Document | Form 10-K 2025, page 62 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Other accrued liabilities (Note 1)
- What is missing
- an analysis of the caption showing each item above 5% of total current liabilities
- Pages looked at
- p.54 (balance sheet), p.59-64 (Note 1), p.66 (Note 2), p.76 (Note 8) - images
- Result
- 'other accrued liabilities' hits p.45 (MD&A cash-flow narrative), p.54 (the caption), p.58 (cash-flow movement), p.66 (parts of deferred revenue said to be included) and p.76 (pension component); none analyses the caption. 'insurance reserve' and 'self insurance' hit p.62, the policy with no amount. 'accrued interest' hits p.80, accrued interest and penalties on income taxes (nil). 'accrued liabilities consist' has no hit.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.