1.06 Restricted stock table: the fiscal 2025 closing weighted-average fair value does not follow from the roll-forward
Company A · a US-listed consumer leisure company · SEC-style question
In brief
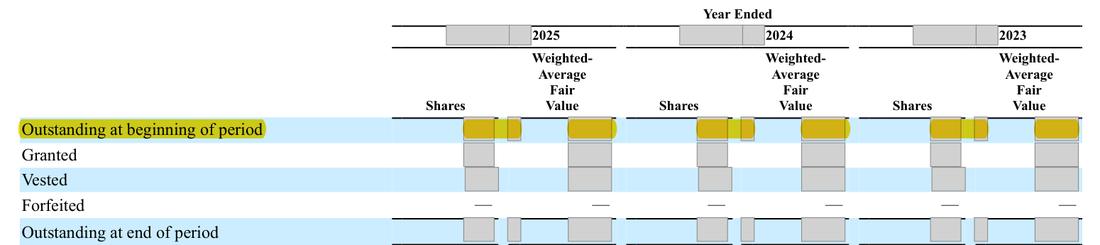
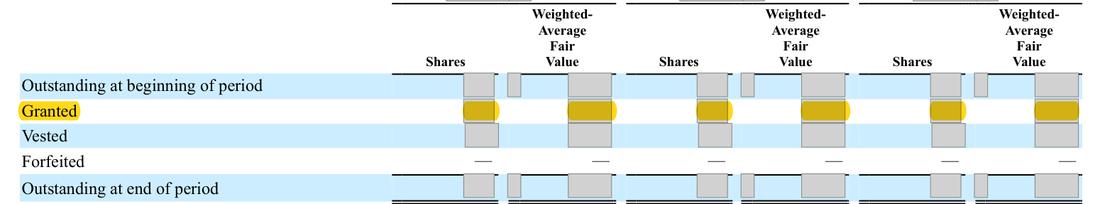
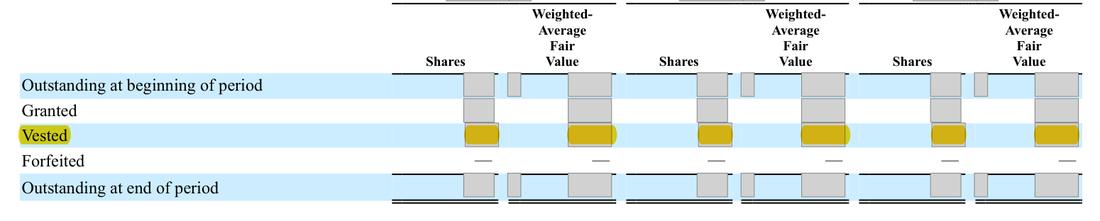
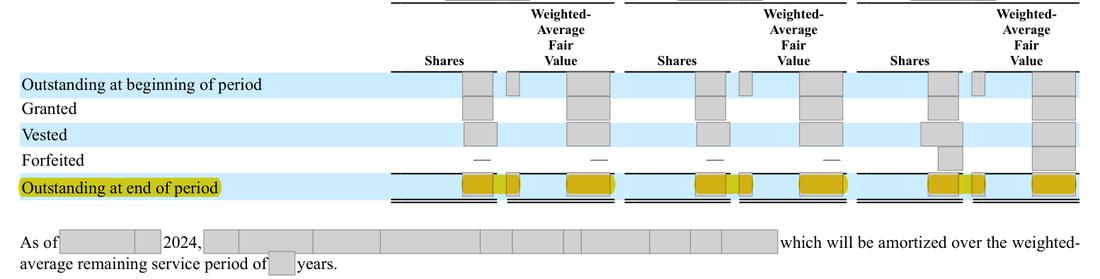
Note 7 shows [n] restricted shares outstanding at the start of fiscal 2025 at a weighted-average grant-date fair value of [amount], [n] granted at [amount] and [n] vested at [amount], leaving [n] at [amount]. Rolled forward, the printed lines give [n] per share, a gap of [n] dollars of grant-date value; rounding of the share counts can explain at most [n]. The same test reproduces the fiscal 2024 column exactly, so one of the fiscal 2025 figures is not on the grant-date basis or is mis-keyed.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Closing line printed as [n] at [amount]; the printed opening, granted and vested lines give [n] / [n] = [n]. | Opening, granted, vested, forfeited and closing weighted-average grant-date fair values that reconcile, each on the grant-date basis. |
The rule
FASB ASC 718-10-50-2 (award activity for nonvested shares: number and weighted-average grant-date fair value at the start and end of the year and for shares granted, vested and forfeited)
Summary; FASB/IFRS text is copyrighted Disclose share-based arrangement terms, fair-value methods and assumptions, award activity, compensation cost and tax effects, and unrecognised cost with weighted-average recognition period.
Version: Text as amended up to fiscal 2025 · Source: FASB Accounting Standards Codification, ASC 718-10-50-1 to 50-2 (as amended to fiscal 2025), paraphrased
Why it applies here. the award-activity disclosure for nonvested shares is a weighted-average grant-date fair value table, so every line must be on that basis for it to reconcile. Possible causes are a vested line stated at the market price on vesting instead of grant-date fair value, or a slip in the closing or granted value; the report does not show which.
Why it matters
Readers using the table to estimate future expense or dilution value cannot rely on the closing weighted-average fair value; a required disclosure carries a figure that does not reconcile.
Exposure
A disclosure-table question; no measurement effect is shown and no fine applies.
Our workings
the fiscal 2025 restricted stock table prints opening [n] at [amount], granted [n] at [amount], vested ([n]) at [amount], no forfeitures, closing [n] at [amount]; the share counts add up. The prior-year report printed the fiscal 2024 closing as [n] at [amount], the same as this year's opening.
opening, granted and vested values give a closing value of [n], or [n] per share, against [n] printed ([n] at [amount]); the gap is [n]. Share counts rounded to thousands can move the result by at most [n]. On the same method the fiscal 2024 column reconciles to [amount] exactly and the restricted stock unit table to within two cents; the fiscal 2023 column is also off ([n] against [n]).
| Line | Computation | Value |
|---|---|---|
| Opening | [n] x [n] = [n] | [n] |
| Granted | [n] x [n] = [n] | [n] |
| Vested | [n] x [n] = [n] | [n] |
| Closing by roll-forward | [n] + [n] - [n] = [n] | [n] |
| Implied closing weighted-average fair value | [n] / [n] = [n] | [n] |
| Printed closing | [n] x [n] = [n] | [n] |
| Gap | [n] - [n] = [n] | [n] |
| Test | Computation | Result |
|---|---|---|
| Fiscal 2024 restricted stock | ([n] x [n] + [n] x [n] - [n] x [n]) / [n] = [n] | agrees with [n] printed |
| Fiscal 2023 restricted stock | ([n] x [n] + [n] x [n] - [n] x [n]) / [n] = [n] | [n] printed |
| Largest effect of rounding the fiscal 2025 share counts | [n] x ([n] + [n] + [n] + [n]) = [n] | [n] |
Management’s best defense, and our reply
The finance team could say the table is prepared from the equity plan administrator's award-level records, which value each tranche separately, and that rounding share counts to thousands always leaves small differences. It could add that the table has no effect on the expense recognized, which is computed award by award, and that unrecognised compensation cost is disclosed separately. However, rounding of the share counts can explain at most [n] of the [n] gap, and the fiscal 2024 column reconciles exactly on the same method, so a figure in the fiscal 2025 column is on another basis or is wrong; only the company's records can say which, so this is a question.
The fix
- Re-run the fiscal 2025 (and fiscal 2023) roll-forward from the award-level records on the grant-date basis and correct the line that differs.
Question for the company
Which figure in the fiscal 2025 restricted stock table is not on the grant-date basis or is mis-stated: the closing weighted-average fair value of [amount], the granted value of [amount] or the vested value of [amount]? Is the vested line measured at grant-date fair value, and what are the corrected figures (and for the fiscal 2023 column)?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Opening restricted shares and weighted-average fair value for each year | Document | Form 10-K 2025, page 74 |
| 2 | Shares granted and their weighted-average fair value | Document | Form 10-K 2025, page 74 |
| 3 | Shares vested and the value attached to them | Document | Form 10-K 2025, page 74 |
| 4 | Closing restricted shares and the printed weighted-average fair value | Document | Form 10-K 2025, page 74 |
| 5 | The prior-year report printed the same fiscal 2024 closing, so the fiscal 2025 opening is not the source of the gap | Document | Form 10-K 2024 (prior year), page 74 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.