6.06 Accounting policy note carries wording from another framework and superseded guidance, and one comparative figure is mistyped
Company H · a US-listed aerospace services company · Drafting slip
In brief
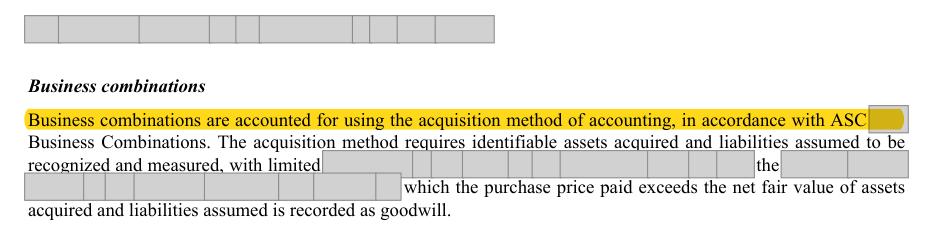
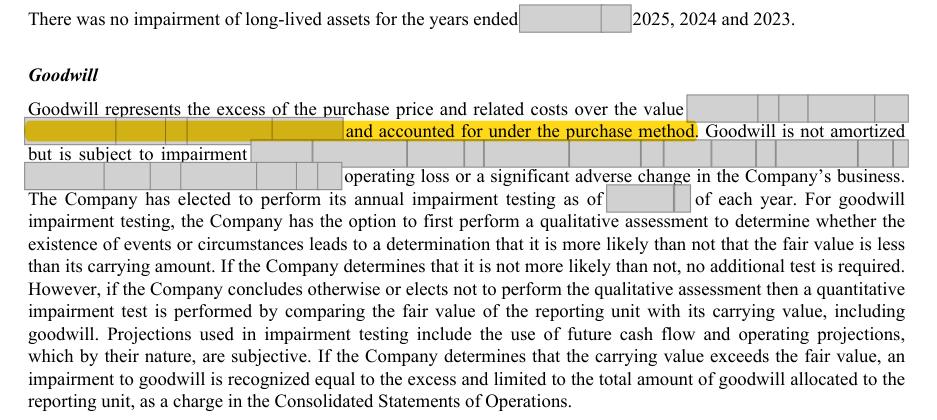
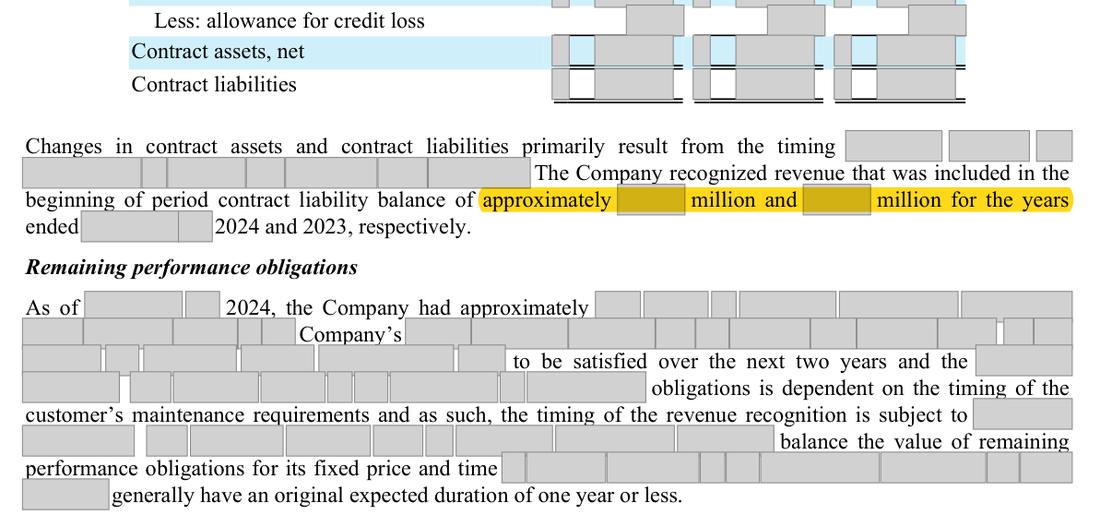
Five passages in the notes do not read as current US GAAP wording. The financial instruments policy describes classification by 'business model' and 'nature of the cash flows', which is International Financial Reporting Standards (IFRS) wording; the goodwill policy refers to the 'purchase method' although the business combinations policy uses the acquisition method; the pension corridor is described against the 'accumulated postretirement benefit obligation'; the hedging policy still elects reference rate reform expedients for 'future LIBOR-indexed cash flows'; and the revenue note prints '[amount]' where the prior-year Form 10-K printed '[amount]'. The prior-year Form 10-K carried the same wording: the 'purchase method' in the goodwill policy (page 84), the corridor on the 'accumulated postretirement benefit obligation' (page 85) and the expedients for 'future LIBOR-indexed cash flows' in the hedging policy.
The evidence, as filed
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Policy text: classification 'dependent on the business model and the nature of the cash flows'; goodwill 'accounted for under the purchase method'; corridor of 'the accumulated postretirement benefit obligation'; expedients for 'future LIBOR-indexed cash flows'. Revenue note: '[amount]' for 2023. | US GAAP terms: financial assets classified under the US GAAP categories actually used (amortized cost, fair value through net income, designated hedges); 'acquisition method'; corridor of the projected benefit obligation or the market-related value of plan assets; the reference rate reform sentence removed or put in the past tense; '[amount]'. |
Why it matters
Policy wording that names another framework or superseded guidance invites a staff question on whether the policy applied is the US GAAP one, and weakens the reader's confidence in the policy note.
Exposure
Drafting only; no recognized amount is affected.
Our workings
each phrase is printed on the pages cited; the same policy wording was printed in the prior-year Form 10-K.
these are carried-over or template phrases; none changes a recognized amount, so each is a drafting slip. The business-model and cash-flow-characteristics test is the classification model of IFRS 9, not of US GAAP, and sits beside a basis-of-presentation statement that the statements follow US GAAP. The 'purchase method' was replaced by the acquisition method, which the business combinations policy on an earlier page already applies. For pensions the corridor is measured against the projected benefit obligation; the accumulated postretirement benefit obligation is the measure for other postretirement benefits. The reference rate reform relief was time-limited and the term debt described in the debt note is no longer LIBOR-indexed. The 2023 figure for revenue recognized from the opening contract liability balance was printed with two decimals in the prior-year report as [amount].
Management’s best defense, and our reply
The finance team would say these passages are long-standing policy text, that the auditor has accepted them for several years, and that no figure in the statements depends on them. They would add that the two-decimal figure is a narrative comparative which readers can check against the prior-year report. That does not cure the wording: the policy note must describe the policies actually applied under US GAAP, and each passage either names a framework the company does not use or guidance that no longer applies, so each should be corrected in the next filing.
The fix
- Replace the financial instruments paragraph with the US GAAP categories used; read 'acquisition method' in the goodwill policy; describe the corridor against 'the projected benefit obligation or the market-related value of plan assets'; delete or past-tense the LIBOR expedient sentence; correct '[amount]' to '[amount]'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Basis of presentation: US GAAP | Document | Form 10-K 2025, page 80 |
| 2 | Financial instruments policy uses the IFRS classification test | Document | Form 10-K 2025, page 88 |
| 3 | Business combinations policy applies the acquisition method | Document | Form 10-K 2025, page 82 |
| 4 | Goodwill policy still names the superseded purchase method | Document | Form 10-K 2025, page 86 |
| 5 | Pension corridor described against the postretirement (not projected) benefit obligation | Document | Form 10-K 2025, page 87 |
| 6 | Reference rate reform expedient still described as elected for LIBOR-indexed cash flows | Document | Form 10-K 2025, page 89 |
| 7 | 2023 figure printed as [amount] | Document | Form 10-K 2025, page 91 |
| 8 | Prior-year Form 10-K printed the 2023 figure as [amount] | Document | Form 10-K 2024 (prior year), page 89 |
| 9 | Same IFRS classification wording in the prior-year Form 10-K | Document | Form 10-K 2024 (prior year), page 85 |
| 10 | Prior-year goodwill policy uses the superseded 'purchase method' term, carried unchanged into the current 10-K | Document | Form 10-K 2024 (prior year), page 84 |
| 11 | Prior-year pension policy applies the corridor to the 'accumulated postretirement benefit obligation' although the plans are defined benefit pension [wording masked] | Document | Form 10-K 2024 (prior year), page 85 |
| 12 | Prior-year derivatives policy still describes reference-rate reform expedients for LIBOR-indexed cash flows | Document | Form 10-K 2024 (prior year), unnumbered page |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.