5.01 The company's decision on how often to hold the say-on-pay vote was not reported by its fourth-quarter deadline, and Item 9B(a) of the 10-K says 'None'
Company H · a US-listed aerospace services company · Compliance or disclosure gap
In brief
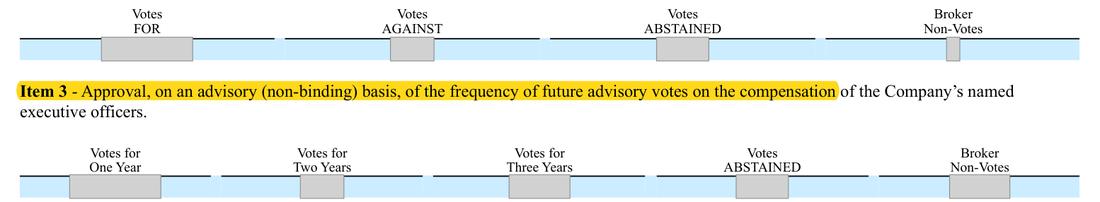
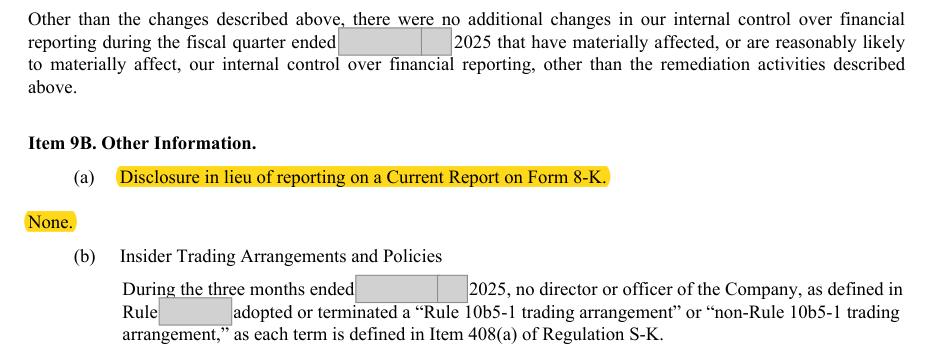
At the [date] annual meeting, stockholders voted on how often to hold the advisory vote on executive pay. The Form 8-K of [date] reported only the votes; Form 8-K Item 5.07(d) then required the company to report its own decision by amendment, by [date] at the latest, and no amendment, Form 10-Q or other filing did so. Because the deadline fell in the fourth quarter, Item 9B(a) of this 10-K had to give the decision; it says 'None'. The Board's decision was first stated in the [date] proxy statement.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Form 8-K of [date] gives the frequency vote results and says stockholders approved annual votes; no amended Form 8-K for the annual meeting, and the [n]-Qs for the second and third quarters are silent; 10-K Item 9B(a): 'None.' | By [date], a Form 8-K/A to the [date] report (or a periodic report filed by then) stating the company's decision to hold the say-on-pay vote every year; failing that, the decision given in Item 9B(a) of this 10-K. |
| What we checked. Form 8-K of [date] (Item 5.07); the 2025 proxy for the Rule 14a-8 deadline; every 8-K and 8-K/A on EDGAR from [date] to the 10-K date; the Forms 10-Q for the second and third quarters of 2025; Item 9B of this 10-K; the 2026 proxy. | |
The rule
Form 8-K, Item 5.07(d)
No later than one hundred fifty calendar days after the end of the annual or other meeting of shareholders at which shareholders voted on the frequency of shareholder votes on the compensation of executives ... by amendment to the most recent Form 8-K filed pursuant to (b) of this Item, disclose the company's decision in light of such vote as to how frequently the company will include a shareholder vote on the compensation of executives in its proxy materials
Version: Text in force at the date of this review · Source: Form 8-K (SEC [n], revised [date]), Item 5.07(d)
Form 10-K, Item 9B(a)
The registrant must disclose under this item any information required to be disclosed in a report on Form 8-K during the fourth quarter of the year covered by this Form 10-K, but not reported, whether or not otherwise required by this Form 10-K.
Version: Text in force at the date of this review · Source: Form 10-K (SEC [n], revised [date]), Item 9B(a)
Exchange Act Form 8-K Compliance and Disclosure Interpretation 121A.04
an issuer may report Item 5.07 Form 8-K information in a periodic report that is filed on or before the date that an Item 5.07 Form 8-K would otherwise be due
Version: Text in force at the date of this review · Source: SEC Division of Corporation Finance, Exchange Act Form 8-K Compliance and Disclosure Interpretations, Question 121A.04
Why it applies here. The earlier of the two dates, [date], fell in the fourth quarter, so the decision belonged in Item 9B(a). Stockholders' preference is not the company's decision, which Item 5.07(d) asks for in terms.
Why it matters
- The filing record lacked a required statement for about six months, Item 9B(a) of the 10-K is inaccurate, and the cover-page statement that all required reports were filed rests on an incomplete record.
- The substance was never in doubt: [n]% of votes cast favored an annual vote and the vote was held again in 2026. A staff comment, answered by a Form 8-K/A, is the realistic outcome.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, executive compensation and governance drew 4 of the 1,774 numbered comments (0.2%): topic 21 of 25 by frequency.
Exposure
A staff comment asking for a Form 8-K/A and an accurate Item 9B in future; no fixed penalty.
Our workings
the [date] Form 8-K reported the advisory vote on the frequency of say-on-pay votes and closed by saying the stockholders approved, on an advisory basis, that future votes be held every year. Item 5.07(d) of Form 8-K requires a separate statement of the company's decision in light of that vote, by amendment to the Item 5.07 report, within 150 calendar days after the meeting and in no event later than 60 calendar days before the Rule 14a-8 deadline in the last proxy. The SEC staff interpretation allows the decision to be given instead in a periodic report filed by that date.
the 2025 proxy set the Rule 14a-8 deadline at [date], so the outer date is [date], earlier than the 150-day date of [date]; [date] lies in the fourth fiscal quarter.
EDGAR shows no Form 8-K/A under Item 5.07 (the two 2025 amendments concern Item 5.02), and the Forms 10-Q for the second and third quarters contain no such statement.
Item 9B(a) of this 10-K, which must carry any information required on Form 8-K in the fourth quarter but not reported, says 'None'.
the decision was required in this 10-K and is missing; the first statement of it is the 2026 proxy, 185 days after the due date.
| Step | Date or computation | Result |
|---|---|---|
| Annual meeting | [date] | Frequency vote held |
| 150 calendar days after the meeting | [date] + 150 days = [date] | Sunday |
| Rule 14a-8 deadline in the 2025 proxy, less 60 days | [date] - 60 days = [date] | Earlier date governs |
| Due date | [date] | Fourth fiscal quarter (1-Oct to [date]) |
| First statement of the decision | 2026 proxy, [date] | [date] to [date] = 185 days |
| Votes for one year | [n] / ([n] + [n] + [n] + [n]) = [n] / [n] | [n]% |
Management’s best defense, and our reply
Management would say nothing was hidden: the [date] Form 8-K showed that [n]% of the votes cast favoured an annual vote and stated that future votes would be held every year, and the company did hold the vote again in 2026. It may add that the 8-K's closing sentence was intended as the decision. However, that sentence reports what the stockholders approved on an advisory basis; Item 5.07(d) asks for the company's own decision by a fixed date, the staff interpretation offers only a periodic report filed by that date as an alternative, and Item 9B(a) exists to catch a fourth-quarter 8-K item that was missed. The point stands, though its weight is low.
The fix
- File a Form 8-K/A to the [date] report: 'In light of the vote, the Board has determined to hold an advisory vote on named executive officer compensation every year until the next required frequency vote.' Add a check of Item 5.07(d) and other trailing 8-K items to the Item 9B(a) close procedure.
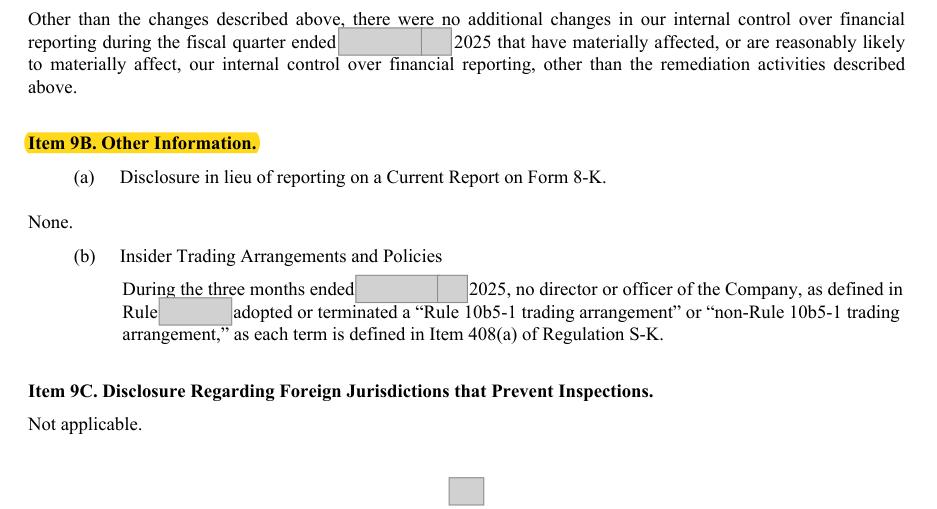
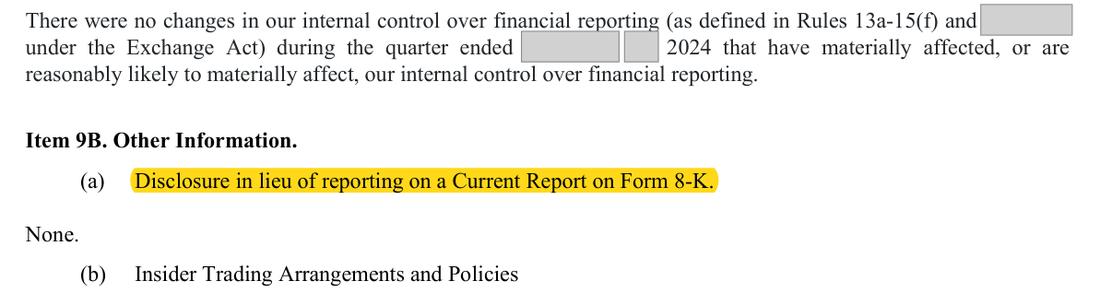
Item 9B(a), page 134: Disclosure in lieu of reporting on a Current Report on Form 8-K
Also: file the same statement as a Form 8-K/A to the [date] report
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The 2025 annual meeting held the frequency vote | Document | |
| 2 | Votes for one, two and three years, abstentions and broker non-votes | Document | |
| 3 | The 8-K reports what stockholders approved, not the company's decision | Document | |
| 4 | Rule 14a-8 deadline that fixes the outer due date | Document | |
| 5 | Item 9B(a) of this 10-K reports nothing | Document | Form 10-K 2025, page 134 |
| 6 | The Board's decision first stated in the [date] proxy | Document |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Item 9B. Other Information.
- What is missing
- the company's decision on how often it will hold the advisory vote on executive pay, required on Form 8-K in the fourth quarter and not reported
- Pages looked at
- p.134 (Item 9B), p.135-139 (Part III), p.51 (Item 5)
- Result
- 'frequency' hits only p.23, a risk factor on the frequency of cyberattacks; 'say-on-pay', 'advisory vote' and 'every year' do not hit.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.