4.05 The MD&A puts all [amount] of 2024 refinancing costs on the March and [date] amendments; the debt note puts [amount] on the [date] New Credit Agreement
Company H · a US-listed aerospace services company · Presentation point
In brief
The fiscal 2025 management's discussion and analysis (MD&A) says the [amount] of 2024 refinancing costs was associated with the March and [date] amendments of the Prior Credit Agreement. The debt note in the same 10-K splits the [amount]: [amount] for the New Credit Agreement, [amount] for the New 2024 Term Loan Facilities, [amount] for the September amendment and [amount] for the March amendment. Only [amount] relates to the two amendments. The prior-year 10-K's MD&A gave this split correctly.
The evidence, as filed
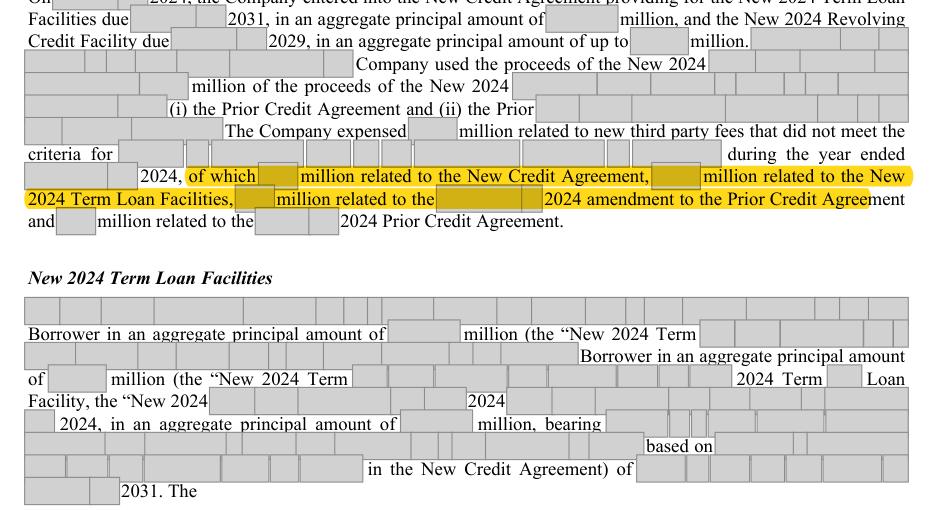
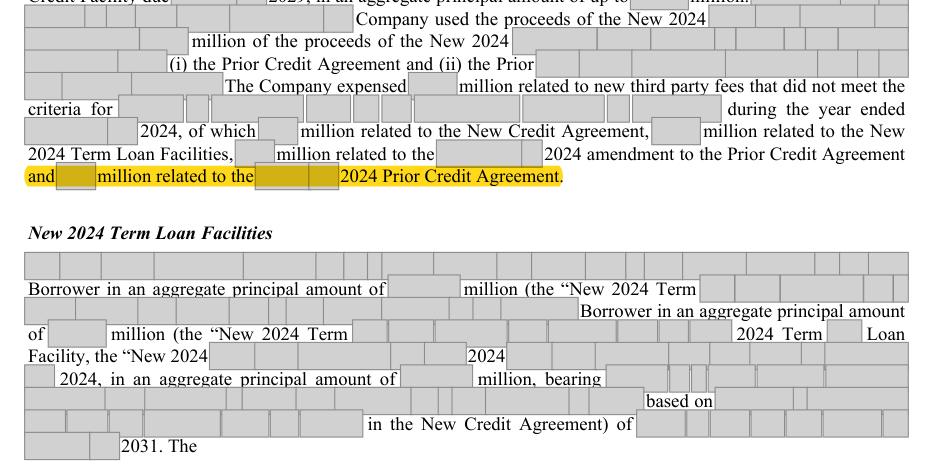
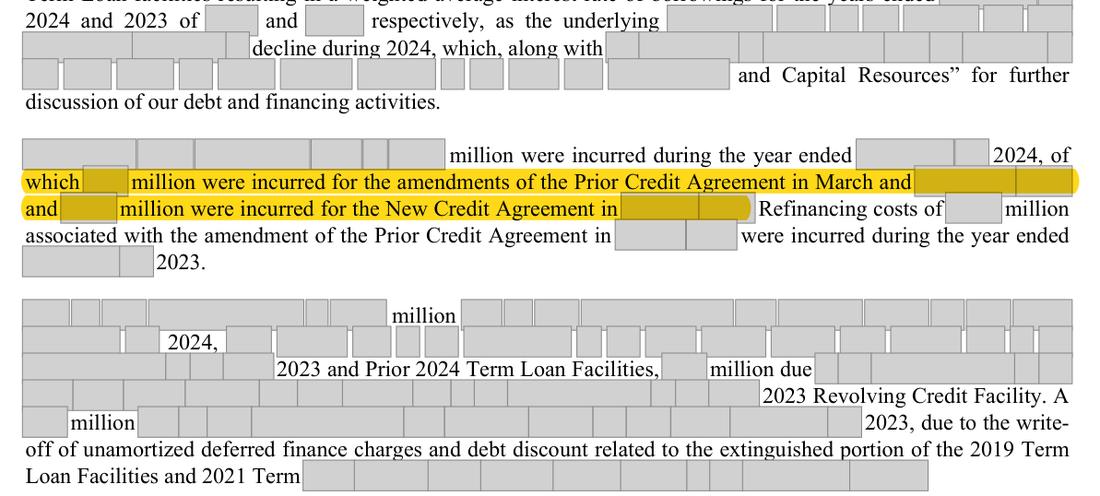
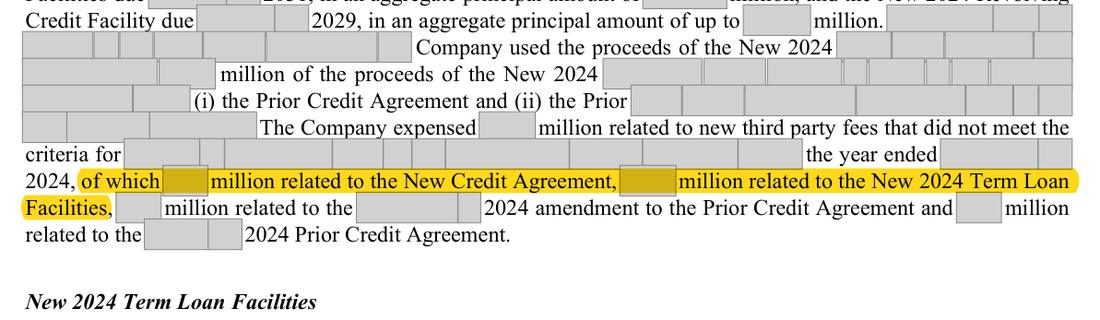
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
MD&A: refinancing costs of [amount] 'associated with the modified portion of the Prior Credit Agreement amendments in March and [date]'. Debt note: [amount] + [amount] = [amount] related to the [date] New Credit Agreement and its term loans, and [amount] + [amount] = [amount] to the two amendments. | The MD&A describes the 2024 refinancing costs as the debt note and the prior-year MD&A do: [amount] for the March and [date] amendments of the Prior Credit Agreement and [amount] for the New Credit Agreement in [date]. |
The rule
Regulation S-K Item 303(b)
Where the financial statements reflect material changes from period-to-period in one or more line items, including where material changes within a line item offset one another, describe the underlying reasons for these material changes in quantitative and qualitative terms.
Version: Text in force at the date of this review · Source: 17 CFR 229.303 (Regulation S-K Item 303), as amended by Release 33-10890
Why it applies here. [amount] of the [amount], about 73%, relates to the [date] New Credit Agreement, the refinancing behind the lower 2025 interest cost, not to the amendments. The total agrees with the income statement; only the description is wrong.
Why it matters
- A reader of MD&A is told the 2024 costs came from amending the old facility, when most came from the [date] refinancing that drives the lower 2025 interest cost.
- At most a staff comment asking for consistent wording; no amount changes.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, MD&A results of operations drew 239 of the 1,774 numbered comments (13.5%): the third most frequent topic.
Exposure
A staff comment on the consistency of the MD&A with the financial statements, answered by correcting the description in the next Form 10-K; no change to any reported figure.
Our workings
the fiscal 2025 MD&A explains the absence of refinancing costs in 2025 by saying that the [amount] incurred in 2024 was associated with the modified portion of the Prior Credit Agreement amendments in March and [date]. The debt note of the same 10-K says that, of the [amounts] related to the New Credit Agreement, [amount] to the New 2024 Term Loan Facilities, [amount] to the [date] amendment and [amount] to the [date] amendment. The prior-year 10-K's MD&A said [amount] was incurred for the March and September amendments and [amount] for the New Credit Agreement in [date].
[amount] + [amount] = [amount]; [amount] + [amount] = [amount]; [amount] + [amount] = [amount] (workings).
the total is unchanged and agrees with the income statement, and the MD&A's own description of this line item correctly names both the March and [date] amendments and the [date] New Credit Agreement, so the slip is confined to the results paragraph. Only the MD&A's description of what the costs related to has changed, and it now disagrees with the audited note. Item 303(b) asks for the reasons for material changes in line items, and the reason given for the [amount] fall in this line is wrong for nearly three quarters of the amount.
| Component (debt note) | Amount ($ million) | Relates to |
|---|---|---|
| New Credit Agreement + New 2024 Term Loan Facilities | [n] + [n] = [n] | [date] refinancing |
| [date] amendment + [date] amendment | [n] + [n] = [n] | March and [date] amendments |
| Total refinancing costs 2024 | [n] + [n] = [n] | as stated in both the MD&A and the note |
Management’s best defense, and our reply
The [date] New Credit Agreement refinanced the Prior Credit Agreement, and the fees were expensed because they related to the modified portion of the prior term loans. On that reading all [amount] is 'associated with the modified portion of the Prior Credit Agreement', and the total is correct. However, the MD&A ties the costs to the 'amendments in March and [date]', and the [date] transaction was a new agreement, not one of those amendments. The note in the same 10-K, and the prior-year MD&A, give [amount] to the New Credit Agreement. The total stands, but the description of what it related to does not.
The fix
- Replace the sentence with: 'Refinancing costs of [amount] were incurred during the year ended [date], of which [amount] related to the March and [date] amendments of the Prior Credit Agreement and [amount] to the New Credit Agreement entered into in [date], with no similar charges incurred in the year ended [date].'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Fiscal 2025 MD&A attributes the whole [amount] to the March and [date] amendments | Document | Form 10-K 2025, page 60 |
| 2 | Debt note in the same 10-K: [amounts] relate to the [date] New Credit Agreement and its term loans; [amount] to the September amendment | Document | Form 10-K 2025, page 99 |
| 3 | The remaining [amount] relates to the [date] amendment | Document | Form 10-K 2025, page 99 |
| 4 | Prior-year MD&A gave the correct split: [amount] for the amendments and [amount] for the New Credit Agreement | Document | Form 10-K 2024 (prior year), page 59 |
| 5 | Prior-year debt note: the same split as the fiscal 2025 note | Document | Form 10-K 2024 (prior year), page 98 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.