1.06 The parent-company balance sheet labels as 'accumulated deficit' a figure that also contains accumulated other comprehensive loss
Company H · a US-listed aerospace services company · Presentation point
In brief
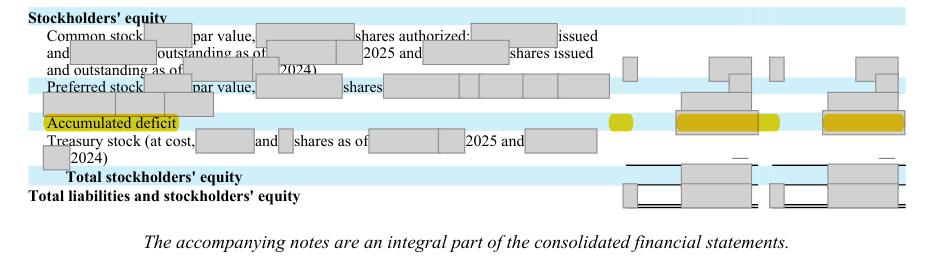
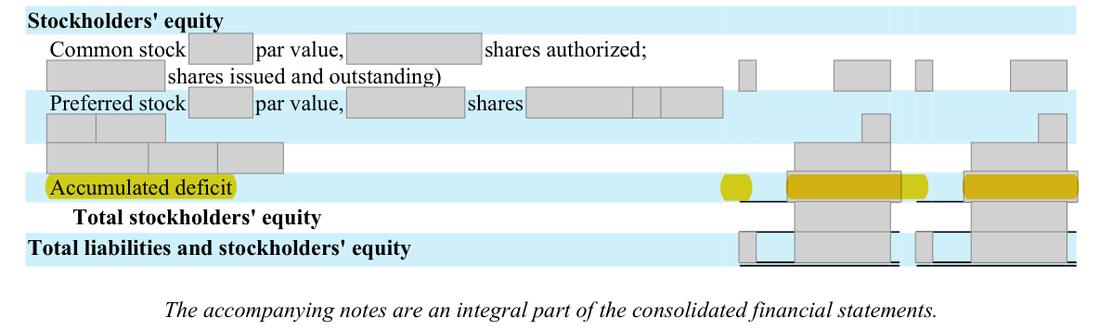
Note 25 shows the parent company's accumulated deficit as ([n]) at [date] and ([n]) at [date]. The consolidated balance sheet shows the accumulated deficit as ([n]) and ([n]), with accumulated other comprehensive loss of ([n]) and ([n]) on a separate line. The parent figure is the sum of the two consolidated lines, so the same caption carries two different amounts in one filing; the prior-year report did the same.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 25 parent balance sheet: 'Accumulated deficit ([n]) ([n])'; no accumulated other comprehensive loss line | Either a separate 'Accumulated other comprehensive loss ([n]) ([n])' line with accumulated deficit ([n]) ([n]), as in the consolidated balance sheet, or a caption that says the line combines both |
| What we checked. Note 25 parent-company balance sheet and statement of operations against the consolidated balance sheet; the prior-year Note 25 | |
Why it matters
- Two accumulated-deficit figures for the same date appear in one audited filing, which invites a reconciliation question from readers and from the staff.
- At most a staff comment; total equity is unaffected.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, financial statement presentation drew 254 of the 1,774 numbered comments (14.3%): the second most frequent topic.
Exposure
Presentation only; equity totals agree.
Our workings
the Note 25 parent-company balance sheet prints accumulated deficit of ([n]) and ([n]) and no accumulated other comprehensive loss line; total equity is [n] and [n]. The consolidated balance sheet prints accumulated deficit of ([n]) and ([n]) and accumulated other comprehensive loss of ([n]) and ([n]), with the same equity totals.
[n] + [n] = [n] and [n] + [n] = [n], so the parent line is the two consolidated lines added together. The parent statement of operations shows equity in other comprehensive income of subsidiaries of [n] for 2025, which the parent then carries inside the 'accumulated deficit' line.
the parent presentation merges accumulated other comprehensive loss into the deficit without saying so, so a reader comparing Note 25 with the consolidated balance sheet sees two different accumulated deficits for the same company at the same date. The 2024 Form 10-K's Note 25 used the same presentation.
| Year end | Consolidated accumulated deficit + accumulated other comprehensive loss | Parent 'accumulated deficit' |
|---|---|---|
| [date] | [n] + [n] = [n] | ([n]) |
| [date] | [n] + [n] = [n] | ([n]) |
Management’s best defense, and our reply
The company would say Rule 12-04(a) of Regulation S-X allows the parent information to be condensed to the level of condensed interim statements, which permits combining captions, and that the equity totals agree with the consolidated balance sheet. It would add that the parent statement of operations shows the other comprehensive income, so a reader can rebuild the split. Combining is indeed allowed. However, a combined line must be named for what it holds; calling it 'accumulated deficit' prints a second, different accumulated deficit for the same date, which is the inconsistency raised here.
The fix
- In Note 25, add 'Accumulated other comprehensive loss ([n]) ([n])' and show accumulated deficit as ([n]) ([n]), or rename the line 'Accumulated deficit and accumulated other comprehensive loss'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Note 25 parent balance sheet: the 'accumulated deficit' line, with no separate other comprehensive loss line | Document | Form 10-K 2025, page 127 |
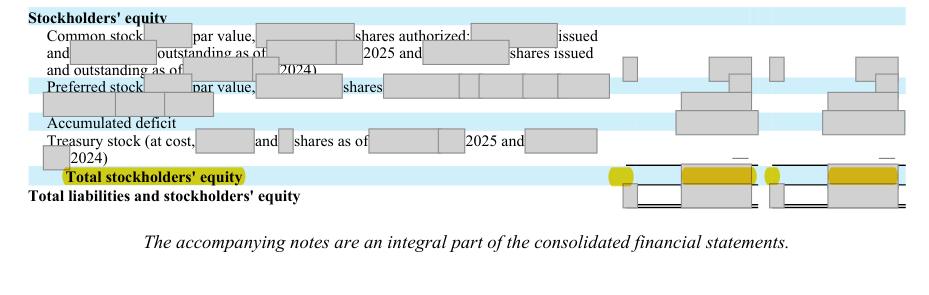
| 2 | Parent equity totals equal the consolidated totals | Document | Form 10-K 2025, page 127 |
| 3 | Consolidated balance sheet accumulated deficit | Document | Form 10-K 2025, page 75 |
| 4 | Consolidated balance sheet shows accumulated other comprehensive loss on its own line | Document | Form 10-K 2025, page 75 |
| 5 | The parent records other comprehensive income, which it then carries inside the deficit line | Document | Form 10-K 2025, page 128 |
| 6 | Prior-year parent-only balance sheet: one caption for deficit and AOCI | Document | Form 10-K 2024 (prior year), page 123 |
| 7 | Prior-year consolidated balance sheet shows the two lines separately | Document | Form 10-K 2024 (prior year), unnumbered page |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.