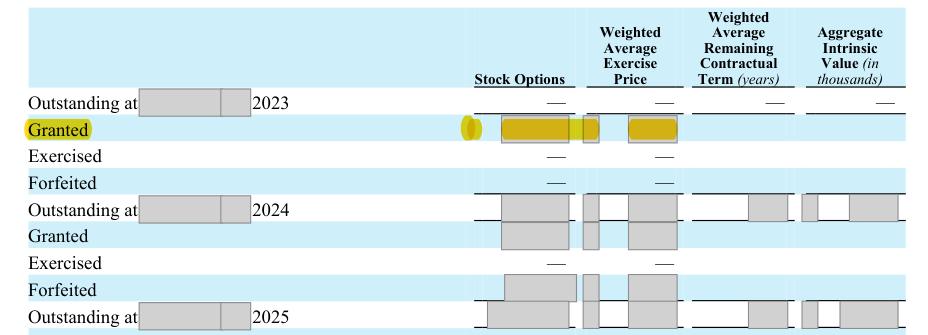
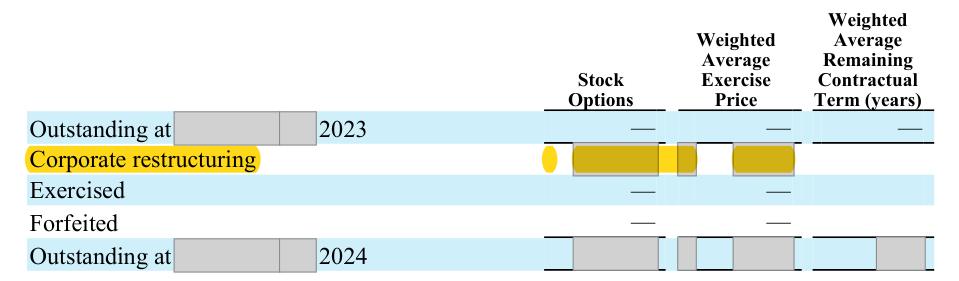
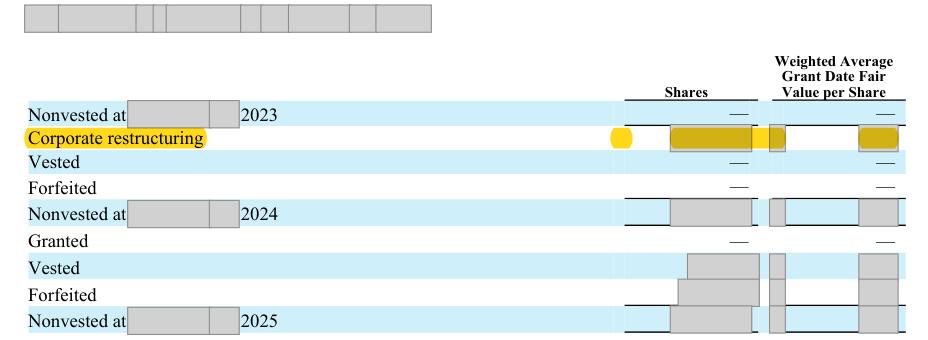
1.05 The option table now calls the [n] options that the prior 10-K showed as arising from the 2024 restructuring 'Granted'; the prior 10-K and the RSA table call the same event 'Corporate restructuring'
Company H · a US-listed aerospace services company · Presentation point
In brief
The 2025 option activity table shows [n] options at a [amount] weighted-average exercise price as 'Granted' in 2024. The prior 10-K presented the identical row as 'Corporate restructuring', and the restricted stock award (RSA) table in the same note still uses that label for awards converted in the same transactions. The relabelled row reads as new 2024 grants at [amount], for which the note gives no grant-date fair value or assumptions.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
2024 row of the option table: 'Granted [n] [amount]'. | 'Corporate restructuring [n] [amount]', as in the prior 10-K and the RSA table; or, if these were new grants, their grant-date fair value and valuation assumptions. |
Why it matters
- A reader of the 2025 table alone would take the row as 2024 option grants at [amount] and look for a fair value and assumptions the note does not give.
- At most a staff comment asking for consistent labels; no amount changes.
Exposure
Presentation only; no recognized amount is affected.
Our workings
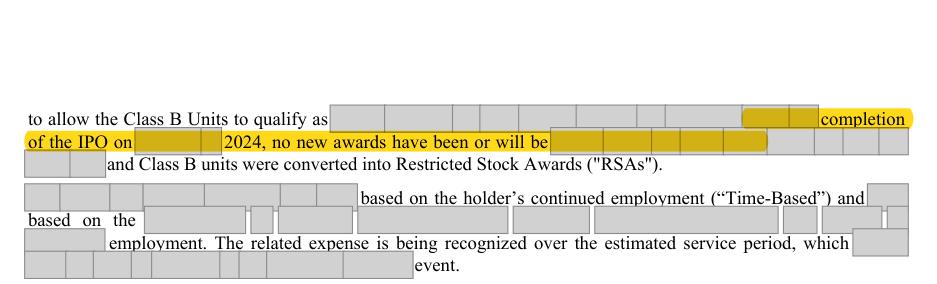
The 2025 option table labels the 2024 movement of [n] options at [amount] 'Granted'. The prior 10-K labelled the same movement 'Corporate restructuring', and the RSA table on the next page of this note labels the conversion of Prior Plan units into [n] RSAs 'Corporate restructuring'. The note also says that no new awards have been issued under the Prior Plan since the IPO, and the options exercisable at [date] carry a weighted-average remaining contractual term of [n] years.
Read with the restructuring narrative, the options are Prior Plan awards carried into the Company's stock in the restructuring, not grants made in 2024; under US GAAP an exchange of awards in an equity restructuring is accounted for as a modification of existing awards rather than a new grant. The label change alters no figure, but a reader of the 2025 table alone would take it that the company granted options at [amount] in 2024 and would look for their grant-date fair value, which the note does not give.
Management’s best defense, and our reply
The company could say that the Company first issued these options over its own stock in 2024 when Prior Plan awards were converted, so 'Granted' describes the issuer's act, and that the row carries the same number and price as before so nothing changed. However, the company itself labels the identical event 'Corporate restructuring' in the RSA table of the same note and did so for these options in the prior 10-K, and US GAAP treats an exchange of awards in a restructuring as a modification of existing awards, not a new grant; the new label therefore changes what the table reports.
The fix
- Restore the label 'Corporate restructuring' (or 'Converted in the restructuring transactions') for the 2024 row of the option table, consistent with the RSA table.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | 2025 option table: the 2024 movement is labelled 'Granted' | Document | Form 10-K 2025, page 116 |
| 2 | Prior 10-K: the same 2024 movement was labelled 'Corporate restructuring' | Document | Form 10-K 2024 (prior year), page 113 |
| 3 | RSA table in the same note keeps the 'Corporate restructuring' label for the same transactions | Document | Form 10-K 2025, page 117 |
| 4 | No new Prior Plan awards after the IPO | Document | Form 10-K 2025, page 114 |
| 5 | Exercisable options with a [n]-year remaining contractual term | Document | Form 10-K 2025, page 116 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.