4.07 Lease note: the financing cash outflow for finance leases is the same figure as the finance-lease interest cost in every year
Company G · a US-listed specialty pharmaceutical company · Drafting slip
In brief
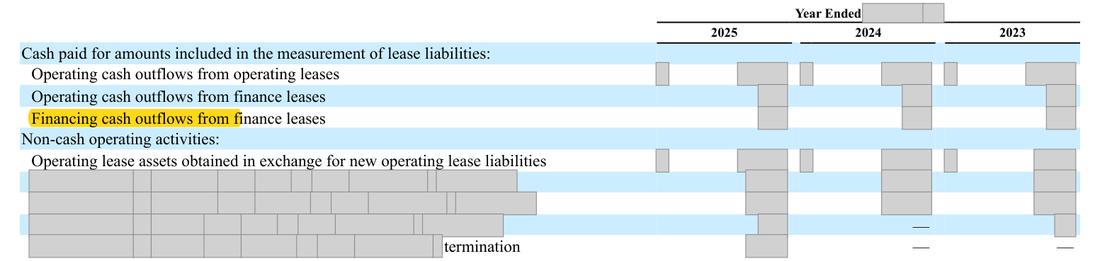
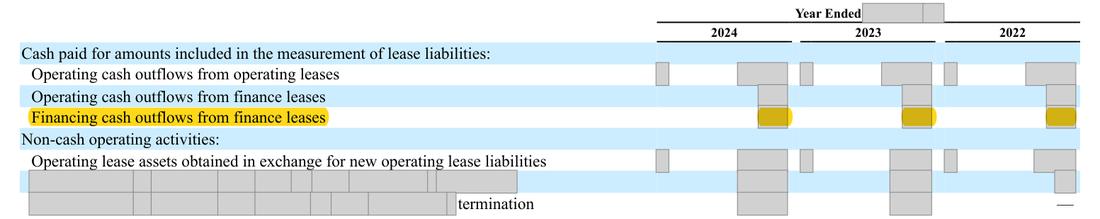
In the lease note, 'Financing cash outflows from finance leases' shows [n], exactly the figures shown as 'Interest on lease liabilities' in the lease cost table; the prior-year 10-K shows the same match ([n]). The cash-flow statement has no finance-lease line in financing activities: its 2025 financing lines add to the reported total without one. One row may carry the other's figure; it should be confirmed before the next 10-K.
The evidence, as filed
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Lease note: financing cash outflows from finance leases [n] / [n] / [n], the same as interest on lease liabilities [n] / [n] / [n]; cash-flow statement: no finance-lease line in financing activities in any year | The financing row shows principal repaid on finance leases and the operating row the interest paid, each confirmed to the lease ledger |
Why it matters
A reader cannot tell from the lease note how much finance-lease cash went to interest and how much to principal.
Exposure
Presentation slip in a note; amounts are immaterial.
Our workings
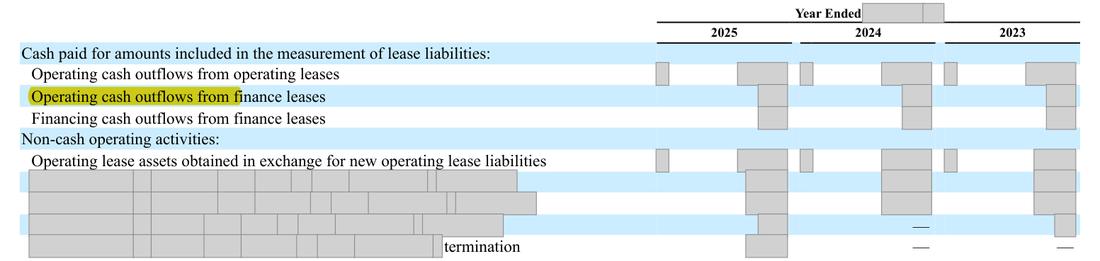
the supplemental cash-flow table on F-29 gives financing cash outflows from finance leases of [n] for 2025, 2024 and 2023, and the finance lease cost table on F-28 gives interest on lease liabilities of exactly [n]. The prior-year 10-K shows the same match, including [n] for 2022. The consolidated statement of cash flows (F-8) shows no finance-lease line in financing activities: repayments of long-term debt, share repurchases, withholding taxes on share awards and plan proceeds make up the whole 2025 financing total.
a figure that equals the interest cost in four consecutive years, and that does not appear as a financing line in the statement, suggests one table has taken its figure from the other. The 10-K does not show which row is right, and a simple swap of the two finance-lease row labels is not established either. The amounts are under one million dollars and no cash-flow statement subtotal is affected.
Management’s best defense, and our reply
The finance team could say the amounts are trivial against total operating cash flows and that the cash-flow statement itself does not present a finance-lease line, so no reader is misled. It could also say the financing row may be the true principal repayment and the match with interest a coincidence. A match in four consecutive years is unlikely to be chance, so the row should still be confirmed, but the size keeps it a drafting point.
The fix
- Re-derive both finance-lease rows from the lease ledger (interest paid in operating activities, principal repaid in financing activities) and correct the label or the figure in the next 10-K.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | F-29: the financing outflow row for finance leases, 2025-2023 | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 2 | F-29: the operating outflow row for finance leases | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 3 | F-28: interest on finance lease liabilities equals the financing outflow row in every year | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 4 | Prior-year 10-K F-29: same row, same figures as that year's interest | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 5 | Prior-year 10-K F-28: interest on lease liabilities | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 6 | Cash-flow statement (F-8), financing activities: first line | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 7 | Financing line | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 8 | Financing line | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 9 | Financing line | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 10 | The four 2025 financing lines add to this total with no finance-lease line, so the [n] the lease note calls a financing outflow is not in financing activities | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.