4.03 Two referencing slips in the MD&A: a legal-proceedings cross-reference to the wrong note and a footnote marker pointing to the wrong footnote
Company G · a US-listed specialty pharmaceutical company · Drafting slip
In brief
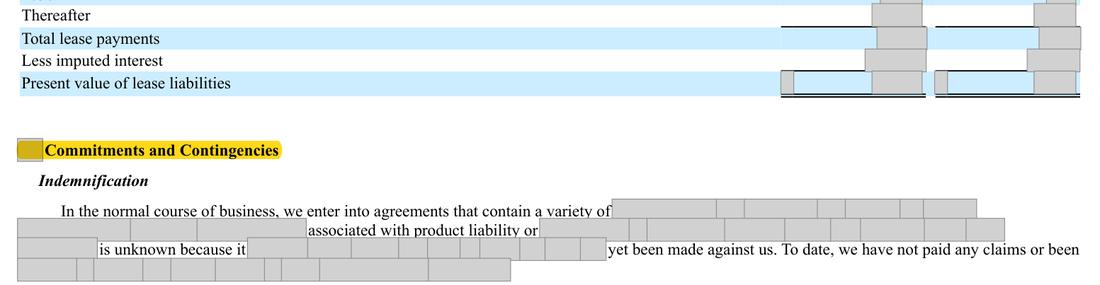
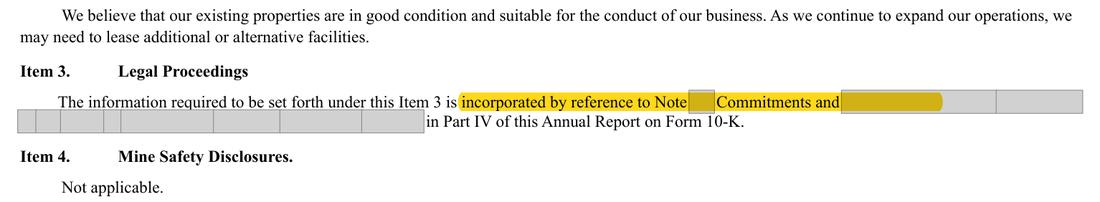
The MD&A sends readers to 'Note 10, Commitments and Contingencies-Legal Proceedings' for the [product] antitrust litigation, but commitments and contingencies is Note 13; Note 10 is a different note, and Item 3 and every other legal-proceedings cross-reference in the filing correctly say Note 13 (Note 10 is the accrued liabilities note). In the revenue table, [product]'s 2024 change column carries footnote marker (1), which is the footnote about the [product] divestment; it should carry (2), 'Comparison to prior period is not meaningful'.
The evidence, as filed
4 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Cross-reference to 'Note 10' for legal proceedings; [product] 2024 change marked 'N/A(1)' with footnote (1) about [product]. | 'Note 13, Commitments and Contingencies-Legal Proceedings'; [product] 2024 change marked 'N/A(2)'. |
Why it matters
A reader following the cross-reference lands on the wrong note; the footnote marker misdescribes the [product] comparison.
Exposure
Drafting only.
Our workings
the commitments and contingencies note is headed '[n]. Commitments and Contingencies' in the financial statements, and the prior-year MD&A used Note 13 in the same sentence, so the 'Note 10' reference is a new slip. In the revenue table, [product] carries superscript 1 and footnote (1) explains that its sales run to the [date] divestment; the same marker on [product]'s 2024 change is a mis-keyed (2). Neither slip changes a figure.
Management’s best defense, and our reply
Management would say both are obvious typographical slips that no reader would rely on, and that Item 3 and the other legal-proceedings cross-references give the right note. That is accepted, which is why they are listed only as drafting slips. They still belong in the pre-filing proof-read because the legal-proceedings note is where the antitrust settlements are explained.
The fix
- Change 'Note 10' to 'Note 13' in the trends section, and the [product] 2024 marker from (1) to (2).
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | MD&A cross-reference gives Note 10 for legal proceedings | Document | Form 10-K 2025, page 91 |
| 2 | In the financial statements (page F-29) commitments and contingencies is Note 13 | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 3 | Item 3 cross-refers correctly to Note 13 | Document | Form 10-K 2025, page 77 |
| 4 | [product] row: the 2024 change beside [n] is marked N/A(1) | Document | Form 10-K 2025, page 92 |
| 5 | Footnote (1) concerns [product], not [product] | Document | Form 10-K 2025, page 92 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.