1.09 Income tax note: two 2023 figures in the rate reconciliation disagree with the rest of the same note, in both [n]-Ks
Company G · a US-listed specialty pharmaceutical company · SEC-style question
In brief
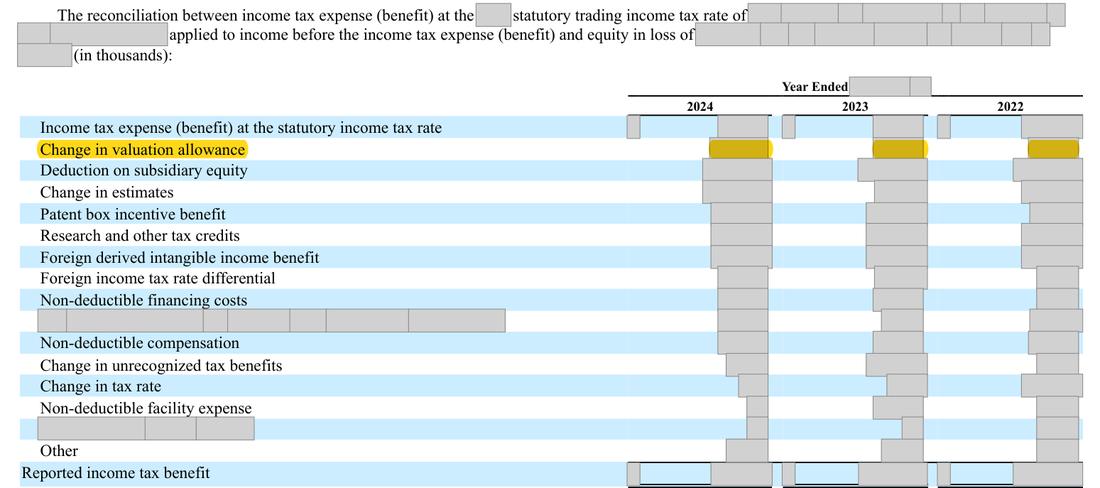
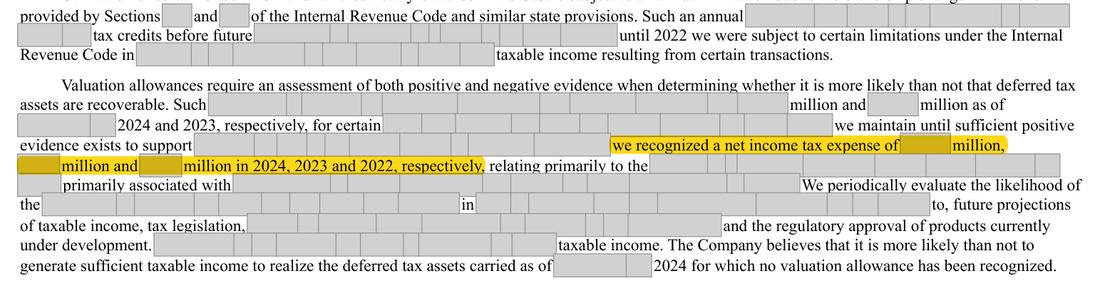
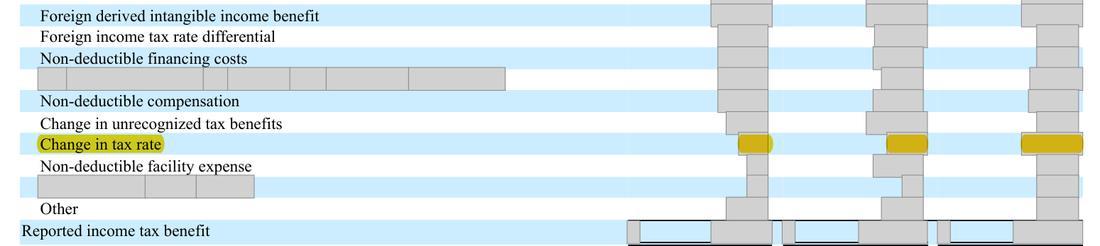
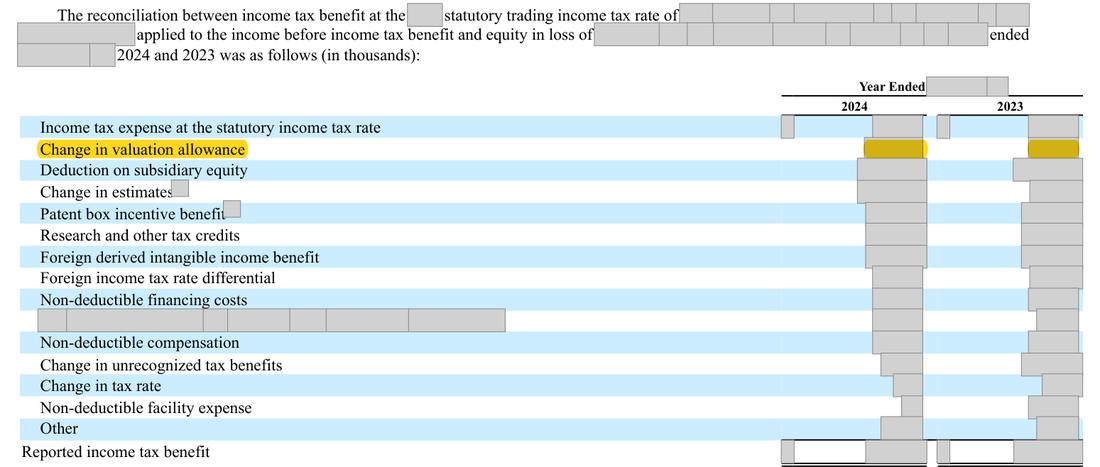
The rate reconciliation shows a 2023 'change in valuation allowance' of [n], but the narrative on the next page says the valuation allowance cost [amount] in 2023. The 2023 'change in tax rate' line is ([n]), while the tax-expense table gives ([n]) for the same effect. For 2024 and 2022 the matching figures agree, and both [n]-Ks print the 2023 pairs unchanged.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
2023: rate reconciliation 'Change in valuation allowance' [n] against '[amount]' in the valuation-allowance narrative; rate reconciliation 'Change in tax rate' ([n]) against 'Total deferred, change in tax rates' ([n]) | One figure for each 2023 effect throughout the note, or a short statement of why the narrative and the deferred-tax table use a different basis from the rate reconciliation |
The rule
Exchange Act Rule 12b-20
In addition to the information expressly required to be included in a statement or report, there shall be added such further material information, if any, as may be necessary to make the required statements, in the light of the circumstances under which they are made not misleading.
Version: Text in force at the date of this review · Source: 17 CFR 240.12b-20 (eCFR, as in force 2024-2025)
Regulation S-X Rule 4-08(h)(2) (reconciliation of reported income tax to the statutory rate)
Where the reporting person is a foreign entity, the income tax rate in that person's country of domicile should normally be used in making the above computation
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.4-08(h)(2) (eCFR, as amended)
Why it applies here. the 2023 narrative figure appears to have been taken from Schedule II while 2024 and 2022 follow the rate reconciliation, so the sentence mixes bases across its three years; the tax-rate line may include a current-tax effect the deferred table does not. Neither difference is large ([n] / [n] = 0.24% of fiscal 2024 pre-tax income), but both sit in the audited note and were carried into the current 10-K without comment.
Why it matters
A reader tracing the valuation-allowance charge or the effect of rate changes across years gets two different 2023 figures from the same audited note, with nothing to say which basis each uses.
Exposure
No penalty; at most a staff comment asking which figure is right or for a clarifying sentence in the next filing.
Our workings
the prior-year 10-K's rate reconciliation gives the 2023 valuation-allowance effect as [n] and the 2023 tax-rate effect as ([n]) thousand; the same note's narrative says a net income tax expense of [amount] was recognized for 2023 from the valuation allowance, and its tax-expense table gives the deferred effect of 2023 rate changes as ([n]). The fiscal 2025 10-K repeats all four figures in its 2023 column. For 2024 ([n] against [amount]; [n] against [n]) and 2022 ([n] against [amount]) the pairs agree.
[n] - [n] = [n]; [n] - [n] = [n]. Schedule II shows 2023 valuation-allowance additions charged to costs and expenses of [n] and deductions of ([n]); [n] - [n] = [n], which rounds to the narrative's [amount].
| Effect (2023) | Rate reconciliation | Elsewhere in the note | Difference |
|---|---|---|---|
| Valuation allowance | [n] | [amount]: [n] x [n] = [n] | [n] - [n] = [n] |
| Tax-rate change | ([n]) | ([n]) | [n] - [n] = [n] |
| Schedule II basis for the narrative | additions [n], deductions ([n]) | [n] - [n] = [n] | rounds to [amount] |
| Same pairs in 2024 / 2022 | [n] / [n] | [amount] / [amount] | agree |
| Size | [n] | fiscal 2024 pre-tax income [n] | [n] / [n] = 0.24% |
Management’s best defense, and our reply
The figures may answer different questions: the reconciliation line is the effect of the valuation-allowance change on the 2023 rate reconciliation, while the narrative may be the Schedule II charge net of deductions, and the tax-rate line may include a current-tax effect that the deferred table excludes. Both differences are small, sit in the earliest year presented and were audited. However, the same narrative sentence uses the reconciliation basis for 2024 and 2022, so 2023 alone departs without explanation, and the current 10-K reprints the pair unchanged; only management can say which basis is intended.
The fix
- Confirm the 2023 figures and, where a different basis is intended, say so, e.g. 'The 2023 amount is the Schedule II charge net of deductions; the rate reconciliation shows [n].' The 2023 column drops out of the fiscal 2026 10-K, so the check is on the basis used going forward.
Question for the company
For 2023, which amount is the tax expense from the change in valuation allowance, [n] in the rate reconciliation or [amount] in the narrative, and why does the 2023 'change in tax rate' reconciling item ([n]) differ from the deferred effect of rate changes ([n]) in the tax-expense table?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Prior-year 10-K rate reconciliation (F-48): 2023 valuation-allowance effect [n]; 2024 [n] and 2022 [n] | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 2 | Prior-year 10-K narrative (F-49): 2023 valuation-allowance charge given as [amount]; 2024 and 2022 agree to the reconciliation | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 3 | Prior-year 10-K rate reconciliation (F-48): 2023 tax-rate effect ([n]) | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 4 | Prior-year 10-K tax-expense table (F-47): 2023 deferred effect of rate changes ([n]) | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 5 | Schedule II (F-51), 2023 row: additions charged [n] and deductions ([n]), the likely source of the [amount] | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 6 | Fiscal 2025 10-K (F-45) repeats the 2023 valuation-allowance effect of [n] | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 7 | Fiscal 2025 10-K (F-47) repeats the [amount] narrative for 2023 | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 8 | Fiscal 2025 10-K (F-45) repeats the 2023 tax-rate line ([n]) | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 9 | Fiscal 2025 10-K (F-43) repeats the 2023 deferred rate-change total ([n]) | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.