1.08 Cash-flow statement: no non-cash investing information, although a [amount] milestone was capitalized in 2024 and paid only in 2025
Company G · a US-listed specialty pharmaceutical company · SEC-style question
In brief
In [date] the company capitalized a [amount] regulatory milestone for [product] as an intangible asset, yet the 2024 cash-flow statement shows no payment for intangible assets and the accrued liabilities note shows 'Accrued milestones' of [n] at that year-end. The fiscal 2025 MD&A attributes part of the 2025 intangible outflow to the [product] milestone. Capital spending unpaid at year-end ('Accrued construction-in-progress', [n] and [n]) is not described either, and neither 10-K gives any non-cash investing information, although both give it for leases.
The evidence, as filed
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
No non-cash investing disclosure in either 10-K: an intangible asset of [amount] recognized in 2024 against an accrued liability (Accrued milestones [n]; 2024 'Acquisition of intangible assets' nil) and paid within the 2025 outflow of ([n]); accrued construction-in-progress of [n] (2024) and [n] (2025) not described | A supplemental note to the cash-flow statement, or a sentence in the notes, listing for each year presented the non-cash investing activities: intangible assets acquired through accrued milestones and property, plant and equipment purchases included in accrued liabilities (or a statement that they were not significant) |
| What we checked. Cash-flow statements and supplemental lines of both years, Note 3 collaboration milestones, Note 10 accrued liabilities, fiscal 2025 MD&A investing discussion, lease note non-cash table | |
The rule
ASC 230-10-50-3 to 50-6 (non-cash investing and financing activities; paraphrase, the Codification text is copyrighted)
Summary; FASB/IFRS text is copyrighted Classify cash receipts and payments as operating, investing or financing by their nature, present gross flows, include restricted cash, and disclose significant noncash activities.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 230-10-45 and 230-10-50-3 (as amended by ASU 2016-15 and 2016-18); paraphrase
Regulation S-X Rule 4-01(a) (17 CFR 210.4-01(a))
The information required with respect to any statement shall be furnished as a minimum requirement to which shall be added such further material information as is necessary to make the required statements, in the light of the circumstances under which they are made, not misleading.
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.4-01, eCFR text as amended
Why it applies here. the Codification asks for disclosure of investing activities that change recognized assets or liabilities without cash in the period; an asset obtained by incurring a directly related liability is the standard example. Whether these amounts were significant enough to need it is a judgment only management can explain, so this is a question.
Why it matters
A reader of the 2024 statement sees a new [amount] intangible asset with no investing outflow, and a reader of the 2025 statement sees the payment without being told it settles an asset recognized a year earlier; capital spending shown is cash paid, not additions in the year.
Exposure
A question for management; at most a staff request for non-cash investing disclosure in future filings, with no restatement indicated.
Our workings
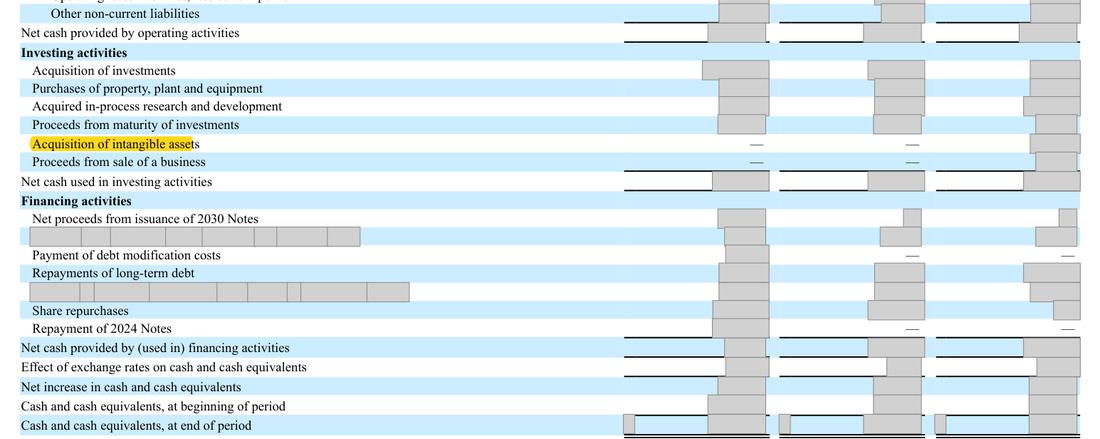
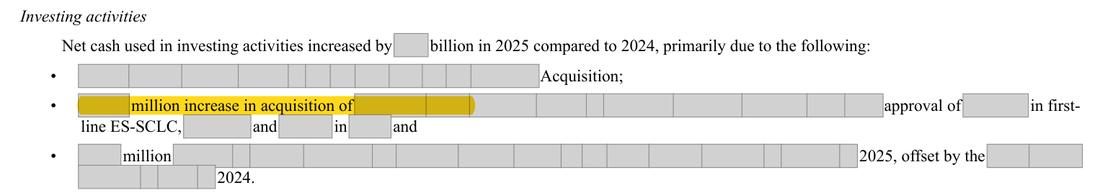
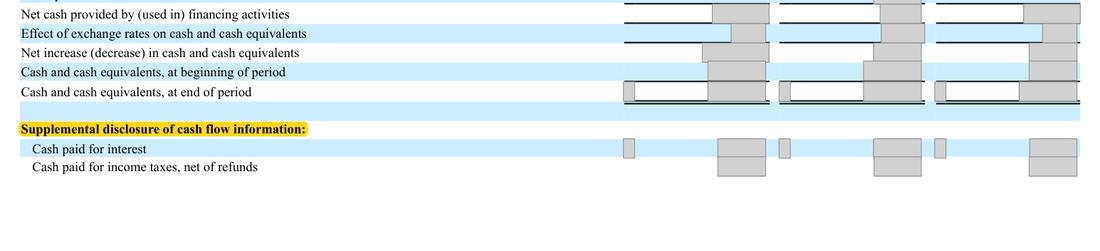
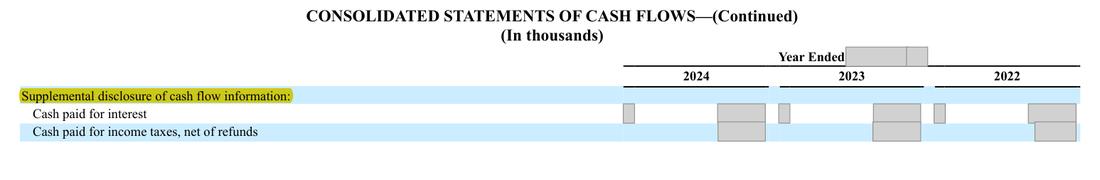
Note 3 of the prior-year 10-K says the [date] FDA approval of [product] triggered 'a regulatory milestone payment of [amount], which was capitalized as an intangible asset'. The 2024 column of the cash-flow statement shows no 'Acquisition of intangible assets', and Note 10 shows 'Accrued milestones' of [n] at [date] against nil a year earlier. The fiscal 2025 MD&A explains the [amount] increase in intangible acquisitions as '[wording masked] ... [product] in [indication]', the approval of [date]. Both [n]-Ks also carry 'Accrued construction-in-progress' ([n] at the 2023, 2024 and 2025 year-ends). The supplemental section of each cash-flow statement gives only cash paid for interest and income taxes; the only non-cash table in either report is the lease note's.
the milestone is [n], 5.32% of 2024 pre-tax income of [n] and 4.92% of 2024 net investing outflow of [n]; accrued construction-in-progress rose by [n] in 2024 and [n] in 2025, and the 2025 year-end balance of [n] is 2.28% of the absolute 2025 pre-tax loss.
| Measure | Computation | Result |
|---|---|---|
| [product] milestone in thousands | [amount] x [n] | [n] |
| Share of 2024 pre-tax income | [n] / [n] | 5.32% |
| Share of 2024 net investing outflow | [n] / [n] | 4.92% |
| Accrued construction-in-progress movement 2024 | [n] - [n] | [n] |
| Accrued construction-in-progress movement 2025 | [n] - [n] | [n] |
| 2025 year-end accrued construction-in-progress vs pre-tax loss | [n] / [n] | 2.28% |
Management’s best defense, and our reply
Management could argue that the Codification asks only for significant non-cash activities, and that a milestone equal to 5.32% of 2024 pre-tax income and accrued construction costs of [n] and [n] are not significant enough for a separate schedule. It could add that Note 3 says the milestone was capitalized, Note 10 shows the 'Accrued milestones' and 'Accrued construction-in-progress' lines, and the fiscal 2025 MD&A explains the milestone payments, so a careful reader can piece the position together. That position is tenable, which is why this is a question. However, no note says the milestone was unpaid at the 2024 year-end, the 2024 column shows no intangible purchase while the balance sheet gained the asset, and the company already gives non-cash information for leases, so leaving out the investing items is a choice that should be explained.
The fix
- Add under the supplemental disclosures: 'Non-cash investing activities: intangible assets acquired and included in accrued liabilities, [amount] (2024); property, plant and equipment purchases included in accrued liabilities, [n] and [n] (2025 and 2024).'
Question for the company
Was the [amount] [product] milestone capitalized in [date] unpaid at [date] and paid in 2025, what property, plant and equipment additions were unpaid at each year-end, and was disclosure of these non-cash investing activities considered and judged not significant?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Prior-year Note 3: the [product] milestone was capitalized as an intangible asset in 2024 | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 2 | Prior-year cash-flow statement: no cash paid for intangible assets in 2024 (the [n] is the 2022 column) | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 3 | 2024 net investing outflow used as a scale measure | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 4 | Prior-year Note 10: milestones accrued but unpaid at [date], nil a year earlier | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 5 | Prior-year Note 10: capital spending unpaid at the 2024 and 2023 year-ends | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 6 | 2024 pre-tax income, the materiality benchmark for the prior year | Document | Form 10-K 2024 (prior year), financial-statement pages (printed F-n; see folios) |
| 7 | Fiscal 2025 MD&A: the 2025 intangible outflow includes the [product] milestone recognized in 2024 | Document | Form 10-K 2025, page 97 |
| 8 | Fiscal 2025 cash-flow statement: the payment falls in 2025; the 2024 comparative still shows nil | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 9 | Fiscal 2025 Note 10: capital spending unpaid at the 2025 year-end | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 10 | Fiscal 2025 Note 10: the accrued milestones were settled during 2025 | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 11 | 2025 pre-tax loss used as the scale measure for the current year | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Supplemental disclosure of cash flow information:
- What is missing
- any non-cash investing information for 2025 or the 2024 comparative: capital spending included in accrued liabilities and the 2024 intangible acquired through an accrued milestone
- Pages looked at
- p.97 (MD&A cash flows), [n] (cash flows), 139-140 (Notes 8-10), 147 (lease note)
- Result
- 'non-cash' phrases hit only the operating add-back captions on financial-statement pages (printed F-n; see folios), the revolver covenant on financial-statement pages (printed F-n; see folios) and the lease note's 'Non-cash operating activities' on financial-statement pages (printed F-n; see folios), none an investing disclosure; 'included in accrued liabilities' hits only financial-statement pages (printed F-n; see folios) (where finance lease liabilities sit); 'unpaid' hits only 'accrued and unpaid interest' in the debt passages (p.70, 99-100, 143-145); 'non-cash investing', 'noncash', 'capital expenditures included' and 'not yet paid' have no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.