1.07 Income taxes paid: an undivided 'Other' foreign line of [n], over four times the 5% jurisdiction threshold
Company G · a US-listed specialty pharmaceutical company · SEC-style question
In brief
In its first year under the new income-tax disclosure rules, the Company splits [n] of income taxes paid into [country], United States - federal and a single 'Other' foreign line of [n], 22.7% of the total. The rules ask for any individual jurisdiction that makes up 5% or more of total taxes paid ([n] here) to be shown on its own. The note gives no breakdown of 'Other', although the same note shows the United Kingdom, [country] and [country] separately elsewhere and United Kingdom current tax of [n].
The evidence, as filed
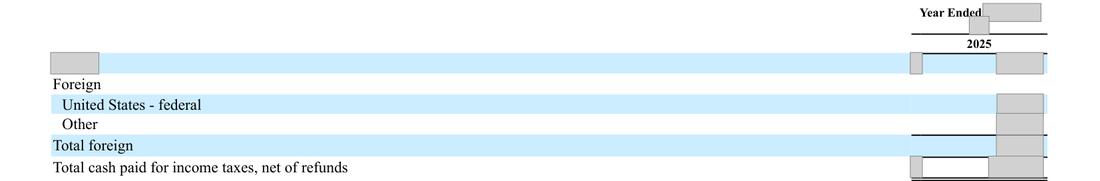
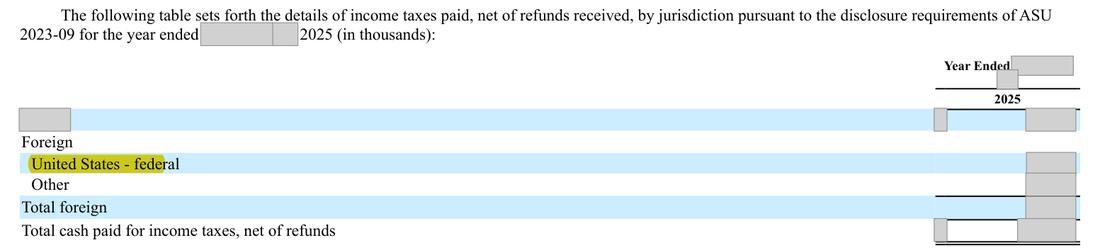
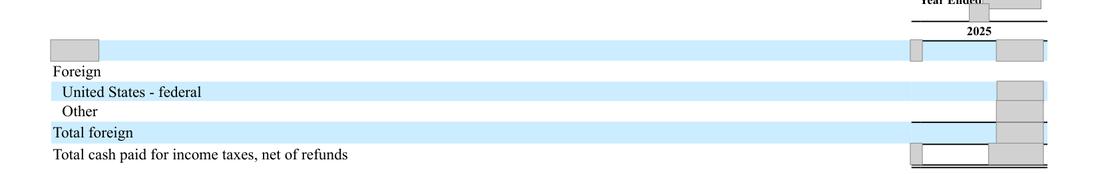
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Income taxes paid, 2025: [country] [n]; United States - federal [n]; Other [n]; total [n]. 'Other' equals 22.7% of the total, with no jurisdiction named | Each jurisdiction whose taxes paid are 5% or more of the total ([n]) shown separately, or a statement that no single jurisdiction inside 'Other' reaches that level |
The rule
FASB ASC 740-10-50-22 to 50-23
Summary; FASB/IFRS text is copyrighted Disclose income taxes paid (net of refunds) by federal, state and foreign, and by any jurisdiction at least 5% of total; split pre-tax income domestic/foreign.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 740-10-50-22 to 50-23 (as amended by ASU 2023-09); paraphrase, the Codification text is licensed
Regulation S-X Rule 4-01(a)(1)
Financial statements filed with the Commission which are not prepared in accordance with generally accepted accounting principles will be presumed to be misleading or inaccurate, despite footnote or other disclosures, unless the Commission has otherwise provided.
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.4-01(a)(1), eCFR text
Why it applies here. the amended Codification asks for income taxes paid to be split between federal (national), state and foreign, and for each individual jurisdiction at 5% or more of the total to be shown. A line this large may hold one or more such jurisdictions; the United Kingdom, with current tax above the threshold, is the most likely. Current tax expense is not cash paid, so the point cannot be settled from the report and is put as a question.
Why it matters
Readers cannot see where outside [country] and the United States the Company pays cash tax; the SEC staff has made the new income-tax disclosures a review focus.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, income taxes drew 23 of the 1,774 numbered comments (1.3%): topic 17 of 25 by frequency.
Exposure
A question for management; if a jurisdiction inside 'Other' reaches 5% of taxes paid, the realistic outcome is a staff comment and a future-filings undertaking. No figure in the statements is affected.
Our workings
the table on F-46 shows income taxes paid, net of refunds, of [n] in [country], [n] to the United States federal government and [n] in 'Other' foreign jurisdictions, totalling [n], which agrees to the cash-flow statement. The tax expense table on F-43 shows United Kingdom current tax of [n] and 'Other' current tax of [n], and the rate reconciliation on F-44 itemises the United Kingdom, [country] and [country].
the 5% threshold is [n]; 'Other' is 22.7% of total taxes paid and [n] times the threshold (workings).
| Measure | Computation | Result |
|---|---|---|
| 5% threshold of total taxes paid | [n] x 5% = [n] | [n] |
| Share of 'Other' in total taxes paid | [n] / [n] = 22.7% | 22.7% |
| 'Other' as a multiple of the threshold | [n] / [n] = [n] | [n] times |
| United Kingdom current tax against the threshold | [n] - [n] = [n] | above the threshold |
| Foreign subtotal | [n] + [n] = [n] | agrees to the printed total foreign |
| Total | [n] + [n] = [n] | agrees to the printed total |
Management’s best defense, and our reply
Management could argue that taxes paid in each country inside 'Other' are individually below [n], for example because United Kingdom payments were reduced by refunds or by losses surrendered within the group, so no further split is required. It could add that current tax expense is an accrual and does not show what was paid in the year. That position is tenable, which is why this is a question. However, the line is [n] times the threshold and the note itself shows three foreign jurisdictions of size in the rate reconciliation, so a short statement confirming that no single country reaches 5% would remove the doubt.
The fix
- Show each jurisdiction at or above 5% of total taxes paid on its own line (for example 'United Kingdom $[x]'), or add: 'No individual jurisdiction included in Other represents 5% or more of total income taxes paid.'
Question for the company
Which jurisdictions make up the [n] 'Other' foreign taxes paid in 2025, and does any of them (for example the United Kingdom, [country] or [country]) reach 5% of total taxes paid, [n]?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Taxes paid in [country], the domestic jurisdiction | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 2 | The only foreign jurisdiction named | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 3 | All other foreign taxes paid in one line | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 4 | Foreign subtotal | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 5 | Total taxes paid, the base for the 5% threshold | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 6 | United Kingdom current tax expense in 2025 is above the threshold | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 7 | Other foreign current tax expense in 2025 | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 8 | The rate reconciliation itemises [country], so jurisdiction data exist | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.