1.06 Cash-flow statement: the [amount] 'proceeds from sale of an asset' is not reconciled to the [amount] [product] price given in the third-quarter Form 10-Q, and no gain or loss is stated
Company G · a US-listed specialty pharmaceutical company · SEC-style question
In brief
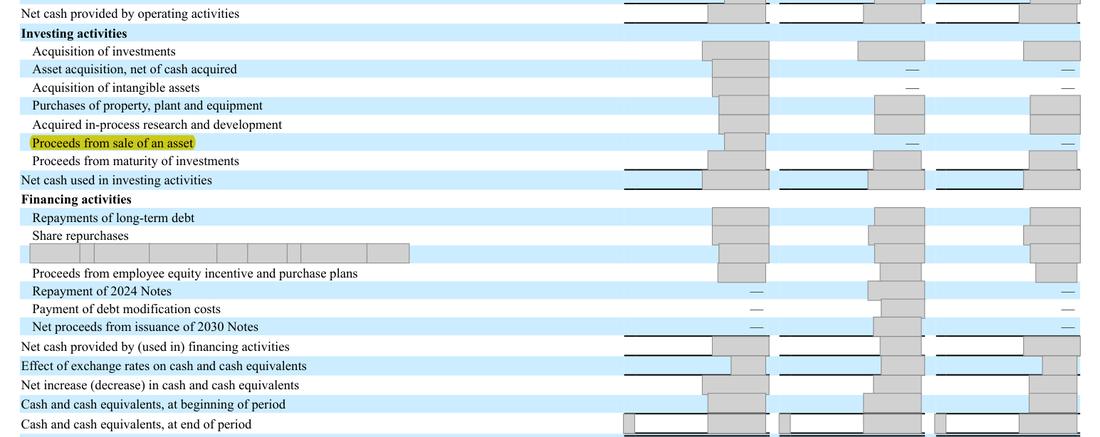
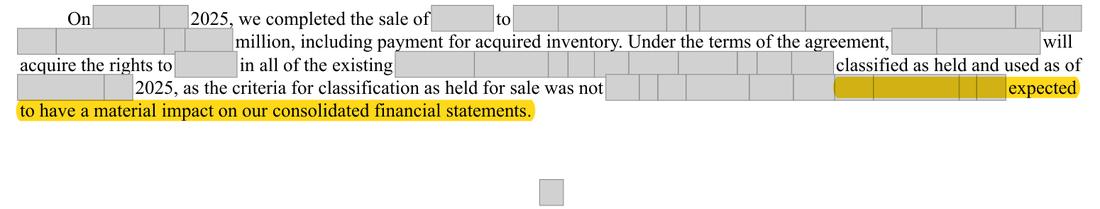
The 2025 cash-flow statement shows a new investing inflow, 'Proceeds from sale of an asset', of [n]. This 10-K says only that the sale of [product] to [buyer] was completed on [date]. The company's Form 10-Q for the quarter to [date] gave the price: total cash consideration of [amount] including inventory, with no material impact expected. The 10-K drops that price, does not tie it to the [n] line (a gap of [n], presumably the inventory element), and does not say whether a gain or loss arose. The inflow equals 4.49% of the pre-tax loss.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
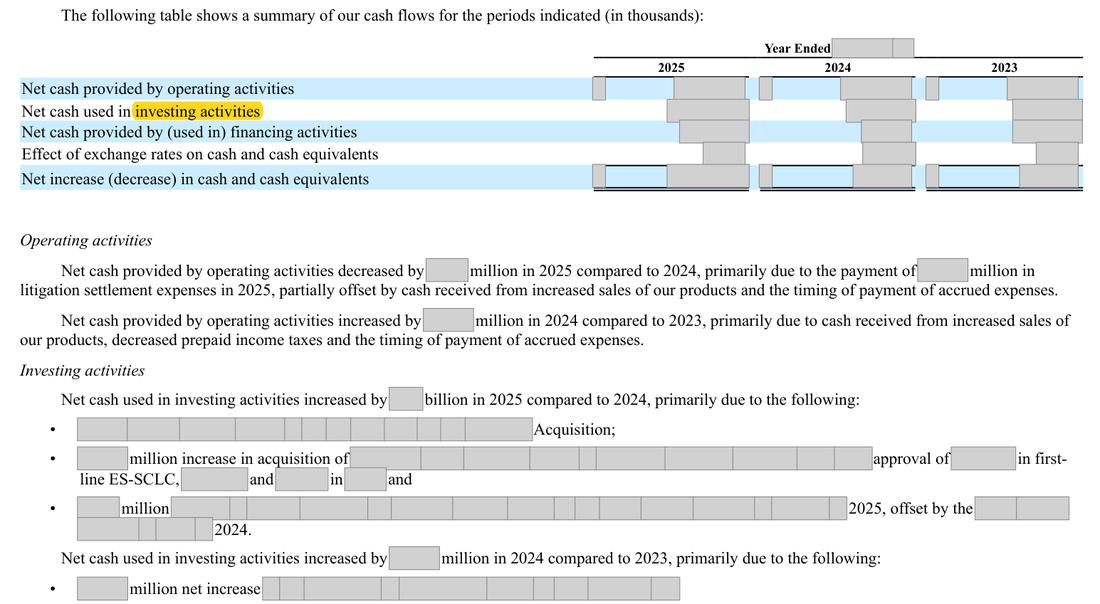
Investing line 'Proceeds from sale of an asset' [n] (F-8); [product] sale completed [date] described in Item 1 (p.8, p.85) and Note 18 (F-38) without a price; the Form 10-Q for the third quarter of 2025 gave total cash consideration of [amount] including inventory; the 10-K states no consideration, no reconciliation to the cash-flow line and no gain or loss | One sentence in the notes (or the MD&A investing discussion) giving the [product] consideration as already reported in the Form 10-Q, how it splits between the investing line and the inventory element, and the gain or loss with its caption, or a statement that no material gain or loss arose |
The rule
Regulation S-X Rule 4-01(a) (17 CFR 210.4-01(a))
The information required with respect to any statement shall be furnished as a minimum requirement to which shall be added such further material information as is necessary to make the required statements, in the light of the circumstances under which they are made, not misleading.
Version: Text as amended up to [date] · Source: Regulation S-X, 17 CFR 210.4-01, eCFR text as amended to [date]
Why it applies here. the identity of the asset is now answered by the company's earlier filing; what remains open is why the annual report omits the price it gave in the quarter, how the [n] splits across the cash-flow statement, and whether a gain or loss arose. If any gain or loss was immaterial, as the 10-Q expected, no further note is needed, so this is a question rather than a finding.
Why it matters
A reader of the 10-K alone cannot tie the investing inflow to the [product] sale, see the price the company reported in the quarter, or see whether a gain or loss arose; the staff could ask for the nature of the transaction.
Exposure
A question for management; at most a staff request for the nature of the sale, with no restatement indicated.
Our workings
the 2025 column of the cash-flow statement (F-8) shows 'Proceeds from sale of an asset' of [n], with no amount in 2024 or 2023. This 10-K discloses one asset sale in 2025: the footnote to the trademark list says the sale of [product] to [buyer] was completed on [date], Item 1 says [product] was divested in [date], and the revenue note (F-38) says the divestiture was completed in [date]. None of these passages gives the consideration, and the MD&A investing paragraph explains the [acquired business] outflow, intangible milestones and IPR&D payments but not this inflow. A whole-report search finds no gain or loss on a sale and no other mention of the amount. The company's own Form 10-Q for the quarter to [date] (subsequent-events note, filed [date]) identifies the sale as [product], for total cash consideration of [amount] including payment for acquired inventory, and says the divestiture is not expected to have a material impact on the consolidated financial statements.
[n] - [n] = [n], which would fit an inventory element reported outside investing activities, but the 10-K does not say so; [n] / [n] = 4.49% of the pre-tax loss.
| Measure | Computation | Result |
|---|---|---|
| Share of pre-tax loss | [n] / [n] | 4.49% |
| Form 10-Q price less investing inflow | [amount] = [n]; [n] - [n] | [n] |
Management’s best defense, and our reply
Management could argue that the sale is disclosed in three places in this 10-K, that the price was published in the third-quarter Form 10-Q, and that the inflow is shown on its own captioned line. It could add that the 10-Q already said the divestiture was expected to have no material impact, that the proceeds are under 5% of the pre-tax loss and that [product] sales were [n] in 2025, so no disposal note was needed. That position is tenable, which is why this is a question; however, the annual report is read on its own, it does not repeat the price or link the [n] inflow to [product], and it never says whether a gain or loss arose or where it was recorded.
The fix
- Add one sentence in the notes or the MD&A investing discussion: 'On [date] we sold [product] to [buyer] for total cash consideration of [amount], including $[x] million for inventory, recognizing a gain (loss) of $[y] million in [caption].'
Question for the company
Is the [n] 'Proceeds from sale of an asset' the non-inventory part of the [amount] [product] consideration reported in the third-quarter Form 10-Q, and where is the balance of [n] shown; what gain or loss, if any, was recognized and in which caption; and was omitting the price from the 10-K a materiality judgment?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The 2025 investing inflow (F-8), with no description on the statement | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 2 | Pre-tax loss used as the materiality benchmark | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 3 | The report discloses the [product] sale and its completion date, but no consideration | Document | Form 10-K 2025, page 8 |
| 4 | Item 1 describes the divestiture without consideration or gain or loss | Document | Form 10-K 2025, page 85 |
| 5 | Revenue note (F-38) footnote; the only mention of the sale in the financial statements | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 6 | MD&A explains the other 2025 investing movements but says nothing about the asset-sale inflow | Document | Form 10-K 2025, page 97 |
| 7 | [product] product sales 2025 (F-38), the scale of the business sold | Document | Form 10-K 2025, financial-statement pages (printed F-n; see folios) |
| 8 | Form 10-Q for the quarter to [date]: the company's own materiality view of the [product] sale | Document | |
| 9 | Form 10-Q for the quarter to [date], subsequent-events note: the asset sold in the fourth quarter and its date | Document | |
| 10 | Form 10-Q: total cash consideration, which includes inventory and so is not the same as the investing-cash line | Document | |
| 11 | This 10-K, Item 1: names the divestment but gives no price and no link to the cash-flow line | Document | Form 10-K 2025, page 85 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Investing activities
- What is missing
- any explanation of the [n] inflow from the sale of an asset, or of the consideration for the [product] divestiture
- Pages looked at
- p.8, [n] ([product] passages), p.97 (MD&A cash flows), financial-statement pages (printed F-n; see folios) (cash-flow statement), p.139-140 (property, plant and equipment; goodwill and intangible assets)
- Result
- 'sale of an asset', 'proceeds from sale' and '[n]' hit only financial-statement pages (printed F-n; see folios), the cash-flow line itself; '[product]' hits p.8, [n] and 'divest' p.85, [n] and [n]: the trademark footnote, Item 1, the MD&A revenue-table footnote and the revenue note, each describing the divestiture without consideration or gain or loss; '[n]' and 'gain on sale' have no hits.
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- [n]. Revenues
- What is missing
- the consideration received for [product] and any gain or loss on the sale with its income-statement caption
- Pages looked at
- p.8, [n], 139-140, [n]
- Result
- 'sale of an asset', 'proceeds from sale' and '[n]' hit only financial-statement pages (printed F-n; see folios), the cash-flow line itself; '[product]' hits p.8, [n] and 'divest' p.85, [n] and [n]: the trademark footnote, Item 1, the MD&A revenue-table footnote and the revenue note, each describing the divestiture without consideration or gain or loss; '[n]' and 'gain on sale' have no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.