5.02 The segment policy still gives the decision maker the former title 'President, Chief Executive Officer and Chairperson'
Company F · a US-listed networking equipment company · Drafting slip
In brief
The segment policy names the chief operating decision maker as '[wording masked]', carried over from the prior-year report. The signature page and Item 9B of the same report give that officer's title as Chief Executive Officer and Chairperson, and another officer signs as President.
The evidence, as filed
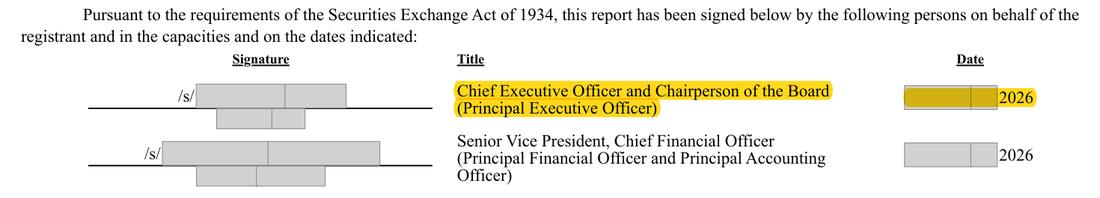
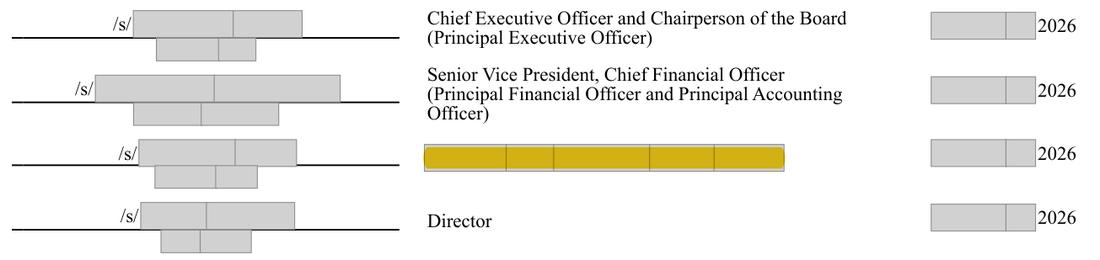
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 1: '[wording masked]' | 'our Chief Executive Officer and Chairperson of the Board', the title in force at the year end |
The rule
ASC 280-10-50-21(c) and 280-10-50-29 (as amended by ASU 2023-07)
Summary; FASB/IFRS text is copyrighted Disclose the CODM's title and position and explain how the CODM uses reported segment profit measures to assess performance and allocate resources.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 280-10-50-21(c) and 280-10-50-29 (as amended by ASU 2023-07); paraphrase
Why it applies here. the policy sentence was not updated. The decision maker is still identifiable, so this is a wording correction only.
Why it matters
None beyond presentation; the decision maker remains identifiable.
Exposure
Drafting correction only.
Our workings
the segment policy uses the title the Chief Executive Officer held when the prior-year report was written (prior-year p.85).
Item 9B and the signature page give the title as Chief Executive Officer and Chairperson, another director signs as President, Chief Technology Officer, and the company's Forms 8-K of June and [date] appointed two other officers President; the 2026 proxy statement says the Chief Executive Officer served as President until [date].
Management’s best defense, and our reply
Management would say the decision maker is plainly the Chief Executive Officer, as it told the SEC staff in 2024, and that only one officer is both Chief Executive Officer and Chairperson, so the extra word misleads nobody. That is right, which is why the point is only a wording correction: the title printed is one that officer no longer holds and two other officers now do.
The fix
- Replace the words with: 'Our chief operating decision maker [wording masked], who reviews financial information presented on a consolidated basis ...'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Segment policy names the decision maker by the former combined title | Document | Form 10-K 2025, page 78 |
| 2 | Item 9B gives the Chief Executive Officer's title without President | Document | Form 10-K 2025, page 96 |
| 3 | Signature page: the principal executive officer signs without the President title | Document | Form 10-K 2025, page 103 |
| 4 | Signature page: another director signs as President | Document | Form 10-K 2025, page 103 |
| 5 | [date] Form 8-K: the Chief Technology Officer made President | Document | |
| 6 | 2026 proxy statement: the Chief Executive Officer held the President title only until [date] | Document | |
| 7 | Prior-year policy carried the same sentence, when the title was correct | Document | Form 10-K 2024 (prior year), page 85 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.