1.08 Accrued liabilities of [amount] are no longer broken down, although last year's breakdown showed an item above the 5% threshold
Company F · a US-listed networking equipment company · SEC-style question
In brief
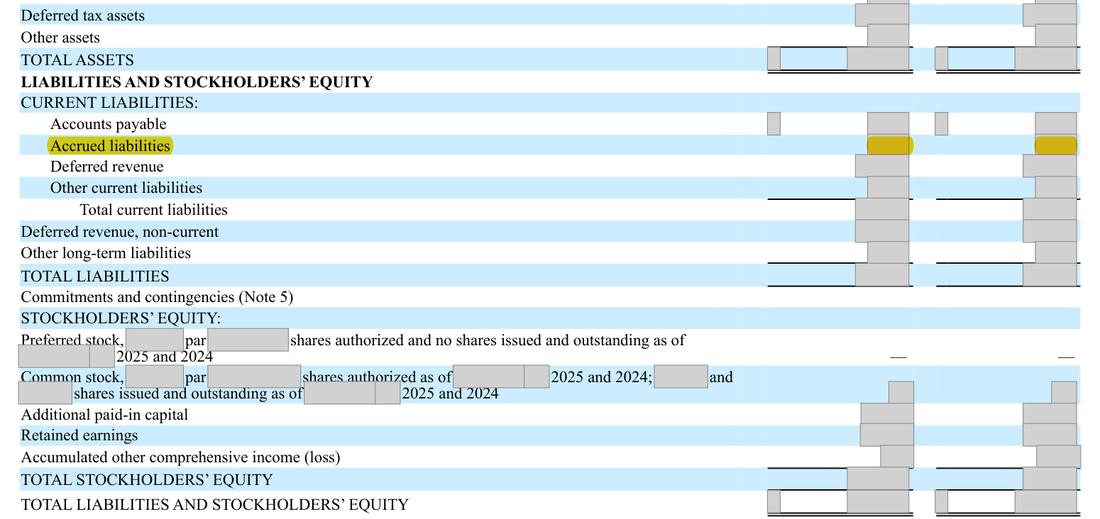
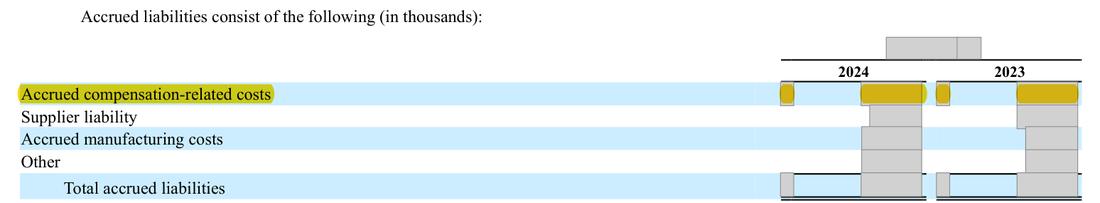
The balance sheet shows accrued liabilities of [amount] (2024: [amount]) as one line, and the financial-statement-details note no longer analyses it. The prior-year Form 10-K broke it down, and its largest item, accrued compensation of [amount] at [date], exceeded 5% of that date's current liabilities. Regulation S-X requires any item above 5% of total current liabilities to be stated separately, so the comparative column at least appears to need the breakdown, and the 2025 composition is unknown.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Accrued liabilities of [amounts] shown as single amounts with no analysis anywhere in the 10-K. | Any component of accrued liabilities above 5% of total current liabilities (2025: [n]; 2024: [n]) stated separately on the balance sheet or in a note, for each balance sheet presented. |
The rule
Regulation S-X Rule 5-02, caption [n] (other current liabilities)
State separately, in the balance sheet or in a note thereto, any item in excess of 5 percent of total current liabilities.
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.5-02
Why it applies here. Regulation S-X Rule 5-02, caption [n], requires any item of other current liabilities above 5% of total current liabilities to be stated separately in the balance sheet or a note; the 2024 comparative, re-presented in this 10-K, carries such an item without it. For 2025 the test cannot be made from the filing.
Why it matters
The comparative balance sheet carries an item above the 5% threshold that is not separately stated in this filing, and readers cannot tell whether the same is true at [date].
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, financial statement presentation drew 254 of the 1,774 numbered comments (14.3%): the second most frequent topic.
Exposure
A question for management; the realistic consequence is restoring the accrued-liabilities table in the next Form 10-K.
Our workings
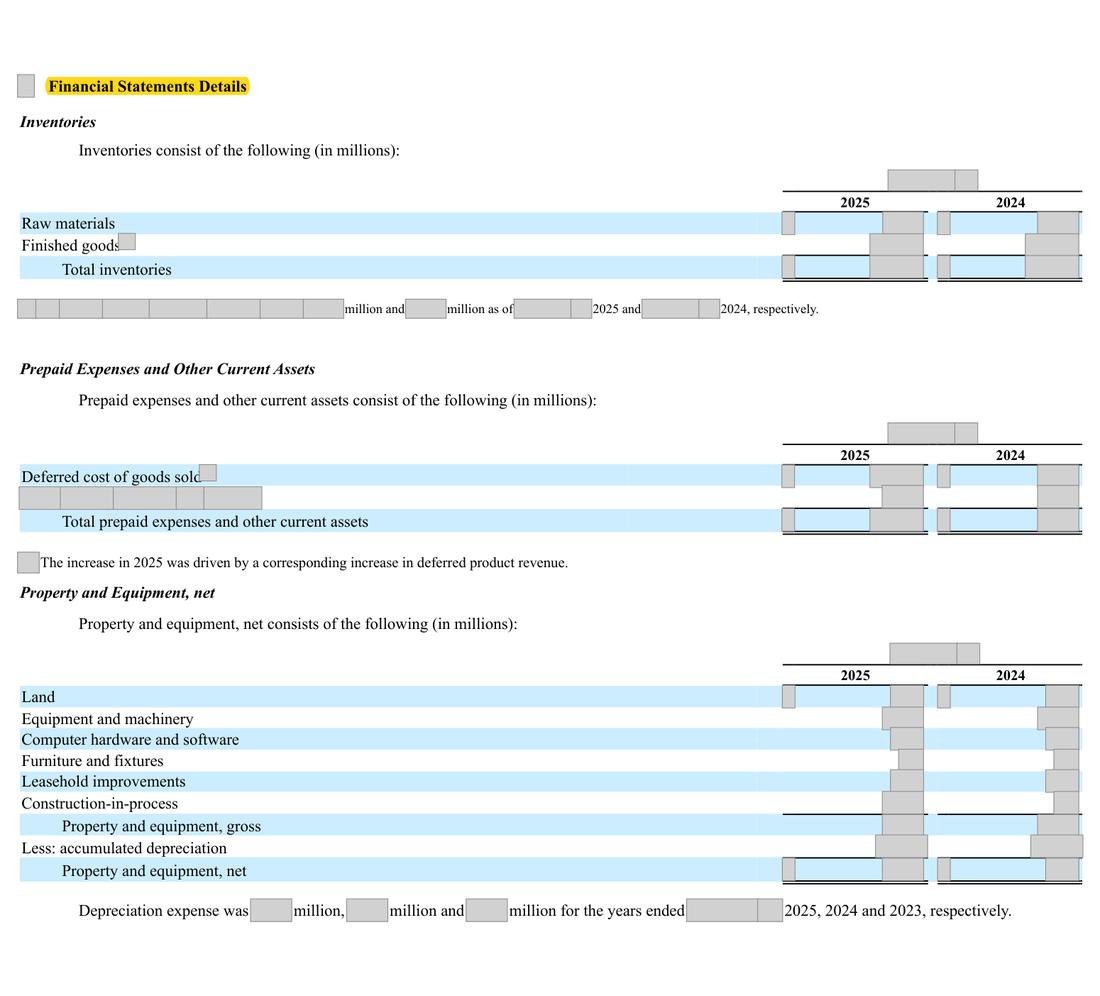
the balance sheet shows accrued liabilities of [n] and [n] and total current liabilities of [n] and [n]. The financial-statement-details note analyses inventories, prepaid expenses, property and equipment, contract liabilities, deferred revenue and other income, but not accrued liabilities. The prior-year Form 10-K analyzed accrued liabilities of [n] into accrued compensation-related costs of [n], supplier liability, accrued manufacturing costs and other.
5% of 2024 current liabilities is [n] x 5% = [n], and accrued compensation of [n] exceeds it; 5% of 2025 current liabilities is [n] x 5% = [n], and the [n] caption is large enough to hold an item above that.
| Line | Arithmetic (USD million) | Source |
|---|---|---|
| 5% threshold, [date] | [n] x 5% = [n] | Balance sheet p.68 |
| 5% threshold, [date] | [n] x 5% = [n] | Balance sheet p.68 |
| Accrued compensation [date] (thousands to millions) | [n] / [n] = [n] > [n] | Form 10-K 2024 (prior year) p.90 (prior 10-K printed thousands) |
| Total accrued liabilities [date] (thousands to millions) | [n] / [n] = [n] = Form 10-K 2025 comparative [n] | Form 10-K 2024 (prior year) p.90; p.68 |
| 2025 caption against its threshold | [n] / [n] = [n] times | computed |
Management’s best defense, and our reply
Management would say that at [date] no single component of accrued liabilities reaches 5% of current liabilities, because current liabilities doubled with deferred revenue. They would say the rule was satisfied for the 2024 balance sheet in the prior 10-K, where the breakdown was given. They would add that the 2024 excess is small, [n] against [n]. The defense is tenable for 2025, which is why this is a question. However, the rule applies to each balance sheet presented, and the 2024 comparative re-presented here carries an item above the threshold without it.
The fix
- Restore the table: 'Accrued liabilities consist of the following: accrued compensation-related costs $[ ]; supplier liability $[ ]; accrued manufacturing costs $[ ]; other $[ ]; total [amount] (2024: [amounts]; total [amount]).'
Question for the company
Does any component of the [amount] of accrued liabilities at [date] exceed [amount]? Why was the breakdown, which showed accrued compensation of [amount] above the [date] threshold of [amount], removed for the comparative year?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Accrued liabilities as one line in both years | Document | Form 10-K 2025, page 68 |
| 2 | Base for the 5% threshold | Document | Form 10-K 2025, page 68 |
| 3 | Prior year: accrued compensation at [date] (thousands) | Document | Form 10-K 2024 (prior year), page 90 |
| 4 | Prior year: total accrued liabilities (thousands) | Document | Form 10-K 2024 (prior year), page 90 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Financial Statements Details
- What is missing
- an analysis of accrued liabilities (accrued compensation, supplier liability, accrued manufacturing costs, other)
- Pages looked at
- p.68 (balance sheet), 77-98 (notes), 56-66 (MD&A)
- Result
- 'accrued compensation', 'compensation-related' and 'accrued manufacturing' have no hits. 'accrued liabilities' hits only the balance-sheet line and the fair-value policy. 'supplier liability' hits risk factors and MD&A narrative on charges (p.18, [n]) and the critical audit matter; the plural 'supplier liabilities' appears only in risk factors, the critical-estimate discussion and the accounting policy (p.19, [n]); none gives a balance.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.