4.08 Inventory reserves doubled to [amount] in 2025; neither the note nor management's discussion says why
Company E · a US-listed home furnishings retailer · SEC-style question
In brief
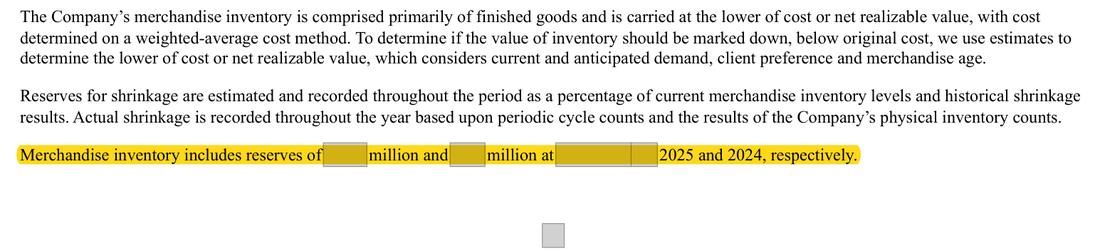
Note 2 shows merchandise inventory reserves of [amount] at the end of 2025 against [amount] a year earlier, a doubling while inventory itself grew [n]%. The increase of [amount] is 9.5% of income before taxes. The management's discussion and analysis (MD&A) gross-margin explanation does not mention inventory reserves at all, and critical accounting estimates cover only long-lived assets.
The evidence, as filed
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
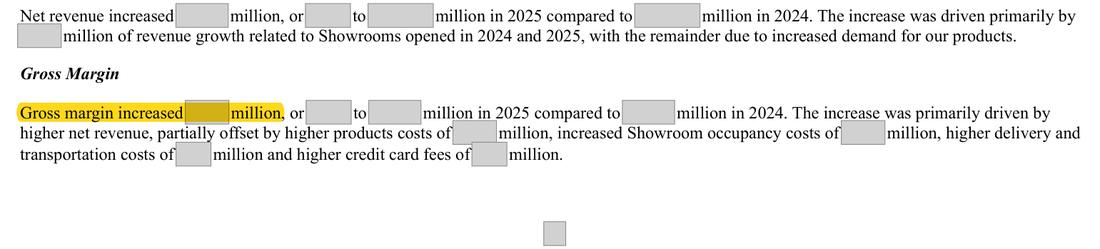
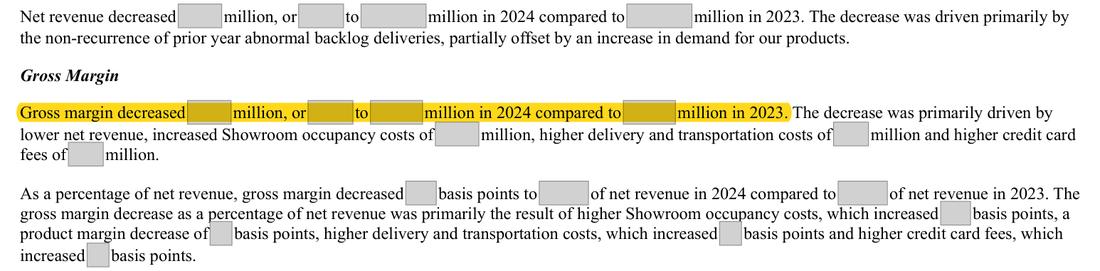
Reserves of [amount] (2025) and [amount] (2024) are stated in one sentence in Note 2 with no cause given. MD&A attributes the 2025 gross-margin change to product costs of [amount], Showroom occupancy of [amount], delivery and credit card fees, and the [n] basis point margin fall to occupancy and delivery costs. | An explanation of what drove the reserve build (lower of cost or net realizable value write-downs, shrink, or another component), how much was charged to cost of goods sold, and, if material, its effect on gross margin in MD&A. |
| What we checked. Note 2 inventory policy, the MD&A gross-margin discussion, critical accounting estimates, the prior-year 10-K and the balance sheet | |
The rule
Regulation S-K Item 303(b)(2)(i)
In addition, describe any other significant components of revenues or expenses that, in the registrant's judgment, would be material to an understanding of the registrant's results of operations.
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.303(b)(2)(i), eCFR text
Regulation S-K Item 303(b)(2)(ii)
If the registrant knows of events that are reasonably likely to cause a material change in the relationship between costs and revenues (such as known or reasonably likely future increases in costs of labor or materials or price increases or inventory adjustments), the change in the relationship must be disclosed.
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.303(b)(2)(ii), eCFR text
Why it applies here. A material change in an estimate that bears on gross margin is not explained anywhere in the 10-K
Why it matters
If the build was charged to cost of goods sold, readers of MD&A are given an incomplete account of why gross margin fell, and a material change in an estimate is not visible anywhere in the 10-K.
Exposure
None while the point is a question. If the build was a material charge, a Securities and Exchange Commission (SEC) staff comment on MD&A results asking the company to quantify it, answered by a future-filings undertaking, is the realistic outcome.
Our workings
Note 2 states that merchandise inventory includes reserves of [amounts] at the 2025 and 2024 year ends; the prior-year 10-K gave [amounts]. Merchandise inventory, net rose from [n] to [n]. MD&A explains the 2025 gross-margin change through higher product costs, Showroom occupancy, delivery and credit card fees, and the [n] basis point fall in the margin rate through occupancy and delivery costs; it does not mention inventory reserves. The critical accounting estimates section covers only long-lived assets.
the reserve rose by [n], 9.5% of income before taxes of [n] and [n] basis points of net revenue of [n], against a [n] rise in 2024; net inventory grew [n]%.
Item 303(b)(2)(i) of Regulation S-K asks MD&A to describe significant components of revenues or expenses material to an understanding of results, and Item 303(b)(2)(ii) names inventory adjustments among the known events reasonably likely to cause a material change in the relationship between costs and revenues, which must then be disclosed. A reserve build of this size, if charged to cost of goods sold, is larger than the whole [n] basis point margin fall that MD&A explains. It may instead sit inside the higher product costs figure, or reflect a reclassification or growth in aged stock; only management knows which, so this is put as a question.
| Measure | Working | Result |
|---|---|---|
| Increase in inventory reserves in 2025, USD thousand | ([n] - [n]) x [n] = [n] | [n] |
| Increase as a share of 2025 income before taxes | [n] / [n] = 9.5% | 9.5% |
| Increase as a share of 2025 net revenue | [n] / [n] = 0.63% | [n] basis points |
| Growth [wording masked] | [n] / [n] - 1 = [n]% | [n]% |
| Increase in inventory reserves in 2024 ($ million) | [n] - [n] = [n] | [n] |
Management’s best defense, and our reply
The company would say the reserve change is already within the higher product costs of [amount] that MD&A does quantify, that part of the increase reflects growth in inventory rather than a deterioration in its quality, and that it did not regard the reserve as a separately significant driver of results. It would add that the reserve balance is disclosed in Note 2 for both years, so nothing is hidden. That is a tenable position if the charge was small, but the balance doubled while inventory grew [n]%, and Item 303(b)(2)(ii) names inventory adjustments expressly; the staff's 2025 letter to the company already asked it to quantify each material factor in a change, so the point is best answered by the figure.
The fix
- In MD&A, add to the gross-margin paragraph: 'Gross margin was also affected by an $[x] million increase in inventory reserves, primarily related to [cause].' In Note 2, add one sentence on what drove the change in reserves.
Question for the company
What drove the [wording masked] reserves from [amount] to [amount] during 2025 (lower of cost or net realizable value write-downs, shrink, or another component), how much of it was charged to cost of goods sold, and why was it not identified among the gross-margin drivers in MD&A?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Reserves doubled; the note gives no cause | Document | Form 10-K 2025, page 63 |
| 2 | Prior year: a rise of only [n] | Document | Form 10-K 2024 (prior year), page 67 |
| 3 | Net inventory on the balance sheet | Document | Form 10-K 2025, page 56 |
| 4 | MD&A gross-margin drivers: no mention of inventory reserves | Document | Form 10-K 2025, page 47 |
| 5 | The margin-rate fall MD&A explains through occupancy and delivery only | Document | Form 10-K 2025, page 48 |
| 6 | Critical accounting estimates name a single policy (long-lived assets) | Document | Form 10-K 2025, page 51 |
| 7 | 2025 net revenue | Document | Form 10-K 2025, page 57 |
| 8 | 2025 income before taxes | Document | Form 10-K 2025, page 57 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Gross margin increased [amount]
- What is missing
- any discussion of the inventory reserve build and its effect on gross margin
- Pages looked at
- p.44-51 (MD&A results, liquidity and critical accounting estimates) and p.61-63 (Note 2)
- Result
- 'inventory reserve' hits only the definition of cost of goods sold in MD&A and in Note 2 and the use-of-estimates list, none of which explains the change; 'reserves of' hits only the Note 2 sentence itself. The other terms do not hit.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.