1.04 Equity statement: the Class A share column and two captions do not match what the figures contain
Company E · a US-listed home furnishings retailer · Presentation point
In brief
The equity statement closes 2025 with [n] Class A shares, while the balance sheet reports [n] shares outstanding; the difference is unvested restricted stock, which the statement leaves out without saying so. The [n] shares added to treasury are captioned as shares withheld for taxes, but only [n] were withheld; the rest are forfeited restricted shares. A credit of [n] to retained earnings is captioned 'Dividends declared' although no dividend was declared in 2025.
The evidence, as filed
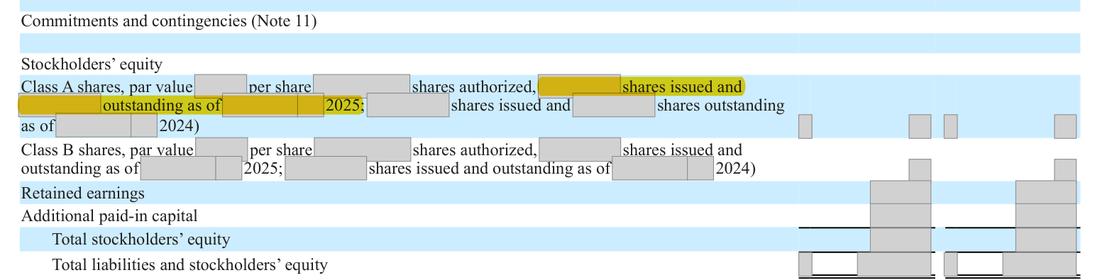
3 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Class A shares at [date]: [n] in the equity statement, [n] outstanding on the balance sheet. Treasury shares rise by [n] on a line captioned for tax withholding that removes [n] Class A shares. 'Dividends declared' shows +[n] in retained earnings. | Captions that say what each line contains (for example 'Shares returned to treasury on forfeiture of restricted stock' and 'Reversal of forfeited dividend equivalents'), and a note that the Class A share column excludes unvested restricted stock, reconciling it to the balance sheet count. |
| What we checked. Equity statement against the balance sheet share counts, the restricted stock table and the dividends paragraph in Note 11 | |
The rule
Regulation S-X Rule 3-04
This analysis shall be presented in the form of a reconciliation of the beginning balance to the ending balance for each period for which a statement of comprehensive income is required to be filed with all significant reconciling items described by appropriate captions with contributions from and distributions to owners shown separately.
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.3-04, eCFR text
Why it applies here. Captions and share column cannot be tied to the balance sheet without the restricted stock note
Why it matters
A reader cannot tie the equity statement share count to the balance sheet, and two 2025 lines name events (a dividend declaration and tax withholding) that did not produce those figures.
Exposure
No amount is misstated; a presentation clean-up in the next annual report.
Our workings
the equity statement shows [n] Class A shares and [n] treasury shares at [date]. The balance sheet shows [n] Class A shares issued and [n] outstanding. The restricted stock table shows [n] unvested shares at the year end and [n] forfeited in 2025. Note 11 says dividends payable fell from [amount] (plus [amount] long-term) to [amount] after [amount] was paid.
balance sheet outstanding less the equity statement column is [n] shares, which is the unvested restricted stock of [n] within rounding; the treasury increase less the Class A reduction is [n], which is the [n] forfeited restricted shares; and the dividends payable roll leaves [amount] released, which is the [n] credit.
the figures are right but the presentation is not. Regulation S-X Rule 3-04 requires the equity reconciliation to describe its reconciling items by appropriate captions; a forfeiture reversal captioned 'Dividends declared' and a forfeiture of restricted shares captioned as tax withholding do not describe what happened, and the Class A column follows an accounting count (unvested restricted stock excluded) that the balance sheet does not use, with nothing telling the reader why the two primary statements disagree.
| Test | Working | What explains it |
|---|---|---|
| Class A shares: balance sheet outstanding less equity statement column | [n] - [n] = [n] | unvested restricted stock [n] |
| Treasury increase less Class A shares withheld (thousand) | [n] - [n] = [n] | restricted stock forfeited [n] |
| Dividends payable released in 2025 ($ million) | [n] + [n] - [n] - [n] = [n] | the [n] credit captioned 'Dividends declared' |
Management’s best defense, and our reply
The company would say every figure is correct, the amounts are trivial against equity of [n], and the forfeitures and dividend equivalents are explained in the restricted stock table and Note 11. It would add that unvested restricted stock is not treated as outstanding for accounting purposes, so excluding it from the equity statement column is the right measurement even though the balance sheet parenthetical gives the legal count. That answers the measurement but not the captions: Rule 3-04 asks for reconciling items described by appropriate captions, and 'Dividends declared' and 'Shares withheld to cover employees' withholding taxes' describe events that did not produce the [n] credit or [n] of the [n] treasury shares. The fix costs nothing and lets the two primary statements agree on their face.
The fix
- Re-caption the [n] line 'Reversal of dividend equivalents on forfeited awards', split the treasury movement into 'Shares withheld for taxes' and 'Restricted stock forfeited', and footnote the Class A column: 'Excludes unvested restricted stock ([n] shares at [date]) included in shares outstanding on the balance sheet.'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Equity statement closing Class A shares [n] and treasury shares [n] | Document | Form 10-K 2025, page 58 |
| 2 | The withholding line removes [n] Class A shares but adds [n] to treasury | Document | Form 10-K 2025, page 58 |
| 3 | A positive [n] in retained earnings captioned 'Dividends declared' | Document | Form 10-K 2025, page 58 |
| 4 | Balance sheet Class A shares issued and outstanding | Document | Form 10-K 2025, page 56 |
| 5 | Restricted stock forfeited in 2025 | Document | Form 10-K 2025, page 75 |
| 6 | Unvested restricted stock at the year end | Document | Form 10-K 2025, page 75 |
| 7 | Dividends payable on unvested awards at each year end | Document | Form 10-K 2025, page 79 |
| 8 | Long-term dividends payable at the start of 2025 | Document | Form 10-K 2025, page 79 |
| 9 | Dividend equivalents paid in 2025 | Document | Form 10-K 2025, page 79 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.