1.02 The equity based compensation note does not give the income tax benefit recognized on compensation cost
Company E · a US-listed home furnishings retailer · Compliance or disclosure gap
In brief
Note 8 gives equity based compensation cost by award type for each of the three years ([n] for 2025, [n] in all), but the 10-K never states the income tax benefit recognized on that cost. US GAAP names that benefit as an amount to disclose for every year an income statement is presented. The prior-year 10-K left it out too.
The evidence, as filed
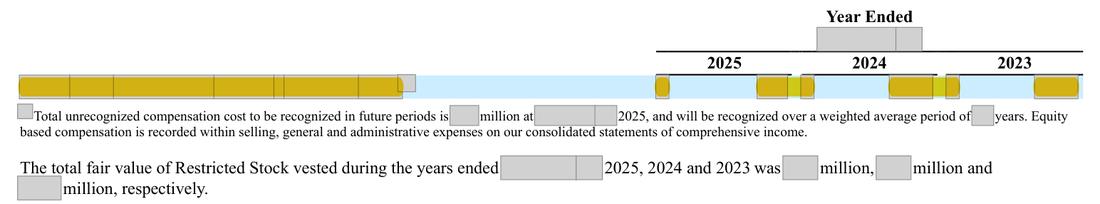
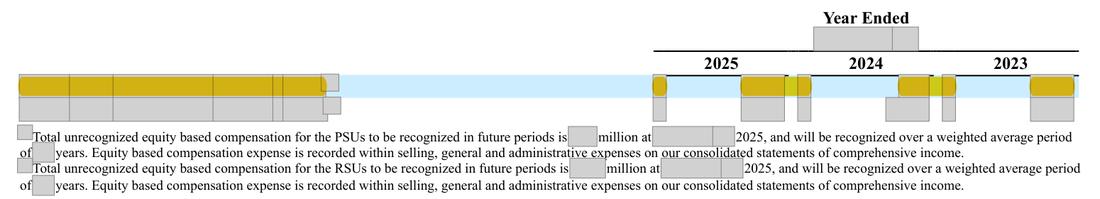
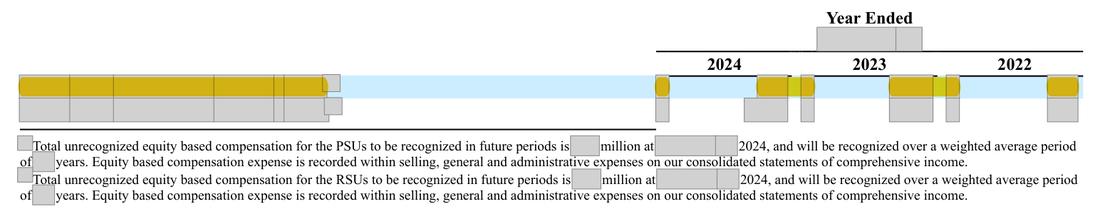
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Compensation cost of [n] / [n] / [n] is given for 2025 / 2024 / 2023; the recognized tax benefit on it appears nowhere in Note 8, Note 13 or elsewhere in the filing. | For 2025, 2024 and 2023, the total income tax benefit recognized in the income statement for share-based compensation, given next to the cost. |
The rule
FASB ASC 718-10-50-1 to 50-2, including 50-2(h)(1) (paraphrase; the Codification text is copyrighted)
Summary; FASB/IFRS text is copyrighted Disclose share-based arrangement terms, fair-value methods and assumptions, award activity, compensation cost and tax effects, and unrecognised cost with weighted-average recognition period.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 718-10-50-2 (as amended by ASU 2016-09)
Regulation S-X Rule 4-01(a)(1)
Financial statements filed with the Commission which are not prepared in accordance with generally accepted accounting principles will be presumed to be misleading or inaccurate, despite footnote or other disclosures
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.4-01(a)(1) (eCFR as of the pack date)
Why it applies here. the share-based payment Topic sets out the recognized tax benefit as a separate amount for each income-statement year; because the cost is close to a tenth of pre-tax income the gap is not trivial, and because the 2024 10-K omits it as well it is a standing practice rather than a one-year slip.
Why it matters
Readers cannot see the after-tax cost of equity awards, and the notes fall short of a named US GAAP disclosure for two consecutive annual reports.
Exposure
A staff comment asking for the amount in future filings is the realistic outcome; no figure in the statements changes.
Our workings
Note 8 shows compensation cost for restricted stock ([n]), PSUs ([n]) and RSUs ([n]) for 2025, with unrecognised cost and the remaining recognition period, and says the cost sits in selling, general and administrative expenses. Note 13 shows the domestic / foreign split, current and deferred components, the rate reconciliation and a deferred tax table that holds only the outside-basis assets for the two operating LLC investments. None of these, nor the equity or cash flow statements, gives the tax benefit recognized on compensation cost.
[n] + [n] + [n] = [n], which is 9.98% of pre-tax income of [n]; at the [n]% effective rate the benefit would be of the order of [n] (an illustration of size only; the true figure depends on the deductible amount and the LLC structure).
| Item | FY2025 | FY2024 | FY2023 |
|---|---|---|---|
| Restricted stock expense | [n] | [n] | [n] |
| PSU expense | [n] | [n] | [n] |
| RSU expense | [n] | [n] | [n] |
| Total compensation cost | [n] + [n] + [n] = [n] | [n] + [n] + [n] = [n] | [n] + [n] + [n] = [n] |
| Cost as % of pre-tax income | [n] / [n] = 9.98% | [n] / [n] = 8.40% | [n] / [n] = 4.69% |
| Order of size of the benefit (illustration at the 2025 effective rate) | [n] x [n]% = [n] | not computed | not computed |
| Recognized tax benefit disclosed | none | none | none |
Management’s best defense, and our reply
Management could argue that the benefit is small and that the tax position runs through the investments in two operating LLCs, so a separate benefit is hard to isolate. It could add that the SEC staff reviewed the 2024 financial statements in 2025 and raised only a results-of-operations comment, which suggests the staff did not see the gap as material. The answer: the Topic names the recognized benefit as an amount for each income-statement year whatever the structure, compensation cost is about 10% of pre-tax income, neither the rate reconciliation nor the two-line deferred tax table lets a reader derive it, and the staff's letter itself says management stays responsible for the adequacy of disclosure whatever the staff's review.
The fix
- Add to Note 8: 'The total income tax benefit recognized in the consolidated statements of comprehensive income for equity based compensation was $x million, $y million and $z million for the years ended [date], 2024 and 2023, respectively.'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Restricted stock compensation cost for 2025, 2024 and 2023 | Document | Form 10-K 2025, page 75 |
| 2 | PSU compensation cost for the three years | Document | Form 10-K 2025, page 76 |
| 3 | RSU compensation cost for the three years; the footnotes that follow give unrecognised cost but no tax benefit | Document | Form 10-K 2025, page 76 |
| 4 | Pre-tax income used to size the cost | Document | Form 10-K 2025, page 78 |
| 5 | 2025 effective tax rate, used only to illustrate the order of size | Document | Form 10-K 2025, page 81 |
| 6 | The deferred tax table holds only the two LLC investment lines; no compensation-related item | Document | Form 10-K 2025, page 81 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Total unrecognized equity based compensation for the PSUs
- What is missing
- the total income tax benefit recognized for share-based compensation cost in 2025, 2024 and 2023
- Pages looked at
- p.58-59 (equity and cash flow statements), 72-73 (policy), 78-80 (Note 8), 83-85 (Note 13)
- Result
- 'tax benefit' hits p.68 and [n] only in 'unrecognized tax benefits' (uncertain tax positions), not compensation; 'tax deduction' hits p.15 (risk factor on tax law) and p.81 (the 2025 tax legislation paragraph on bonus depreciation and research costs); 'income tax benefit', 'excess tax' and 'windfall' have no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.