1.01 Revenue recognized out of the opening client-deposit balance is not disclosed
Company E · a US-listed home furnishings retailer · Compliance or disclosure gap
In brief
Client deposits are the company's contract liability: [n] at the start of 2025 and [n] at the end (USD thousand). US generally accepted accounting principles (US GAAP) require the amount of revenue recognized in each year that came out of the opening contract-liability balance. The 10-K gives the balances and a forward-looking 12-month sentence, but never that figure, for 2025 or for 2024.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Balance sheet: client deposits [n] (2025) and [n] (2024). Note 2: [wording masked] at [date] are expected to be recognized within the next 12 months. No amount is given for revenue recognized in 2025 from the [n] opening balance, or in 2024 from the [n] opening balance. | A sentence in Note 2 giving, for each year presented, the revenue recognized that was included in client deposits at the beginning of that year, with a short explanation of significant changes in the balance. |
| What we checked. Whole 10-K text, the balance sheet, cash flows, Note 2, Note 4 and the segment note; prior-year 10-K Note 2; the 2026 Form 10-Q reports | |
The rule
ASC paragraph 606-10-50-8(b), contract balances
Summary; FASB/IFRS text is copyrighted Disclose opening and closing receivables, contract assets and contract liabilities, revenue recognized from opening contract liabilities, and explain significant changes in contract balances.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC paragraph 606-10-50-8 to 50-10 (as amended by ASU 2014-09); paraphrase, FASB text is copyrighted
Regulation S-X Rule 4-01(a)(1)
Financial statements filed with the Commission which are not prepared in accordance with generally accepted accounting principles will be presumed to be misleading or inaccurate, despite footnote or other disclosures, unless the Commission has otherwise provided.
Version: Text in force at the date of this review · Source: Regulation S-X, 17 CFR 210.4-01(a)(1), eCFR text
Why it applies here. Required quantitative contract-balance figure missing in both years
Why it matters
Readers cannot see how much of each year's revenue was delivered out of the order book carried in from the prior year, which is the main driver of a deposit-funded retailer's revenue timing; the financial statements omit a quantitative disclosure that US GAAP requires.
Exposure
A Securities and Exchange Commission (SEC) staff comment asking for the figure, answered by an undertaking to include it in future filings; an amendment is unlikely.
Our workings
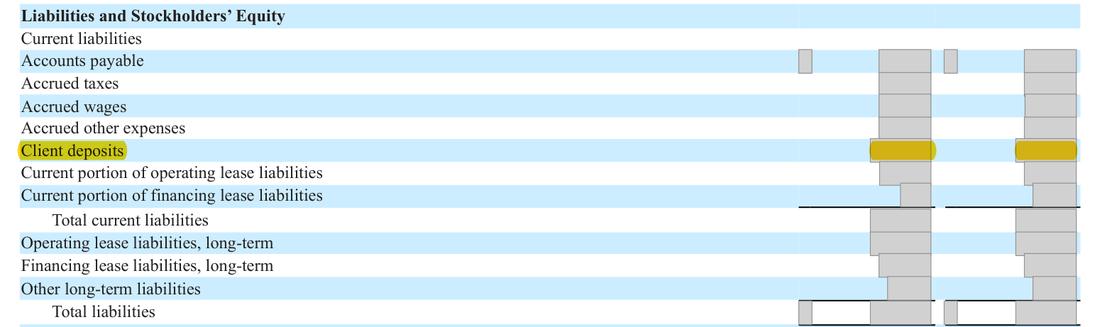
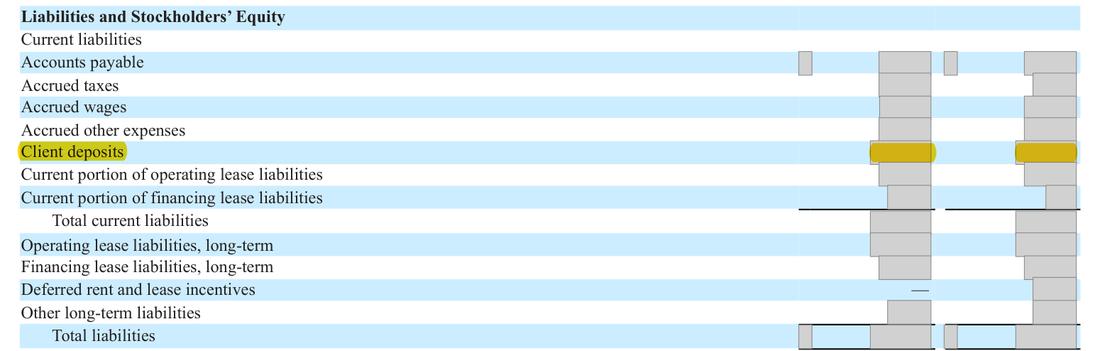
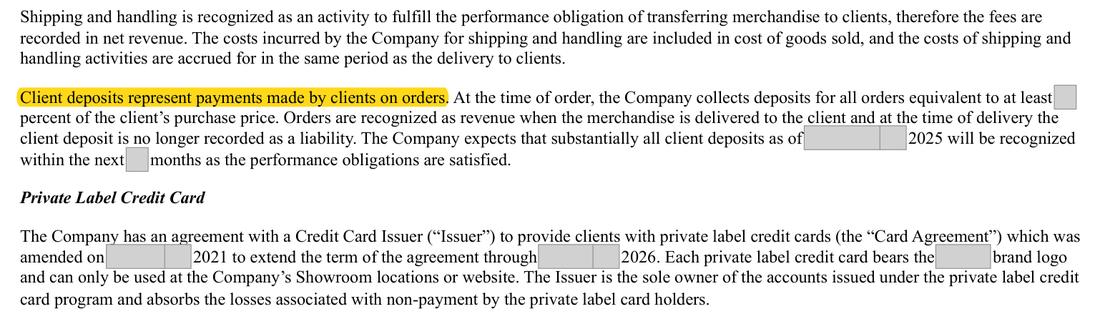
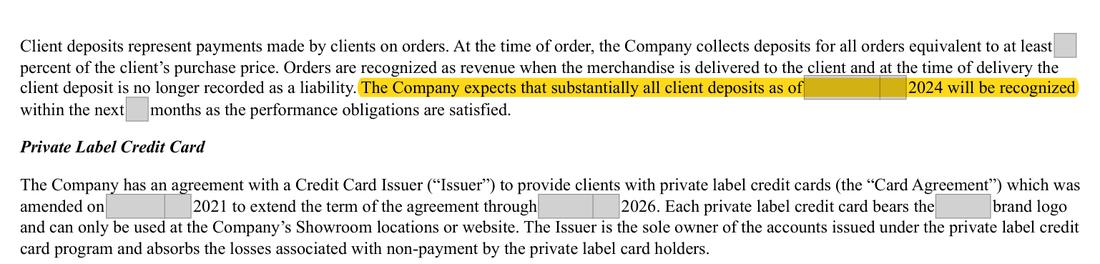
the company takes a deposit on every order and recognizes revenue on delivery, so client deposits are its contract liability under the revenue standard in the FASB Accounting Standards Codification (ASC). The balance sheet shows [n] at [date] and [n] at [date]; the prior-year balance sheet shows [n] at [date]. Note 2 says substantially all deposits at the year end will be recognized within the next 12 months. Nowhere in the 10-K is the revenue recognized from the opening balance given.
the opening balance is [n]% of 2025 net revenue ([n] / [n]) and [n] times income before taxes ([n] / [n]).
ASC paragraph 606-10-50-8 has three limbs: (a) opening and closing balances of receivables, contract assets and contract liabilities, which the balance sheet meets; (b) revenue recognized in the period that was included in the opening contract liability, which is missing; and (c) revenue from obligations satisfied in earlier periods. ASC paragraph 606-10-50-9 and 50-10 then ask for an explanation of significant changes. The 12-month sentence answers a different requirement, the timing of the remaining performance obligations at the closing date (ASC paragraph 606-10-50-13); it looks forward and does not say how much of the opening balance became revenue and how much was cancelled or refunded, which the risk factors identify as a live exposure. The one-year practical expedient in ASC paragraph 606-10-50-14 relieves only the remaining-obligation amount, not the contract-balance figure. For a deposit-funded retailer this figure is the clearest measure of how much of the year's revenue was carried in from the prior year's order book.
| Measure | Working | Result |
|---|---|---|
| Client deposits at [date] (opening contract liability) | balance sheet, [date] column | [n] |
| Client deposits at [date] | balance sheet, [date] column | [n] |
| Opening deposits as a share of 2025 net revenue | [n] / [n] = [n]% | [n]% |
| Opening deposits against 2025 income before taxes | [n] / [n] = [n] | [n] times |
| Client deposits at [date] (prior-year opening) | prior-year balance sheet, [date] column | [n] |
Management’s best defense, and our reply
The company would argue that the balance sheet already gives opening and closing client deposits and that Note 2 tells readers substantially all deposits turn into revenue within 12 months, so the revenue recognized from the opening balance is in substance the opening balance less a small level of cancellations and a separate figure adds little. It would add that the SEC staff reviewed the 2024 Form 10-K in 2025, commented only on the management's discussion and analysis (MD&A) revenue explanation, and closed the review without asking for this figure. However, ASC paragraph 606-10-50-8(b) asks for an actual amount for each year, not an inference: the 12-month sentence is a forward-looking statement about the closing balance and does not say how much of the opening balance was recognized, cancelled or refunded. The staff's closing letter itself states that the company remains responsible for the adequacy of its disclosures notwithstanding any absence of action by the staff, and with the opening balance equal to [n]% of revenue the omission cannot be excused as immaterial.
The fix
- Add to the client-deposits paragraph: 'Net revenue recognized during 2025 that was included in client deposits at [date] was $[x] million (2024: $[y] million from the balance at [date]).'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The contract liability: client deposits of [n] at [date] and [n] at [date] | Document | Form 10-K 2025, page 56 |
| 2 | The only contract-liability disclosure: a forward-looking timing statement about the closing balance | Document | Form 10-K 2025, page 63 |
| 3 | 2025 net revenue used as the size benchmark | Document | Form 10-K 2025, page 57 |
| 4 | 2025 income before taxes used as the size benchmark | Document | Form 10-K 2025, page 57 |
| 5 | Prior-year balance sheet: the 2024 opening balance of [n] | Document | Form 10-K 2024 (prior year), page 58 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Client deposits represent payments made by clients on orders
- What is missing
- the revenue recognized in 2025 (and 2024) that was included in client deposits at the beginning of the year
- Pages looked at
- p.56, [n], 59-67, [n], 78-79 (balance sheet, income statement, cash flows, Note 2, Note 4, segment note, Note 11)
- Result
- 'beginning of the period' hits only the sales-returns reserve table and the warranty table; 'client deposits' hits the risk factor on refunds and the deposit balance, the MD&A cash-flow explanation, the balance sheet, the cash flow statement and the Note 2 policy - none gives revenue recognized from the opening balance. The other terms do not hit.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.