6.03 Risk factor summary spread over parts of three printed pages; Item 105(b) allows two
Company D · a US-listed cloud communications software company · Drafting slip
In brief
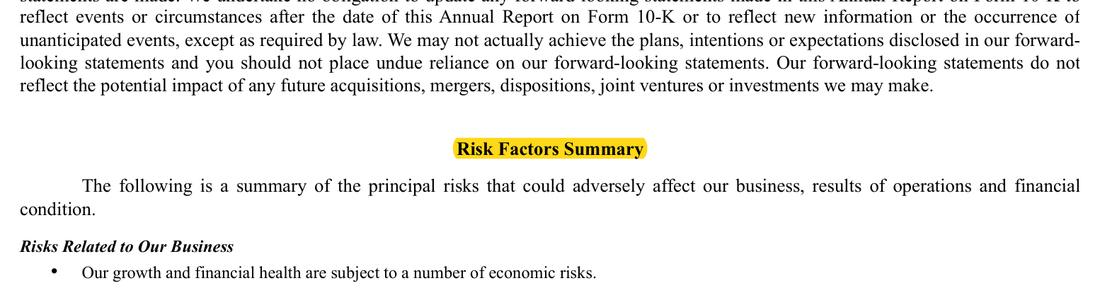
The risk factor summary now starts at the foot of p.3 and runs to near the foot of page 5, where last year it sat on two pages; trimming it to the principal risks would keep it within the two pages Item 105(b) allows.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Risk Factors Summary from the foot of p.3 to p.5 | A summary of the principal risks on no more than two pages |
The rule
Regulation S-K Item 105(b)
If the discussion is longer than [n] pages, include in the forepart of the prospectus or annual report, as applicable, a series of concise, bulleted or numbered statements that is no more than two pages summarizing the principal factors that make an investment in the registrant or offering speculative or risky.
Version: Text in force at the date of this review · Source: 17 CFR 229.105(b), Regulation S-K, as amended by Release 33-10825 (eCFR current text)
Why it applies here. The summary carries about the same content as last year; the spill onto a third page comes from the forward-looking statements above it ending lower on the page. Measured by area it is close to two pages, so this is a layout slip rather than a breach.
Why it matters
Layout only; no reader would decide differently.
Exposure
Layout only; drafting improvement for the next Form 10-K.
Management’s best defense, and our reply
Management would say the summary is about the same length as last year, which fitted on two pages, and that the spill is caused by the pagination of the preceding forward-looking statements, not by more content. Measured by area the summary is close to two pages. That is accepted, which is why the point is a one-line layout slip rather than a finding.
The fix
- Next Form 10-K: trim the summary to the principal risks so that it fits on two pages wherever the forward-looking statements end.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The summary begins at the foot of p.3 | Document | Form 10-K 2025, page 3 |
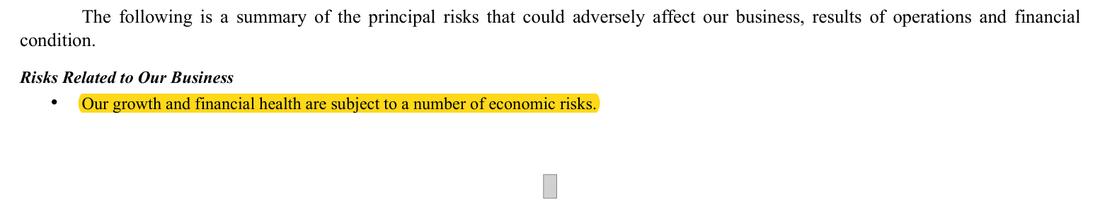
| 2 | First bullet, on p.3 | Document | Form 10-K 2025, page 3 |
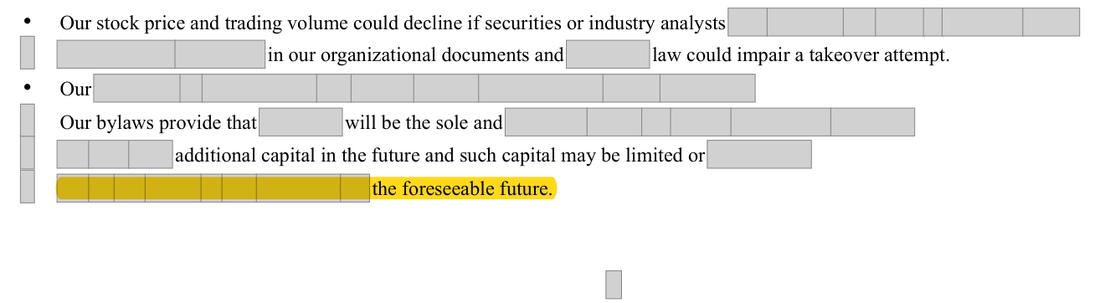
| 3 | Last bullet, near the foot of p.5 | Document | Form 10-K 2025, page 5 |
| 4 | Item 1A begins on p.19 | Document | Form 10-K 2025, page 19 |
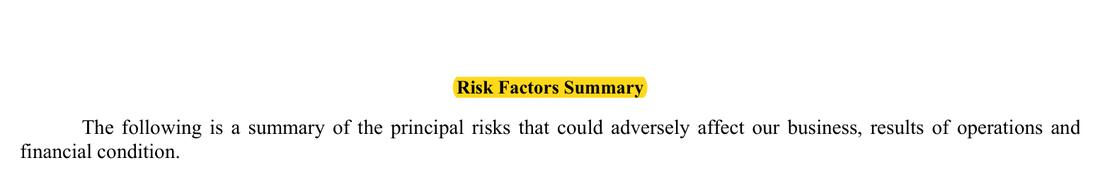
| 5 | In the 2024 Form 10-K the summary began on p.4 and fitted on two pages | Document | Form 10-K 2024 (prior year), page 4 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.