4.06 Average annual customer revenue is reported without a definition, after the company told the staff it would discuss the measure
Company D · a US-listed cloud communications software company · SEC-style question
In brief
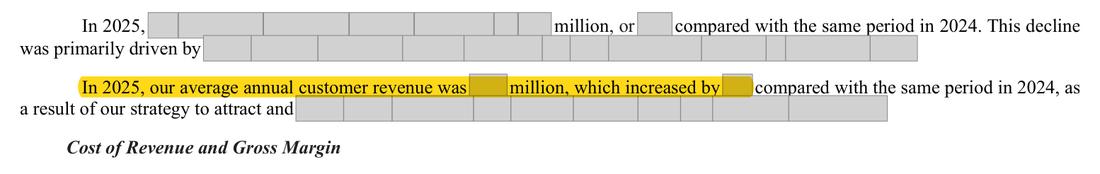
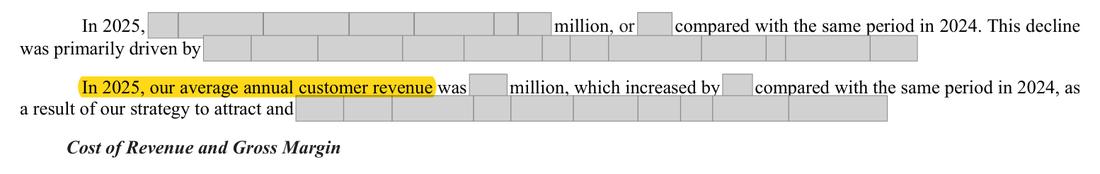
In its [date] reply to a staff comment letter the company said it would discuss average annual revenue per customer in MD&A from the 2024 Form 10-K. MD&A now says average annual customer revenue was [amount] in 2025, up 3%, but never says how the figure is calculated: which revenue, which customers, or what customer count. The key performance indicator section lists only the net retention rate. Rounded to [amount], the figure cannot show the 3% change it reports.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
One sentence: average annual customer revenue of [amount], up 3%; no definition, no customer count, not listed as a key performance indicator | A definition (revenue used, customers counted, how the average is taken), the amounts for both years at a precision that shows the change, and a statement of why management uses it |
The rule
Regulation S-K Item 303(a)
The discussion and analysis must be of the financial statements and other statistical data that the registrant believes will enhance a reader's understanding of the registrant's financial condition, cash flows and other changes in financial condition and results of operations.
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.303(a), as amended by Release 33-10890
Exchange Act Rule 12b-20
there shall be added such further material information, if any, as may be necessary to make the required statements, in the light of the circumstances under which they are made not misleading.
Version: Text in force at the date of this review · Source: 17 CFR 240.12b-20
Why it applies here. the Commission's [date] guidance on key performance indicators expects a clear definition and calculation for a metric management uses to describe its performance; without one the sentence does not let a reader see management's measure of the larger-customer strategy.
Why it matters
A metric introduced to answer a staff comment cannot be understood or tested by a reader; the staff may comment again on the next periodic report it reviews.
Exposure
A question for management; if the staff reviews the filing, a comment letter and a future-filings undertaking are the realistic outcome
Our workings
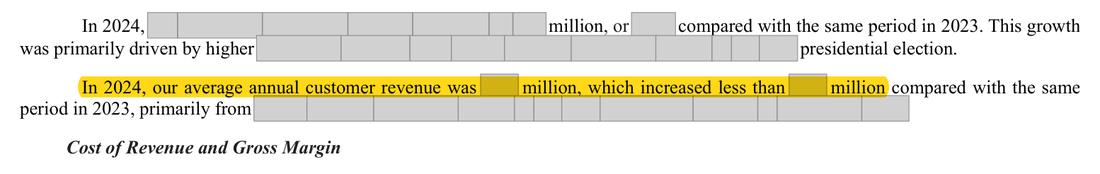
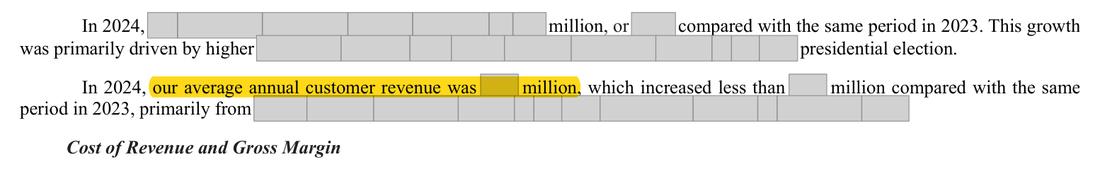
the staff's letter noted that the company no longer presents its active customer count and asked how it monitors its larger customers; the company replied that it would include a discussion of average annual revenue per customer in MD&A. The 2024 and 2025 Forms 10-K each give the figure as [amount] in one sentence; the key performance indicator section, which defines the net retention rate in detail, does not mention it.
any value from [amount] to [amount] prints as [amount], so the reported 3% change cannot be checked from the figures given.
| Item | Value |
|---|---|
| Printed 2025 average annual customer revenue ($ million) | [n] |
| Values that print as [amount] ($ million) | [n] to [n] |
| Customers implied at [amount] if total revenue is used: [n] / [n] | [n] |
| Customers implied at [amount] if total revenue is used: [n] / [n] | [n] |
Management’s best defense, and our reply
Management would say the figure is a simple statistic offered to meet its undertaking, the staff completed its review after receiving the reply, and the measure is not presented as a key performance indicator, so the 2020 guidance does not apply in full. It may add that the customer count behind it is commercially sensitive. However, the metric is used to show that the larger-customer strategy is working, and a reader cannot see how it is built or check the 3% change from a figure rounded to [amount]; a definition and a more precise figure cost nothing in competitive terms.
The fix
- Add to the key performance indicator section: 'Average annual customer revenue is [revenue] for the trailing twelve months divided by [customers] ...; it was $X thousand in 2025 and $Y thousand in 2024.'
Question for the company
How is average annual customer revenue calculated (which revenue, which customers, what count and averaging period), what were the unrounded amounts for 2025 and 2024, and will MD&A define it beside the net retention rate as the measure the company told the staff it uses for its larger customers?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | the metric as reported for 2025: one sentence, no definition | Document | Form 10-K 2025, page 66 |
| 2 | 2025 total revenue used in the implied customer count | Document | Form 10-K 2025, page 65 |
| 3 | the key performance indicator section names only the net retention rate | Document | Form 10-K 2025, page 62 |
| 4 | the staff's comment on the 2023 Form 10-K | Document | |
| 5 | the company's undertaking to the staff, from the 2024 Form 10-K | Document | |
| 6 | the prior-year 10-K gave the metric in the same undefined form | Document | Form 10-K 2024 (prior year), page 66 |
| 7 | the later Form 10-Q repeats the metric, still undefined | Document | |
| 8 | Undertaking to the SEC staff to discuss average annual revenue per customer in MD&A | Document |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- In 2025, our average annual customer revenue
- What is missing
- a definition of average annual customer revenue (revenue used, customers counted, averaging method) and the unrounded amounts
- Pages looked at
- p.61-66 (MD&A overview, key performance indicator, results of operations)
- Result
- 'average annual customer revenue' hits only p.66, the sentence itself; 'per customer' hits only p.30, inside the words 'proper customer consent' in a regulatory risk factor; the other terms do not hit.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.