3.01 Headquarters sublease to a related party: the note gives the cash received, not the income recognized or the year-end balance
Company D · a US-listed cloud communications software company · SEC-style question
In brief
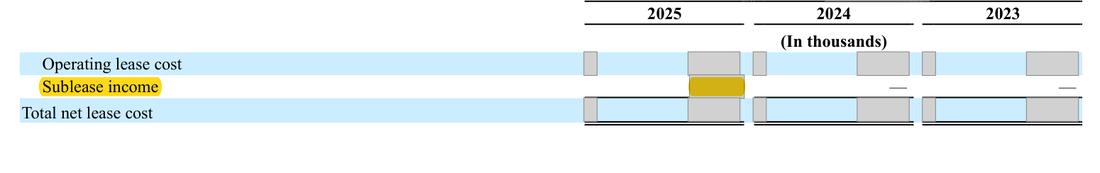
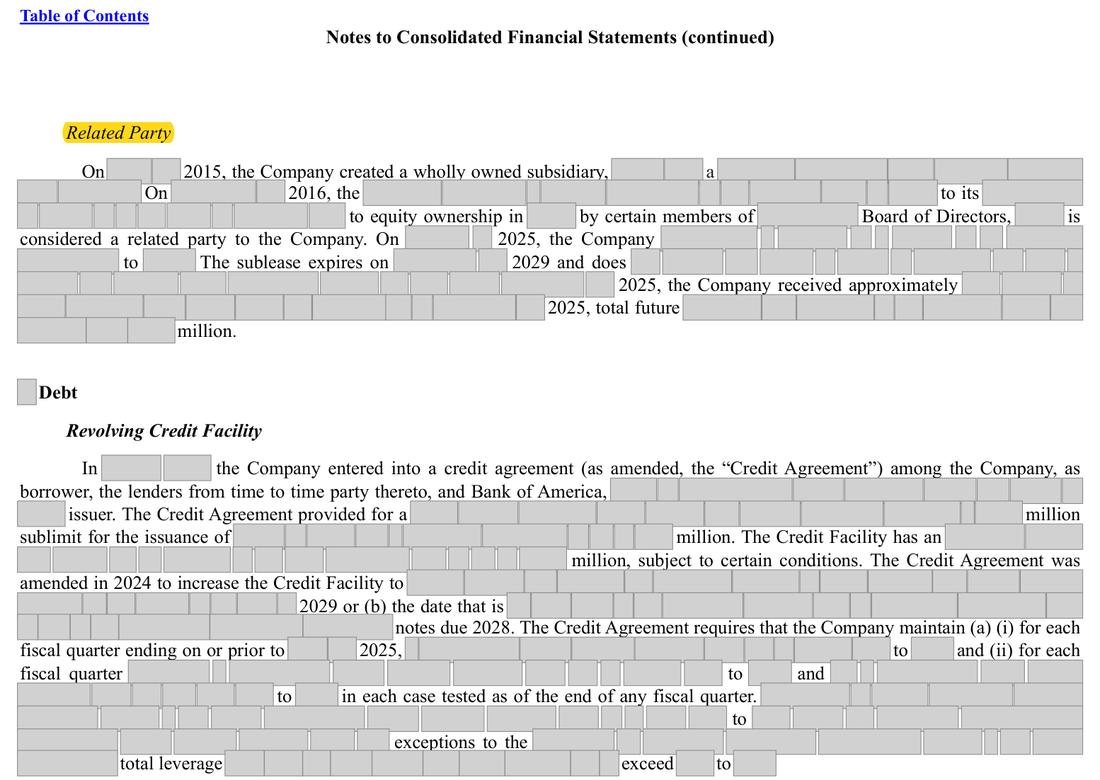
Since [date] the Company has sublet part of its headquarters to [related company], which the note treats as a related party because members of the Board hold equity in it. The note says about [amount] of rent was received in 2025 and [amount] is still to come, but it does not give the sublease income recognized from [related company] or any balance due from [related company] at year end. The lease cost table shows sublease income of [n] for 2025, about twice the cash received, with no split by tenant.
The evidence, as filed
5 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Related-party paragraph gives cash received (about [amount]) and future minimum rents ([amount]); total sublease income for 2025 is [n] with no split by tenant; no amount due from [related company] at [date] is stated. | The related-party paragraph to state the sublease income recognized from [related company] for the year and the balance due from or to [related company] at the balance-sheet date (including any straight-line rent receivable). |
| What we checked. Lease cost table and related-party paragraph on the page images; the whole 10-K for other related-party disclosure; the prior-year 10-K leases and subsequent-events notes and its Item 13; the 2025 and 2026 proxy statements (related-party transactions sections). | |
The rule
Regulation S-X Rule 4-08(k)(1) (17 CFR 210.4-08(k)(1))
Amounts of related party transactions should be stated on the face of the balance sheet, statement of comprehensive income, or statement of cash flows.
Version: Text in force at the date of this review · Source: 17 CFR 210.4-08, eCFR point-in-time text
Why it applies here. [related company] may be the only subtenant, in which case the whole sublease income line is related-party income and a straight-line receivable from [related company] sits on the balance sheet. The related-party Topic of the Codification asks for the dollar amounts of transactions for each income-statement period and the amounts due from or to related parties at each balance-sheet date; Regulation S-X Rule 4-08(k)(1) asks for related-party amounts to be stated on the face of the statements. Cash received is not the same measure as the transaction amount recognized. Prior year: the agreement was signed in [date] and was described, with its aggregate rent, in the 2025 proxy statement, which Item 13 of the prior-year 10-K incorporates by reference; no rent arose in 2024, so the prior-year position is not raised.
Why it matters
Readers cannot see how much of reported income comes from a company in which the chief executive holds equity, or whether that company owes the Company money at year end.
Exposure
A question for management; no penalty attaches. If the answers show material related-party income or balances, the staff could ask for expanded disclosure in future filings.
Our workings
the leases note shows sublease income of [n] for 2025 and none for earlier years. The related-party paragraph says the [related company] sublease began on [date], runs to [date], about [amount] of rent was received in 2025 and future minimum rents were [amount] at year end. The 2026 proxy statement says the agreement was signed on [date] and that aggregate rent over the term is [amount].
([n] + [n]) / 5 = [n] a year on a straight-line basis, which matches the [n] of sublease income in the lease cost table; [n] - [n] = [n] would then be income recognized but not yet received at year end.
| Test | Arithmetic | Result |
|---|---|---|
| Straight-line rent over the five-year term | ([n] + [n]) / 5 = [n] | million a year; the lease cost table shows sublease income of [n] |
| Income recognized less cash received in 2025 (if [related company] is the only subtenant) | [n] - [n] = [n] | thousand not yet received at year end |
| Total rent: this 10-K against the proxy | [n] + [n] = [n] | million against [amount] in the proxy; within the rounding of 'approximately' |
Management’s best defense, and our reply
Management would argue that cash received is a fair measure of the transaction, that the amounts are small against revenue and pre-tax results, and that the proxy statement, which Part III incorporates, describes the agreement and the total rent in full; it would add that the agreement had no accounting effect in 2024 and was disclosed in the 2025 proxy statement. These arguments are tenable for materiality and settle the 2024 position; the open question is only whether income recognized and the year-end balance, rather than cash received, should be the figures given.
The fix
- Expand the paragraph: 'Sublease income recognized from [related company] was $X million for 2025, and amounts due from [related company], including straight-line rent receivable, were $Y million at [date].'
Question for the company
Please state the sublease income recognized from [related company] in 2025 and any amount due from [related company] at [date] (including straight-line rent receivable), and confirm whether [related company] is the only subtenant behind the [n] of sublease income.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | the note treats [related company] as a related party | Document | Form 10-K 2025, page 109 |
| 2 | the note gives cash received, not income recognized | Document | Form 10-K 2025, page 109 |
| 3 | future minimum rents from [related company] at year end | Document | Form 10-K 2025, page 109 |
| 4 | total sublease income for 2025, not split by tenant | Document | Form 10-K 2025, page 107 |
| 5 | the proxy statement dates the agreement to [date] | Document | |
| 6 | aggregate rent over the term per the proxy statement | Document | |
| 7 | the proxy statement ties the related-party status to the chief executive's ownership of [related company] | Document | |
| 8 | the 2025 proxy statement, incorporated into the prior-year 10-K's Item 13, already described the agreement | Document | |
| 9 | Item 13 of the prior-year 10-K incorporates the 2025 proxy statement | Document | Form 10-K 2024 (prior year), page 132 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Related Party
- What is missing
- the sublease income recognized from [related company] in 2025 and the balance due from or to [related company] at year end
- Pages looked at
- p.84, 107-109
- Result
- '[related company]' also hits p.13 (the verb 'relay') and p.16 (the [regulatory program] fund), neither about the related party; 'related party' hits only this paragraph; 'sublease income' hits only the lease cost table on p.107, which gives one total for all subtenants; 'due from related' does not hit.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.