2.03 Item 9B gives no aggregate number of shares for one officer's trading plan, and a second officer's new plan overlaps the plan disclosed a year earlier
Company D · a US-listed cloud communications software company · SEC-style question
In brief
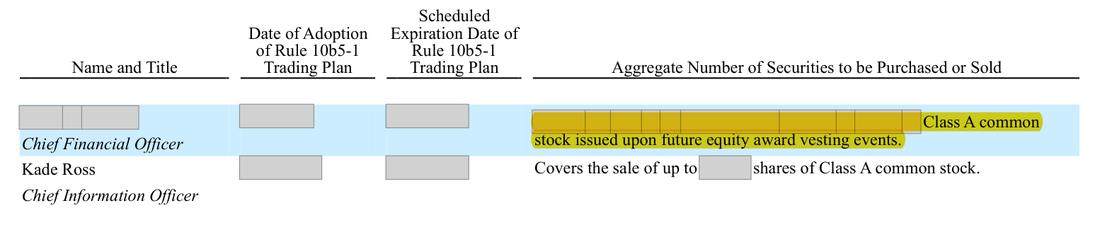
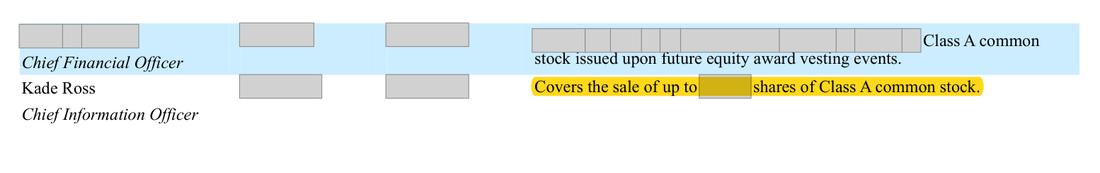
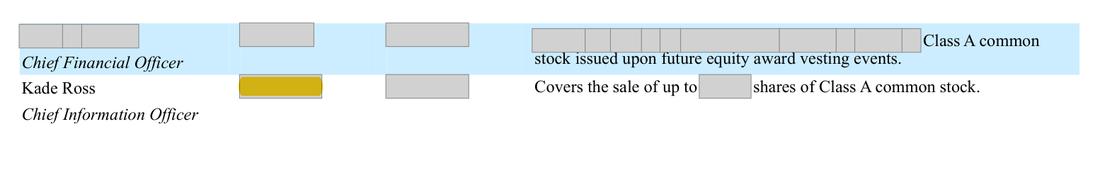
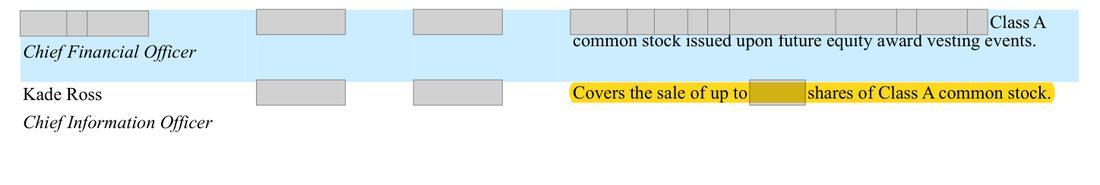
Item 408(a) of Regulation S-K requires, for each officer's trading plan adopted or terminated in the fourth quarter, the aggregate number of securities to be bought or sold. The Chief Financial Officer's plan is described as covering an indeterminate number of shares from future vesting, in this year and last. The Chief Information Officer adopted a plan for up to [n] shares on [date], while the plan disclosed a year earlier for up to [n] shares was scheduled to run to [date]; the 10-K does not say whether the earlier plan was completed or terminated.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Chief Financial Officer: 'an indeterminate number of shares' (plans adopted [date] and [date]); Chief Information Officer: new plan of up to [n] shares adopted [date] while the 2024 plan of up to [n] shares was scheduled to expire [date], with no termination shown | For each plan the aggregate number (or, for a plan that sells only to cover withholding on vesting, the number of awards and the formula); and either a fourth-quarter termination row for the earlier plan or a statement that it had been completed |
The rule
Regulation S-K Item 408(a)(2)(D)
The aggregate number of securities to be purchased or sold pursuant to the trading arrangement.
Version: Text in force at the date of this review · Source: 17 CFR 229.408(a)(2), Regulation S-K, as adopted by Release 33-11138 (eCFR current text)
Regulation S-K Item 408(a)(1)
Disclose whether, during the registrant's last fiscal quarter (the registrant's fourth fiscal quarter in the case of an annual report), any director or officer (as defined in § 240.16a-1(f) of this chapter) adopted or terminated:
Version: Text in force at the date of this review · Source: 17 CFR 229.408(a)(1), Regulation S-K, as adopted by Release 33-11138 (eCFR current text)
Why it applies here. Item 408(a)(2)(D) requires the aggregate number; 'indeterminate' gives none, though a sell-to-cover plan may only be expressible by formula. Two open-market plans of one officer that overlap generally cannot both carry the Rule 10b5-1(c) affirmative defense unless the later plan's trading starts after the earlier one ends; the overlap may be explained by completion of the earlier plan, or by a termination that Item 408(a)(1) would require to be listed. Only the company can say which.
Why it matters
Investors cannot see how many shares an officer may sell, and the record leaves open whether an earlier plan was terminated without disclosure; the staff has commented on both points in other registrants' filings.
Exposure
None until the company answers; a fuller table in the next periodic report if the number or a termination is missing
Our workings
the Item 9B table lists two plans adopted in the fourth quarter of 2025: the Chief Financial Officer's (adopted [date], to [date]), described as covering an indeterminate number of shares issued on future vesting, and the Chief Information Officer's (adopted [date], to [date]), for up to [n] shares. The 2024 Form 10-K (Form 10-K 2024 (prior year) p.131) listed the Chief Financial Officer's prior plan in the same words and the Chief Information Officer's plan adopted [date] for up to [n] shares, scheduled to expire [date].
none.
Management’s best defense, and our reply
Management would say that a plan which sells only enough shares to cover tax withholding on vesting cannot state a number in advance, so 'indeterminate' is accurate. It would add that the Chief Information Officer's 2024 plan may have been fully executed before the new plan was adopted, in which case there was no termination to report and no overlap. Both answers are plausible, which is why this is a question: the 10-K does not say either, and Item 408(a)(2)(D) still asks for the aggregate number, which for a sell-to-cover plan can be given by reference to the awards covered.
The fix
- Give the number for every plan (for a sell-to-cover plan: 'the sale of shares sufficient to cover tax withholding on the vesting of [n] restricted stock units'), and list any fourth-quarter termination, or state that the earlier plan was completed.
Question for the company
For the Chief Financial Officer's plans adopted on [date] and [date], what number of shares, or formula, does each plan set, and why is it described as indeterminate? For the Chief Information Officer, was the plan adopted on [date] (scheduled to run to [date]) completed or terminated before the new plan was adopted on [date], and if it was terminated in the fourth quarter, why is the termination not listed?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Chief Financial Officer's plan adopted [date]: no aggregate number | Document | Form 10-K 2025, page 126 |
| 2 | Chief Information Officer's plan adopted [date], to [date] | Document | Form 10-K 2025, page 126 |
| 3 | Adoption date of the Chief Information Officer's new plan | Document | Form 10-K 2025, page 126 |
| 4 | Chief Information Officer's plan adopted [date] | Document | Form 10-K 2024 (prior year), page 131 |
| 5 | Scheduled expiry of the 2024 plan, after the new plan's adoption | Document | Form 10-K 2024 (prior year), page 131 |
| 6 | The Chief Financial Officer's 2024 plan was described the same way | Document | Form 10-K 2024 (prior year), page 131 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.