2.01 The 2026 proxy statement, incorporated into Part III, gives two different independence determinations, one naming a director who had already resigned
Company D · a US-listed cloud communications software company · Presentation point
In brief
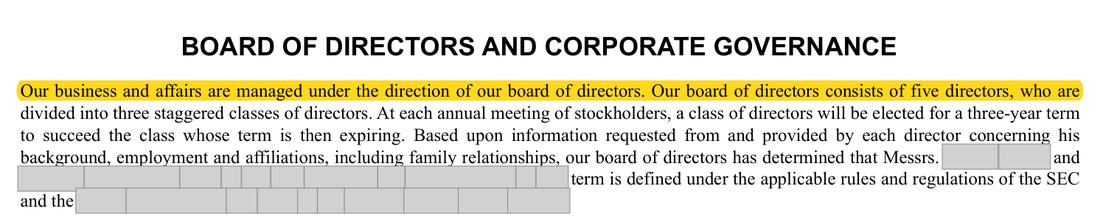
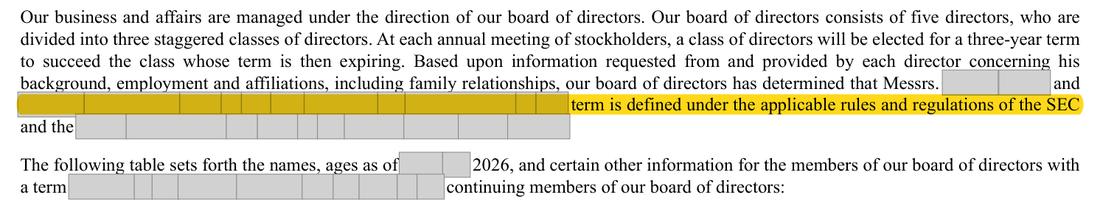
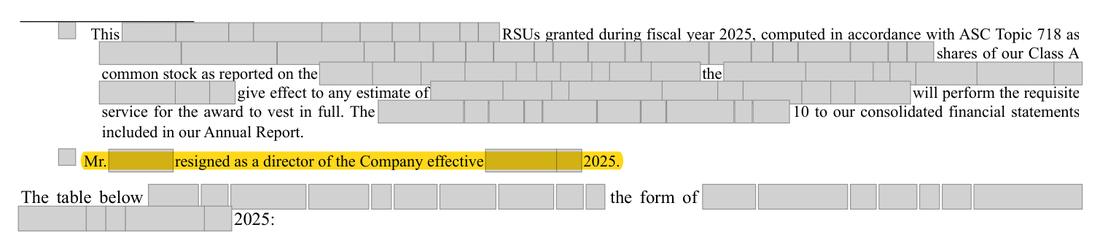
Part III of the 10-K is incorporated from the proxy statement filed on [date]. Its board section says the Board has determined that three of its five directors are independent, but the director-independence section one page later says four of six directors are independent and names a director who resigned effective [date]. The company's own Form 8-K of [date] reported the resignation and the reduction of the board from six members to five.
The evidence, as filed
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Proxy page 7: three of five directors independent; proxy page 8: four of six directors independent, including a director who resigned effective [date] | One independence determination, as of the proxy date, identifying the three independent directors among the five serving |
The rule
Regulation S-K Item 407(a)
Identify each director and, when the disclosure called for by this paragraph is being presented in a proxy or information statement relating to the election of directors, each nominee for director, that is independent under the independence standards applicable to the registrant
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.407(a), as amended
Why it applies here. the second paragraph is the prior year's text left in place. Item 407(a) asks the registrant to identify each director who is independent; the proxy now gives two identifications that disagree on the number of directors and on who serves. The correct identification is present, so the point is an inconsistency rather than an omission; the three directors named in both passages remain a majority of the five, so the Nasdaq majority requirement is not in question.
Why it matters
Investors reading Part III get two different statements of who the independent directors are; a staff review would ask which applies.
Exposure
No penalty; the inconsistency is corrected in the next proxy
Our workings
the proxy's board section states that the Board 'consists of five directors' and that three named directors, 'representing three of our five directors', are independent. The 'Director Independence' section on the next page states that four named directors, 'representing four of our six directors', are independent; one of the four is the director whose resignation effective [date] is stated on proxy page 45 and was reported on Form 8-K on [date], which also reduced the board 'from six members to five members'.
none.
| Passage | Proxy page | Directors identified as independent / board size |
|---|---|---|
| Board of directors summary | 7 | three of five |
| Director Independence | 8 | four of six, including a director no longer serving |
Management’s best defense, and our reply
The company would say the correct determination is printed on the page before, the board table names the five serving directors, and the resignation itself is disclosed in the same document and on Form 8-K, so no reader could be misled about who is independent. Its counsel would point out that a proxy is read as a whole and that the stale paragraph changes no vote. It would add that the three remaining independent directors still form a majority, so nothing of substance changed. The answer: that goes to how much the slip matters, which the category already reflects, but Item 407(a) calls for one identification and the proxy now gives two that disagree on both the count and the people, one of them about a person who was not a director when the proxy was filed.
The fix
- Delete the second paragraph or update it to: a statement that the board has determined that the three directors named in the board section, representing three of its five directors, are independent.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Board size at the proxy date: five | Document | |
| 2 | First determination: three of five directors independent | Document | |
| 3 | Second determination: four of six, naming the director who resigned | Document | |
| 4 | The same proxy records the resignation | Document | |
| 5 | Form 8-K reporting the resignation and the smaller board | Document |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.