1.07 Legal matters: the note says pending cases could materially affect results, but gives no estimate of possible loss and few particulars of the [state] [n] lawsuit
Company D · a US-listed cloud communications software company · SEC-style question
In brief
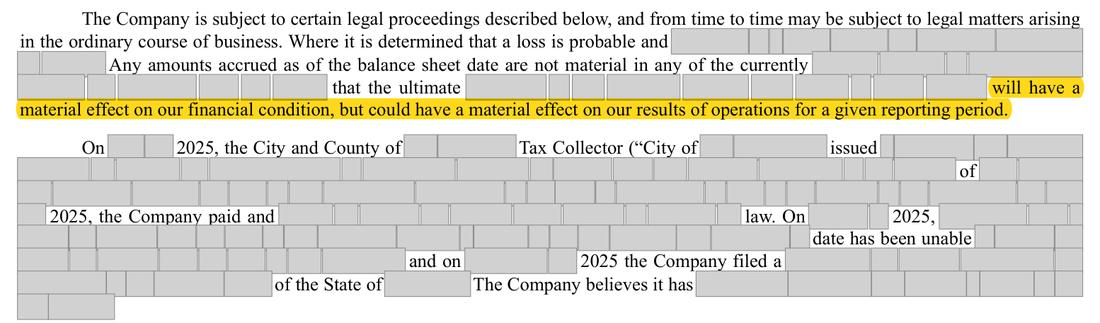
Note 11, which Item 3 incorporates by reference, says the outcome of currently pending legal matters could have a material effect on results of operations for a given reporting period. For the [state] lawsuit [wording masked] [n] taxes and surcharges, the note gives no court, filing date, plaintiffs or relief sought, and for neither that lawsuit nor the [city] Access Line Tax dispute does it give an estimate of the possible loss or range, or say that an estimate cannot be made. The note also does not say where the [amount] paid under protest is carried. Management is asked to explain how these disclosures meet the contingency and legal-proceedings requirements.
The evidence, as filed
1 further page extract: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
General statement that pending matters "could have a material effect on our results of operations"; the [state] [n] lawsuit described in one sentence with no court, date, parties or relief sought; no estimate of possible loss or statement that it cannot be made for either matter; the [amount] paid and placed on deposit under protest with no statement of how it is accounted for. | For each matter where a loss is at least reasonably possible: its nature and an estimate of the possible loss or range, or a statement that such an estimate cannot be made; for a material pending proceeding described in Item 3 (here by cross-reference to the note): the court, date instituted, principal parties, factual basis and relief sought; and the balance-sheet treatment of the amount paid under protest. |
| What we checked. Note 11 Legal Matters; Item 3; the [n] litigation risk factor; whole-report search for any estimate or particulars; prior-year Legal Matters note; the Forms 10-Q for the first two quarters of 2026 | |
The rule
FASB ASC 450-20-50-3 and 50-4 (loss contingencies, reasonably possible losses)
Summary; FASB/IFRS text is copyrighted Accrue probable, estimable losses; for reasonably possible losses disclose nature and an estimate of possible loss or range, or state that none can be made.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 450-20-50-3 to 50-5 (as amended to 2025; paraphrased)
Regulation S-K Item 103(a)
Include the name of the court or agency in which the proceedings are pending, the date instituted, the principal parties thereto, a description of the factual basis alleged to underlie the proceedings and the relief sought.
Version: Text as amended up to [date] · Source: Regulation S-K, 17 CFR 229.103(a)
Regulation S-K Item 103(b)(2)
That involve primarily a claim for damages if the amount involved, exclusive of interest and costs, does not exceed 10 percent of the current assets of the registrant and its subsidiaries on a consolidated basis.
Version: Text as amended up to [date] · Source: Regulation S-K, 17 CFR 229.103(b)(2)
Why it applies here. The Company's own words treat a material effect on results of operations as possible; where a loss is reasonably possible, the contingency standard asks for an estimate of the possible loss or range or a statement that none can be made, and neither is given. Because Item 3 relies wholly on the note, the Item 103 particulars (court, date instituted, parties, relief sought) of the [state] lawsuit are also absent. Whether either requirement is engaged depends on facts only management holds: its probability assessment for each matter and the amount claimed in [state] relative to the threshold of 10% of current assets. The prior-year note, in different words, warned that an adverse outcome could affect results of operations and financial condition and likewise gave no estimate or case particulars; both 2026 Forms 10-Q repeat this year's paragraph unchanged.
Why it matters
Readers cannot judge the size of the exposure the Company itself describes as potentially material to results of operations; contingencies are a recurring subject of staff comment letters.
Exposure
A question for management; if a loss is reasonably possible, the realistic consequence is a staff comment asking for the estimate or the 'cannot estimate' statement and the Item 103 particulars in future filings.
Our workings
Note 11 (p.116) says any amounts accrued are not material and that, in management's opinion, pending matters are not expected to have a material effect on financial condition "but could have a material effect on our results of operations for a given reporting period." It then describes the [city] Access Line Tax assessment of [amount], which the Company "paid and placed on deposit" under protest and is contesting by a refund complaint, and (p.117) a lawsuit in which the Company is a defendant over [n] taxes and surcharges in [local jurisdictions], the City of [city] and the State of [state]. Item 3 (p.58) gives no information of its own and incorporates the note by reference. The [n] risk factor (p.30) refers to litigation in [state] and [state].
| Matter | Accrual stated | Estimate of possible loss or 'cannot estimate' statement | Court / date / parties / relief |
|---|---|---|---|
| [state] [n] taxes and surcharges lawsuit | No (general: accruals not material) | Not given | Not given |
| [city] Access Line Tax ([amount] paid under protest) | No (general: accruals not material) | Not given | Superior Court of [state], refund complaint filed [date]; accounting for the deposit not stated |
Management’s best defense, and our reply
Management could say that it judges any loss in both matters to be remote, so no estimate of possible loss is required. It could add that the sentence about results of operations is a general caution covering all matters, not a probability assessment for these two. It could also say that the amount claimed in [state] is below the Item 103 threshold, so the court, date, parties and relief sought need not be given. However, the note's own words point to a possible material effect on results, the risk factor sends readers to Item 3 for this litigation, and neither this year's note nor the prior-year note gives an estimate or the case particulars, so the basis for leaving out the estimate and the particulars should be stated; because these answers turn on facts only management holds, the point is put as a question.
The fix
- For each matter state whether a loss is probable, reasonably possible or remote; give the estimate of possible loss or range, or say it cannot be estimated and why; for the [state] lawsuit give the court, date filed, plaintiffs and relief sought; state how the [amount] paid under protest is recorded.
Question for the company
For the [state] [n] lawsuit and the [city] Access Line Tax dispute, has management assessed a loss as reasonably possible; if so, what is the estimate of the possible loss or range, or why can it not be estimated? What are the court, filing date, principal parties and relief sought in the [state] lawsuit, and is the amount claimed above 10% of current assets? Where in the balance sheet is the [amount] paid under protest recorded?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The note says pending legal matters could be material to results of operations | Document | Form 10-K 2025, page 116 |
| 2 | [city] assessment of [amount] | Document | Form 10-K 2025, page 116 |
| 3 | The amount was paid under protest; its accounting is not stated | Document | Form 10-K 2025, page 116 |
| 4 | The [state] [n] lawsuit is described in one sentence | Document | Form 10-K 2025, page 117 |
| 5 | Item 3 relies wholly on the note by cross-reference | Document | Form 10-K 2025, page 58 |
| 6 | The risk factor points to Item 3 for the [n] litigation | Document | Form 10-K 2025, page 30 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- The Company is also involved as a defendant
- What is missing
- an estimate of the possible loss or range (or a statement that it cannot be made) and the court, date instituted, parties and relief sought for the [state] lawsuit
- Pages looked at
- p.116-117 (Legal Matters images), p.58 (Item 3), p.30 (risk factor)
- Result
- None of the terms hits anywhere in the 10-K.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.