1.05 Accrued liabilities: the 2024 comparative was regrouped to absorb 'advanced billings' without saying so, while the revenue policy still names that caption
Company D · a US-listed cloud communications software company · Presentation point
In brief
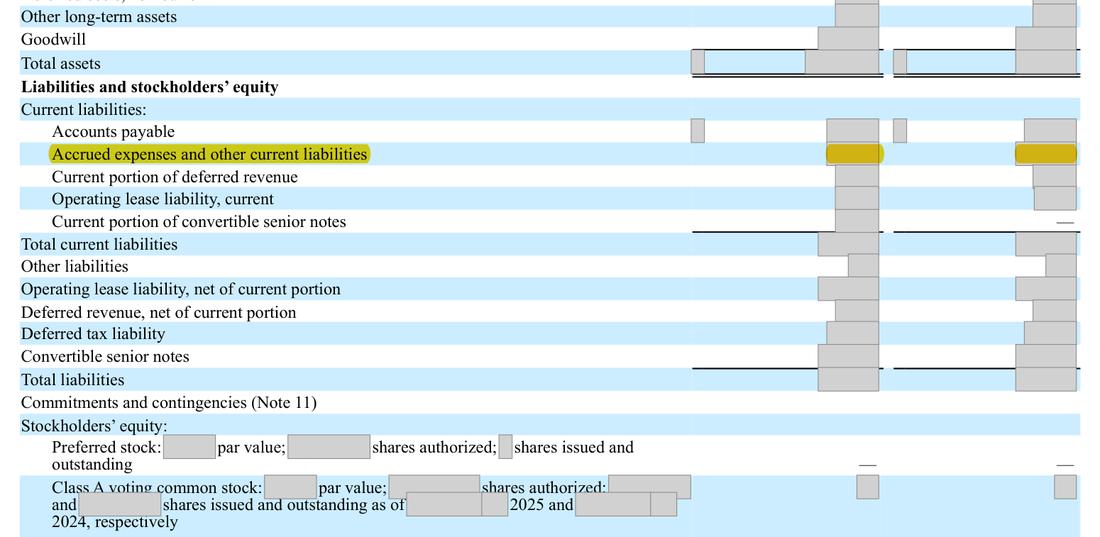
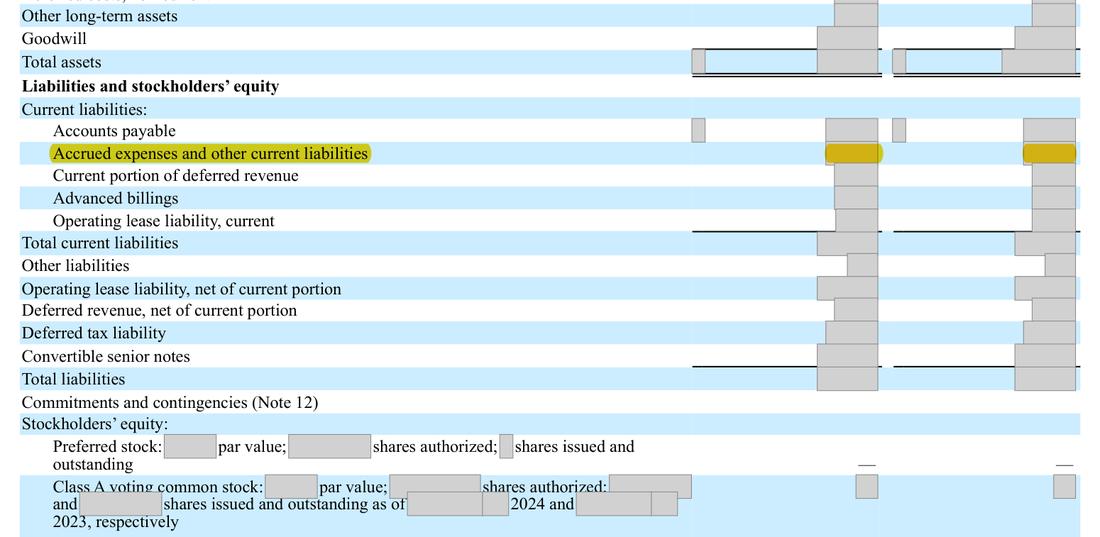
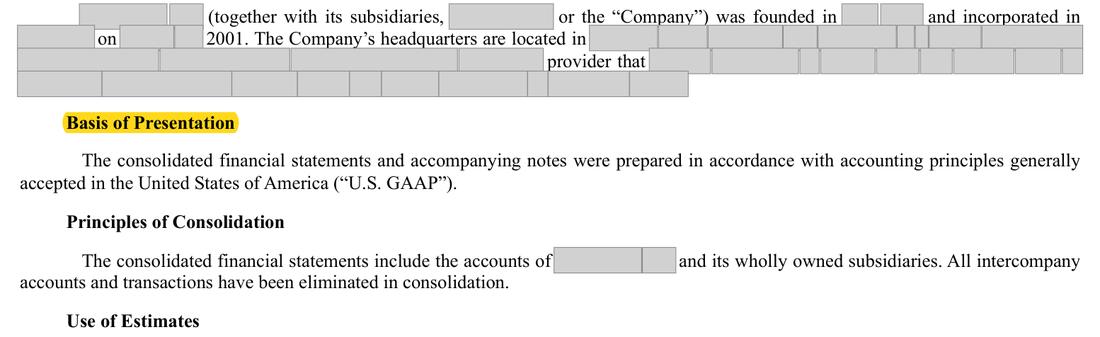
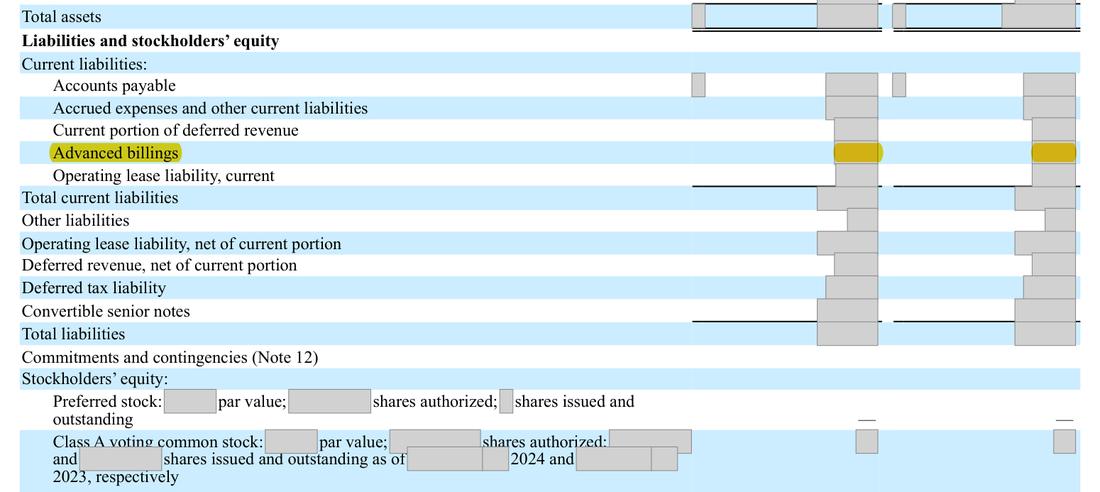
The prior-year 10-K showed 2024 accrued expenses and other current liabilities of [amount] and a separate balance-sheet line 'Advanced billings' of [amount]. This 10-K shows the same 2024 caption at [amount], has no advanced billings line, and adds a 'Customer deposits' row to the accrued-liabilities note. Nothing in the filing says the comparative was regrouped, and the revenue policy still says [wording masked].
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
2024 accrued expenses and other current liabilities: [amount] in this 10-K against [amount] as published; no 'Advanced billings' caption on the balance sheet; the revenue policy says [wording masked]; no reclassification statement. | A one-sentence note that prior-year amounts were reclassified to conform to the current presentation (advanced billings of [amount] now shown in accrued expenses as customer deposits), and the revenue policy updated to name the caption actually used. |
| What we checked. Both balance sheets and both accrued-liability notes on the page images; the whole 10-K for any reclassification sentence; the 2024 cash-flow line for accrued expenses and other liabilities, unchanged between the two filings. | |
The rule
Exchange Act Rule 12b-20 (17 CFR 240.12b-20)
there shall be added such further material information, if any, as may be necessary to make the required statements, in the light of the circumstances under which they are made not misleading
Version: Text in force at the date of this review · Source: 17 CFR 240.12b-20, eCFR point-in-time text
Why it applies here. the advanced billings balance was folded into accrued expenses and relabelled customer deposits, with [n] moved from other accrued expenses. A reader comparing the two filings meets a changed comparative with no explanation, and a policy that points to a caption no longer on the balance sheet. Total current liabilities, net income and equity are unaffected. US GAAP expects a change in how comparative items are presented to be explained.
Why it matters
A reader tying this 10-K to the prior one cannot reconcile the 2024 accrued-liabilities figure without the old filing, and the revenue policy points to a caption that is not on the balance sheet. The SEC staff routinely asks registrants to explain changed comparatives.
Exposure
A staff comment asking for the reclassification to be explained, answered by an undertaking for future filings; no amendment is likely because totals are unchanged.
Our workings
the published 2024 balance sheet carried 'Accrued expenses and other current liabilities' of [n] and a separate 'Advanced billings' line of [n] within total current liabilities of [n]. This 10-K's 2024 column shows accrued expenses of [n], no advanced billings line, and the same total of [n]. Its accrued-liabilities note adds 'Customer deposits' of [n] for 2024 and shows 'Other accrued expenses' of [n] where the prior filing showed [n]. The revenue policy on the contract-balances page still reads that [wording masked].
[n] - [n] = [n], exactly the advanced billings line published; within the note, [n] - ([n] - [n]) = [n].
| Test | Arithmetic | Result |
|---|---|---|
| 2024 accrued liabilities: this 10-K less as published | [n] - [n] = [n] | equals the published advanced billings line [n] |
| Note rows that explain the move | [n] - ([n] - [n]) = [n] | customer deposits less the [n] taken from other accrued expenses |
| Share of the 2024 caption | [n] / [n] = 3.63% | presentation only; total current liabilities [n] in both filings |
Management’s best defense, and our reply
Management would say this is an immaterial presentation change inside current liabilities: totals, net income, equity and cash flows are untouched, and the note itself now shows the customer deposits row for both years, which tells the reader where the balance sits. Under the Codification's materiality principle a reclassification of this size needs no separate sentence. However, the point is not the size of the move but that the filing contradicts itself: the policy still names a caption that no longer exists, and the comparative differs from the published figure with no word of explanation, which costs one sentence to cure.
The fix
- Add to Basis of Presentation: 'Certain prior-year amounts have been reclassified to conform to the current-year presentation, including advanced billings now presented as customer deposits within accrued expenses and other current liabilities.' Change the revenue policy to: 'Customer refundable payments are recorded as customer deposits within accrued expenses and other current liabilities.'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | this 10-K's balance sheet shows 2024 accrued expenses of [n] and no advanced billings line | Document | Form 10-K 2025, page 84 |
| 2 | 2024 total current liabilities unchanged at [n] | Document | Form 10-K 2025, page 84 |
| 3 | 2024 accrued expenses as published in the prior-year 10-K: [n] | Document | Form 10-K 2024 (prior year), page 88 |
| 4 | the separate advanced billings line published for 2024: [n] | Document | Form 10-K 2024 (prior year), page 88 |
| 5 | new customer deposits row in the accrued-liabilities note, [n] for 2024 | Document | Form 10-K 2025, page 104 |
| 6 | 2024 other accrued expenses now [n] | Document | Form 10-K 2025, page 104 |
| 7 | 2024 other accrued expenses as published: [n] | Document | Form 10-K 2024 (prior year), page 107 |
| 8 | the revenue policy still names the advanced billings caption | Document | Form 10-K 2025, page 92 |
| 9 | 2024 Form 10-K: accrued expenses at [date] as published | Document | Form 10-K 2024 (prior year), page 88 |
| 10 | 2024 Form 10-K: Advanced billings shown as its own current-liability caption | Document | Form 10-K 2024 (prior year), page 88 |
| 11 | This Form 10-K: the 2024 comparative of accrued expenses is [n]; no Advanced billings line follows | Document | Form 10-K 2025, page 84 |
| 12 | Total current liabilities 2024 unchanged at [n] | Document | Form 10-K 2025, page 84 |
| 13 | New Customer deposits line in the accrued-expenses note, 2024 comparative [n] | Document | Form 10-K 2025, page 104 |
| 14 | Other accrued expenses 2024 re-presented at [n] | Document | Form 10-K 2025, page 104 |
| 15 | 2024 Form 10-K: other accrued expenses 2024 as published [n] | Document | Form 10-K 2024 (prior year), page 107 |
| 16 | Revenue policy still names the Advanced billings caption that the balance sheet no longer shows | Document | Form 10-K 2025, page 92 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Basis of Presentation
- What is missing
- any statement that prior-year amounts were reclassified to conform to the current presentation
- Pages looked at
- p.84, 90-92, [n]
- Result
- 'reclassif' hits only p.50, a risk factor about classifying the convertible notes as current; 'advanced billings' hits only p.92, the revenue-policy sentence quoted in this point; the other terms do not hit.
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Basis of Presentation
- What is missing
- a statement that prior-year amounts were reclassified to conform to the current presentation (Advanced billings combined into accrued expenses and other current liabilities)
- Pages looked at
- p.84, [n], 90-92, [n] (page images)
- Result
- 'reclassif' hits only p.50 (risk factor on classifying the convertible notes as current); 'conform' hits p.46, [n] (conformity with GAAP, ISO certification, the audit opinion); 'prior period' hits p.22, [n] (marketing, restatement risk factor, goodwill, pension, tax roll-forward); 'Advanced billings' hits only p.92, the revenue-policy sentence quoted in this point. None is a reclassification statement.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.