4.01 A separation agreement with a 2025 named executive officer is neither filed nor listed as an exhibit
Company C · a US-listed specialty healthcare products company · Compliance or disclosure gap
In brief
The proxy statement that supplies Part III of this report names the former Chief Marketing Officer as one of the named executive officers for 2025. It describes a separation and release agreement with her dated [date] and says her severance and pro-rated 2025 bonus were paid pursuant to that agreement: 12 months of base salary ([amount]), company-paid health premiums for up to 12 months (estimated at [amount]) and [amount] in lieu of outplacement, with the bonus paid in [date]. Regulation S-K deems any compensatory contract in which a named executive officer participates material and requires it to be filed. The exhibit index of this Form 10-K lists neither the separation agreement nor her 2023 employment agreement, which last year's index carried, and the third-quarter 2025 Form 10-Q did not file it.
The evidence, as filed
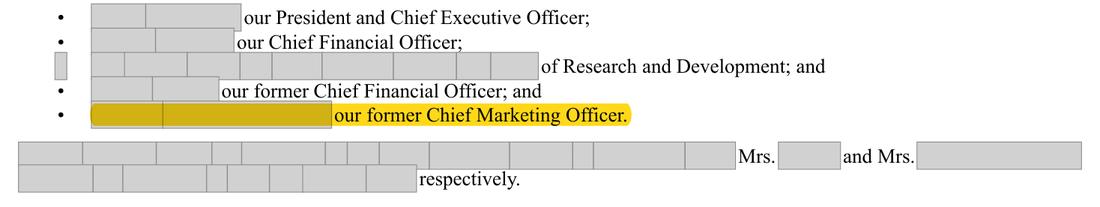
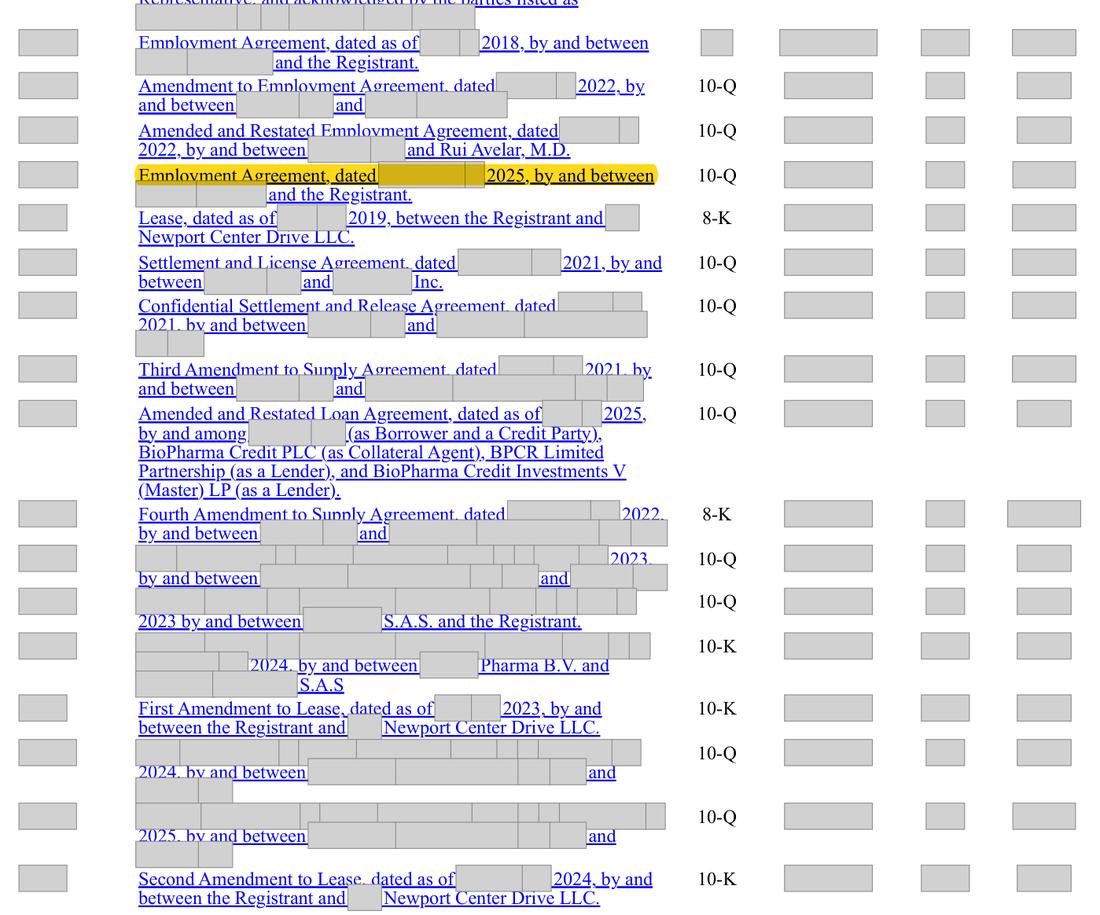
3 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Exhibit index: employment agreements of the chief executive, the chief medical officer and the new chief financial officer only; no separation agreement with the former Chief Marketing Officer, and her [date] employment agreement (listed in the 2024 index) is no longer listed. Proxy: her 2025 payments were made pursuant to the Separation Agreement of [date]. | The separation and release agreement filed (or incorporated by reference from the periodic report for the quarter in which it was signed) and listed in the Form 10-K exhibit index as a management contract or compensatory arrangement. |
| What we checked. Exhibit index of the 2025 and 2024 Forms 10-K; the 2025 Form 10-K signature page; exhibit lists of the second- and third-quarter 2025 and first- and second-quarter 2026 Forms 10-Q; the [date] current report; the 2026 proxy statement; Item 601 of Regulation S-K and the SEC staff's interpretations of it. | |
The rule
Regulation S-K Item 601(b)(10)(iii)(A) (management contracts and compensatory plans)
in which any director or any of the named executive officers of the registrant, as defined by Item 402(a)(3) (§ [n](a)(3)), participates shall be deemed material and shall be filed
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.601 (eCFR, as amended and in force for fiscal 2025)
Regulation S-K Item 601(a)(4) (exhibits executed during the period)
If a material contract or plan of acquisition, reorganization, arrangement, liquidation or succession is executed or becomes effective during the reporting period reflected by a Form 10-Q or Form 10-K, it shall be filed as an exhibit to the Form 10-Q or Form 10-K filed for the corresponding period
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.601 (eCFR, as amended and in force for fiscal 2025)
Regulation S-K Item 601(b)(10)(i)(A) (material contracts still to be performed)
Every contract not made in the ordinary course of business that is material to the registrant and is to be performed in whole or in part at or after the filing of the registration statement or report
Version: Text in force at the date of this review · Source: Regulation S-K, 17 CFR 229.601 (eCFR, as amended and in force for fiscal 2025)
SEC staff, Regulation S-K Compliance and Disclosure Interpretations, Interpretation [n] (staff view)
For purposes of Form 10-K, Item 601(b)(10)(iii) of Regulation S-K requiring disclosure of remunerative contracts would apply to a deferred compensation plan entered into during the fiscal year, even though the officer/director retired during that fiscal year and no longer was an officer/director
Version: Text in force at the date of this review · Source: SEC Division of Corporation Finance, Regulation S-K Compliance and Disclosure Interpretations, as published at the pack date
Why it applies here. the agreement under which a 2025 named executive officer was paid was signed in the third quarter of 2025 and was still being performed when the Form 10-K was filed (health premiums for up to 12 months from [date]), so it should have been filed with the third-quarter Form 10-Q and listed in this Form 10-K.
Why it matters
Investors cannot read the terms on which a named executive officer left, although the proxy reports the payments; a required exhibit is missing from both the third-quarter 2025 Form 10-Q and the 2025 Form 10-K.
Exposure
A staff comment asking for the agreement to be filed with the next periodic report; no fixed penalty.
Our workings
the proxy statement lists the former Chief Marketing Officer among the named executive officers for 2025 and states that she and the Company entered into a separation and release agreement dated [date], the day her departure took effect. It says the amounts reported for her were paid pursuant to the Separation Agreement: a lump sum of 12 months of base salary ([amount]), company-paid health premiums for up to 12 months (estimated at [amount]), [amount] in lieu of outplacement, and a pro-rated 2025 [wording masked] and paid in [date]. The Form 10-K was signed on [date]. Its exhibit index lists the employment agreements of the chief executive, the chief medical officer and the new chief financial officer, but neither the separation agreement nor the former Chief Marketing Officer's [date] employment agreement, which the 2024 index listed; the third-quarter 2025 Form 10-Q filed only the new chief financial officer's agreement and a supply amendment. Law: Item 601(b)(10)(iii)(A) of Regulation S-K deems any compensatory contract in which a named executive officer participates material and says it shall be filed; Item 601(a)(4) requires a material contract executed during the period of a Form 10-Q or Form 10-K to be filed with that report; and Item 601(b)(10)(i)(A) reaches a contract that is still to be performed at or after the filing. The SEC staff's published interpretation applies Item 601(b)(10)(iii) in a Form 10-K to a compensatory arrangement entered into during the fiscal year even though the officer left during that year. None of the exceptions in Item 601(b)(10)(iii)(C) fits a severance agreement with an individual officer.
Management’s best defense, and our reply
Management would say the separation agreement only carries out the severance terms of the [date] employment agreement, already on file, in exchange for the customary release, and the [date] current report said she was entitled to severance consistent with that employment agreement and that no other compensatory arrangement was entered into or amended. They would add that an agreement with an officer who has left need not stay in the exhibit index. The answer: the proxy itself says the payments and the pro-rated bonus were made pursuant to the Separation Agreement, so it is the operative compensatory contract with a named executive officer, which Item 601(b)(10)(iii)(A) deems material with no exception for agreements that carry out earlier ones; if instead the 2023 employment agreement were the operative contract, it would still have had to stay listed while its severance terms were being performed after the filing, yet it was dropped. The staff's interpretation answers the point that she has left.
The fix
- File the separation and release agreement as an exhibit to the next periodic report, marked as a management contract or compensatory arrangement, and list it in the next Form 10-K exhibit index.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The proxy describes a separation and release agreement dated [date] | Document | |
| 2 | The pro-rated 2025 bonus was paid under the agreement in [date], the month the Form 10-K was filed | Document | |
| 3 | She is a named executive officer for 2025 | Document | |
| 4 | Salary and health premiums paid under the separation agreement | Document | |
| 5 | The [date] current report preceded the separation agreement | Document | |
| 6 | The 2025 exhibit index lists the new Chief Financial Officer's agreement but no separation agreement | Document | Form 10-K 2025, page 101 |
| 7 | The proxy says her 2025 bonus was payable under the separation agreement | Document | |
| 8 | The proxy says her severance was paid under the separation agreement, not directly under the employment agreement | Document | |
| 9 | The outplacement payment under the separation agreement | Document | |
| 10 | Health premiums run for up to 12 months from the [date] departure, so the agreement was still being performed when the Form 10-K was filed | Document | |
| 11 | Her departure took effect on the date of the separation agreement, in the third quarter of 2025 | Document | |
| 12 | The current report ties the severance to the 2023 employment agreement, which the 2025 index no longer lists | Document | |
| 13 | The Form 10-K was signed and filed on [date], inside the period the health premiums were still payable | Document | Form 10-K 2025, unnumbered page |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- [n]+
- What is missing
- The separation and release agreement of [date] with a named executive officer (or her employment agreement) as a compensatory-arrangement exhibit
- Pages looked at
- p.100-102 (exhibit index)
- Result
- '[name]' and 'Chief Marketing' have no hits. 'separation' hits p.51 and 'severance' hits p.76, both about the 2025 restructuring benefits for employees. 'release agreement' hits p.101, the 2021 settlement and release agreement with the product supplier (exhibit [n]): neither is the officer's agreement.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.