1.12 Revenue said to come from the opening contract-liability balance equals almost all of a balance described mainly as rebates owed to customers
Company C · a US-listed specialty healthcare products company · SEC-style question
In brief
The note groups customer rebates and deferred revenue for the loyalty Reward and co-branded advertising into one line, accrued revenue contract liabilities, of [amount] at the start of 2025 and [amount] at its end. It then states that [amount] of 2025 revenue came from amounts in the opening balance, which is 98.9% of that balance. Rebates owed to customers are settled by payment or credit and do not become revenue when settled; only the deferred-revenue part does. The note does not give the split, so a reader cannot tell what the [amount] measures.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
One combined balance (rebates plus deferred revenue) of [amount] at [date]; revenue recognized from the opening balance of [amount] (98.9%); the 2024 comparative is [amount] against an opening balance of [n] (92.6%). No split between rebates owed and deferred revenue. | The rebate accrual shown as a refund liability separately from contract liabilities, and revenue recognized from the opening contract-liability balance given for the deferred-revenue part only (or an explanation of why the whole balance is recognized as revenue). |
| What we checked. Contract-balance paragraph and movement, gross-to-net policy, accrued expenses note, prior-year note as published, later quarterly reports | |
The rule
ASC 606-10-50-8 to 50-10 (contract balances)
Summary; FASB/IFRS text is copyrighted Disclose opening and closing receivables, contract assets and contract liabilities, revenue recognized from opening contract liabilities, and explain significant changes in contract balances.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 606-10-50-8 to 50-10 (as issued by ASU 2014-09)
Why it applies here. under the revenue standard, amounts expected to be refunded to customers are a refund liability, and settling it by payment or credit reduces cash or receivables, not deferred revenue; only the loyalty and advertising obligations turn into revenue when satisfied. A near-total release of a balance described as mainly rebates suggests that rebate settlements are counted as revenue recognized from the opening balance, which would overstate that disclosure and blend refund liabilities with contract liabilities. The note does not give the split, so this is a question, not a finding.
Why it matters
If rebate settlements are included, the figure for revenue recognized from opening contract liabilities is overstated and refund liabilities are presented as contract liabilities; net revenue itself is not affected. The realistic result is a staff comment asking for the split and a revised disclosure in future filings.
Exposure
A question for management; net revenue is not in question.
Our workings
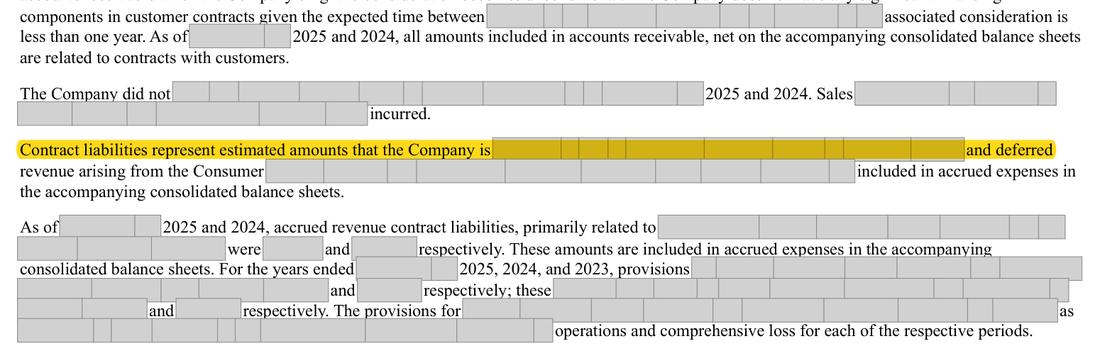
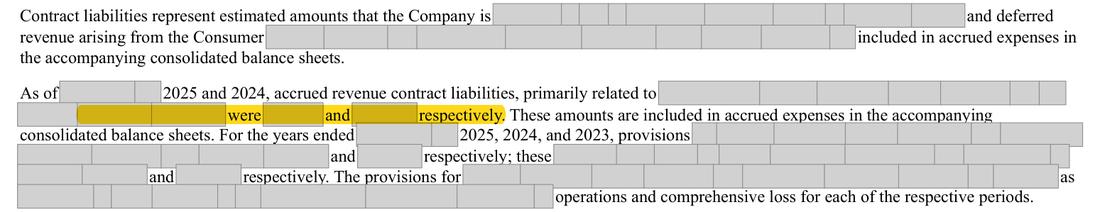
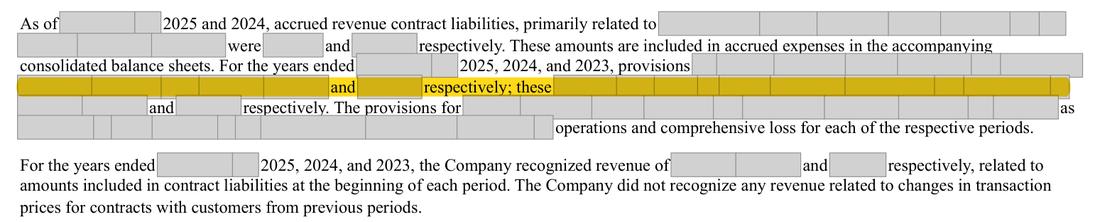
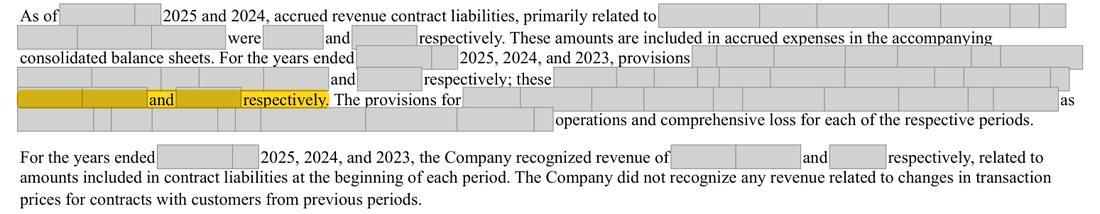
the note says contract liabilities are amounts the Company is obligated to pay to customers and consist mainly of customer rebates and deferred revenue from the loyalty and co-branded programs. The volume-based rebates are determined from contract terms and quarterly purchase volumes; the loyalty Reward and the co-branded advertising are separate performance obligations whose allocated price is deferred and recognized when the Reward is redeemed or [wording masked] balance was [amount] at [date] and [amount] at [date]; 2025 provisions were [amount] and payments, redemptions and adjustments [amount]. The Company states that revenue of [amount] in 2025 (2024: [amount]) related to amounts included in contract liabilities at the beginning of the period.
[amount] is 98.9% of the opening balance and the 2024 figure is 92.6% of its opening balance.
| Item | Computation | Source |
|---|---|---|
| Closing balance [date] from the movement | [n] + [n] - [n] = [n] (printed [n]: rounding) | Note 2, contract balances |
| Opening balance [date] from the 2024 movement | [n] - [n] + [n] = [n] | Note 2, contract balances |
| Share of opening balance recognized as revenue, 2025 | [n] / [n] = 98.9% | computed |
| Share of opening balance recognized as revenue, 2024 | [n] / [n] = 92.6% | computed |
Management’s best defense, and our reply
The finance team may say the rebate accrual and the loyalty and co-branded deferrals are managed as one pool of variable consideration, and that rebates are largely settled by credit against later invoices, so the release of the opening accrual is in substance part of the transaction price recognized in the later period; on that reading the whole opening balance is fairly called revenue recognized. They may add that the total gross-to-net provision and its movement are disclosed, so investors can see the size of the programs. However, the revenue standard treats amounts expected to be refunded to customers as a refund liability, not a contract liability, and settling it by payment or credit does not create revenue; only satisfying the loyalty and advertising obligations does. Without the split a reader cannot tell what the [amount] measures, and the near-total release points to rebate settlements being included.
The fix
- Present 'Accrued customer rebates (refund liabilities)' and 'Deferred revenue - loyalty and co-branded programs (contract liabilities)' separately in Note 5, and state revenue recognized from the opening contract-liability balance for the deferred-revenue part only.
Question for the company
Of the [amount] opening balance of accrued revenue contract liabilities, how much was rebates owed to customers and how much was deferred revenue for the loyalty Reward and co-branded advertising? Does the [amount] of revenue recognized from the opening balance include rebates settled by payment or credit and, if so, what is the figure for the deferred-revenue part alone?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The balance is described as amounts owed to customers, mainly rebates and deferred revenue | Document | Form 10-K 2025, page 75 |
| 2 | Closing balances: [amount] (2025) and [amount] (2024) | Document | Form 10-K 2025, page 75 |
| 3 | Provisions charged against gross revenue in each year | Document | Form 10-K 2025, page 75 |
| 4 | Payments, redemptions and adjustments in each year | Document | Form 10-K 2025, page 75 |
| 5 | Revenue said to be recognized from the opening contract-liability balance | Document | Form 10-K 2025, page 75 |
| 6 | Rebates are amounts payable to customers, settled by reference to quarterly volumes | Document | Form 10-K 2025, page 74 |
| 7 | Only the loyalty Reward (and the co-branded advertisement) is deferred revenue that later becomes revenue | Document | Form 10-K 2025, page 74 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.