7.10 Four wording slips in the fair value, acquisition and other assets notes
Company B · a US-listed transportation and logistics company · Drafting slip
In brief
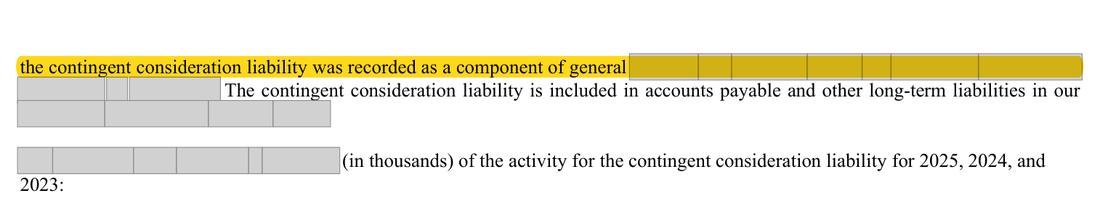
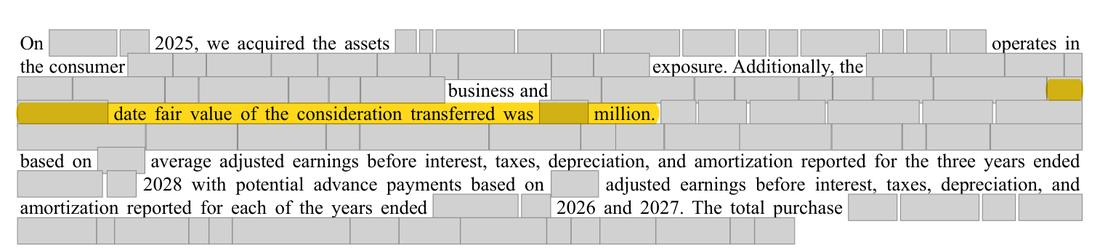
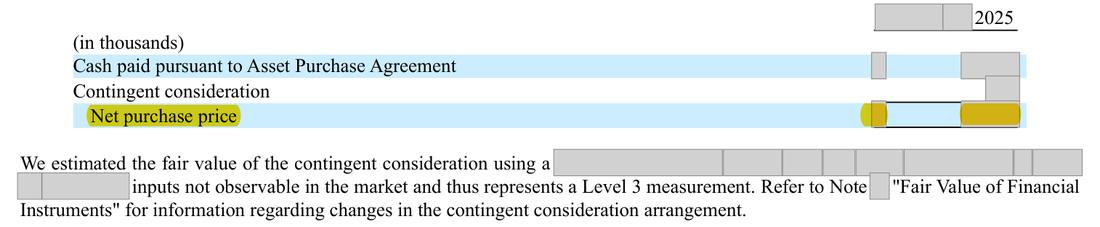
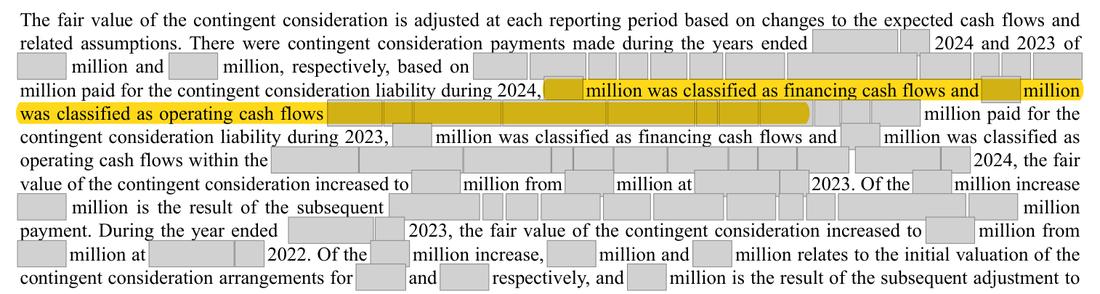
Four slips that change no audited figure: Note 3 refers to 'condensed' consolidated statements in the annual report; Note 6 gives the [acquisition 4] consideration as [amount] while its own table totals [n]; Note 8 still calls the 2023 [acquisition 2] allocation 'preliminary' after describing the measurement-period adjustments as completed; and Note 9 describes 'Other long-term assets, net' under a table captioned 'Other assets, net'.
The evidence, as filed
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
'condensed consolidated statements of operations' and 'condensed consolidated balance sheets' (Note 3); 'consideration transferred was [amount]' beside a net purchase price of [n] (Note 6); 'the allocation is preliminary' for [acquisition 2] (Note 8); 'Other long-term assets, net' (Note 9). | 'consolidated statements of operations / balance sheets'; '[amount]'; delete the 'preliminary' sentence for [acquisition 2]; 'Other assets, net'. |
Why it matters
Cosmetic; the slips may confuse a reader but change no audited amount.
Exposure
Drafting only.
Our workings
Each slip was read on the page image. The 'condensed' wording is carried from the quarterly reports; the annual statements are not condensed. The [acquisition 4] narrative appears to quote the cash paid rather than the total consideration in the table that follows it. The [acquisition 2] pro forma paragraph repeats acquisition-year wording although the note reports the measurement-period adjustments recognized through 2024. The Note 9 label differs from the table caption and the balance sheet line.
Management’s best defense, and our reply
These are wording slips carried over from quarterly or earlier text and no figure in the statements is affected. They are recorded only as drafting points for the next report.
The fix
- Make the four wording changes listed under 'should be' in the next annual report.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Slip 1: 'condensed' statements referred to in the annual report (Note 3) | Document | Form 10-K 2025, page 66 |
| 2 | Slip 2: narrative consideration for [acquisition 4] (Note 6) | Document | Form 10-K 2025, unnumbered page |
| 3 | Slip 2: the table in the same note totals [n] | Document | Form 10-K 2025, unnumbered page |
| 4 | Slip 3: [acquisition 2] allocation still called preliminary (Note 8) | Document | Form 10-K 2025, page 68 |
| 5 | Slip 3: the same note reports the measurement-period adjustments as done | Document | Form 10-K 2025, page 68 |
| 6 | Slip 4: label differs from the 'Other assets, net' caption (Note 9) | Document | Form 10-K 2025, page 70 |
| 7 | The fiscal 2024 annual Note 3 also referred to 'condensed' consolidated statements, here the statements of cash flows. | Document | Form 10-K 2024 (prior year), unnumbered page |
| 8 | The fiscal 2024 10-K already called the [acquisition 2] allocation preliminary, although [acquisition 2] was acquired on [date] and its one-year measurement period had ended. | Document | Form 10-K 2024 (prior year), unnumbered page |
| 9 | The same note describes the measurement-period adjustments as already recognized. | Document | Form 10-K 2024 (prior year), unnumbered page |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.