7.09 Two wording slips in Note 1: a self-contradicting anti-dilution sentence and a reference to available-for-sale securities the company does not hold
Company B · a US-listed transportation and logistics company · Drafting slip
In brief
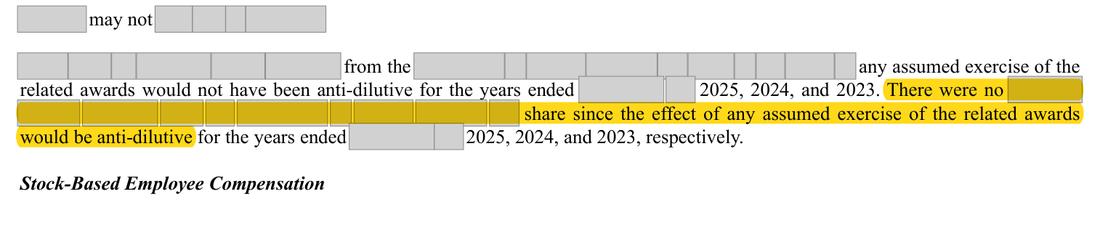
The income-per-share note says no unvested options were excluded from diluted earnings per share 'since' their effect would be anti-dilutive, which reverses the logic (anti-dilutive awards are the ones excluded); the companion sentence on unvested shares is correct in substance but speaks of an assumed 'exercise' of restricted shares. The fair-value policy lists available-for-sale securities among the company's financial instruments, but no such securities appear anywhere else in the 10-K.
The evidence, as filed
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
'There were no unvested options excluded from the calculation of diluted earnings per share since the effect of any assumed exercise of the related awards would be anti-dilutive'; 'Our financial instruments consist primarily of cash and cash equivalents, accounts receivable, available-for-sale securities ...'. | 'No unvested shares or options were excluded from the calculation of diluted earnings per share, because none had an anti-dilutive effect in 2025, 2024 or 2023'; and a list of financial instruments without available-for-sale securities. |
The rule
ASC 260-10-45 and 260-10-50-1 (EPS presentation and reconciliation, including anti-dilutive securities; paraphrase)
Summary; FASB/IFRS text is copyrighted Present basic and diluted EPS on the income statement, apply the two-class method to participating securities, and reconcile numerators and denominators including antidilutive securities.
Version: Text in force at the date of this review · Source: FASB Accounting Standards Codification, ASC 260-10-45 and 260-10-50-1 (as amended to 2025)
Why it applies here. Slip 1 (unnumbered page): the two anti-dilution sentences say, in turn, that no unvested shares were excluded because their effect 'would not have been anti-dilutive', and that no unvested options were excluded 'since' their effect 'would be anti-dilutive'. The second reverses the rule (anti-dilutive potential shares are excluded), and both read awkwardly; the diluted share count in the same table includes options and restricted shares in all three years, so the intended meaning is that nothing was anti-dilutive. Slip 2 (unnumbered page): the fair-value policy lists 'available-for-sale securities'; the balance sheet, the fair-value hierarchy table and the rest of the 10-K show none. No figure changes in either case.
Why it matters
Cosmetic: no figure changes, but an inverted sentence in the earnings-per-share note invites a reader or the staff to ask whether awards were excluded.
Exposure
None; drafting.
Management’s best defense, and our reply
Management would say the meaning is clear from the diluted share count, which includes all unvested shares and options. They would add that the instrument list is a standing description that does no harm.
The fix
- Replace the two sentences with: 'No unvested restricted shares or stock options were excluded from the calculation of diluted earnings per share for 2025, 2024 or 2023, as none had an anti-dilutive effect'; and delete 'available-for-sale securities' from the list of financial instruments.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Slip 1: the sentence reverses the anti-dilution rule. | Document | Form 10-K 2025, unnumbered page |
| 2 | Slip 1: the companion sentence on unvested shares. | Document | Form 10-K 2025, unnumbered page |
| 3 | Slip 2: available-for-sale securities are listed. | Document | Form 10-K 2025, unnumbered page |
| 4 | The fiscal 2024 fair-value policy already listed available-for-sale securities, which the company did not hold at either year end. | Document | Form 10-K 2024 (prior year), unnumbered page |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Interest rate swaps
- What is missing
- any available-for-sale securities among the instruments measured at fair value
- Pages looked at
- unnumbered page (balance sheet), unnumbered page (Note 1), p.113-66 (fair value note)
- Result
- 'available-for-sale' hits only unnumbered page, the slip itself; 'debt securities' hits p.41-22 (risk factors on raising funds by issuing securities); the other terms do not hit.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.