7.07 Six drafting slips in MD&A and Part III, four of them also in the prior year
Company B · a US-listed transportation and logistics company · Drafting slip
In brief
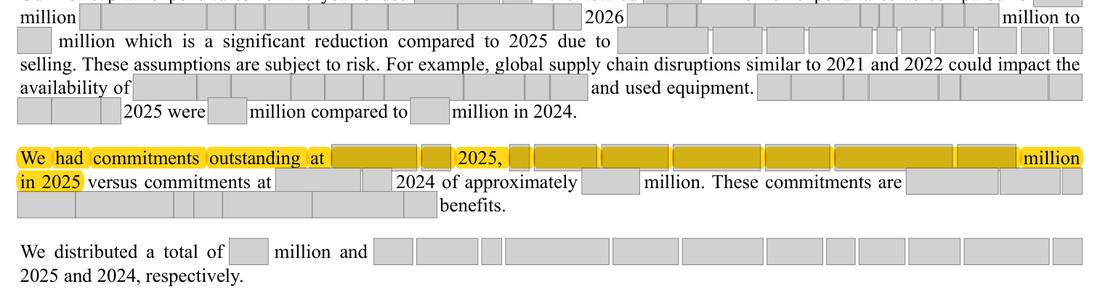
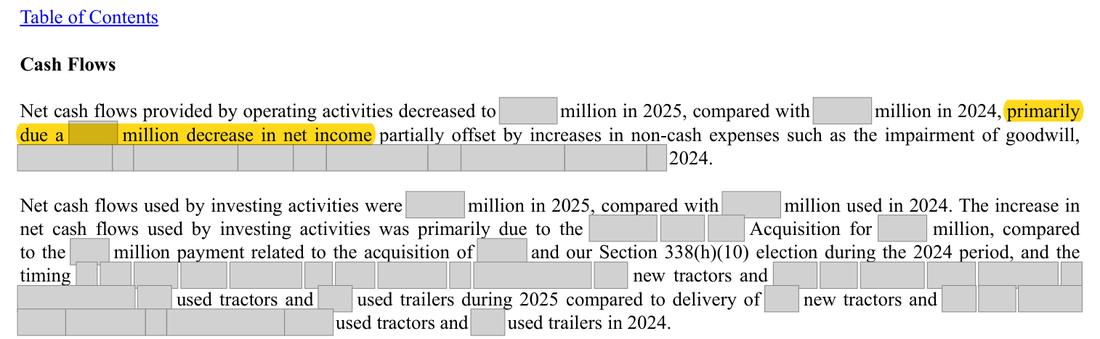
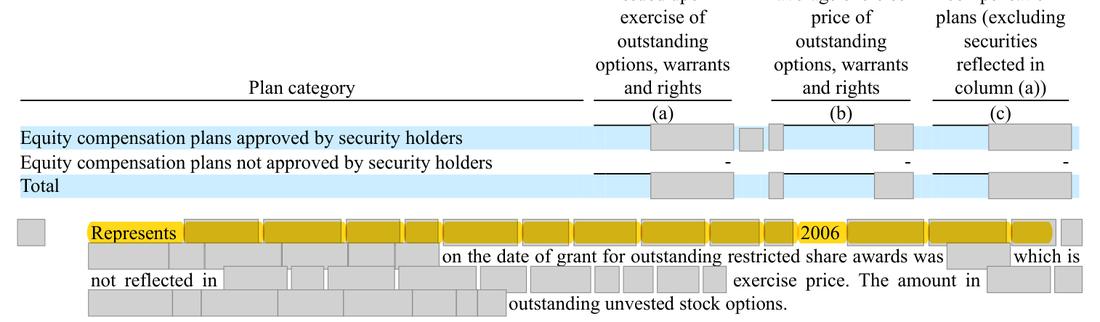
Six wording slips: equipment commitments at [date] are said to be for 2025; the MD&A footnote on the segment measure leaves out the [wording masked] that the segment note lists; a missing word in the cash flow discussion; the critical accounting estimates say acquisitions are accounted for under the 'purchase method', the superseded name for the acquisition method; the equity plan table calls options 'unvested' although the note shows all of them exercisable; and Item 14 refers to 'remaining' information when none is given in the 10-K. The commitments year slip, the 'purchase method', 'unvested' and Item 14 'remaining' were all in the prior-year 10-K as well.
The evidence, as filed
2 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
'commitments outstanding at [date] ... totaling approximately [amount] in 2025'; MD&A footnote lists amortization, goodwill impairment and contingent consideration only; 'primarily due a [amount] decrease'; 'Acquisitions are accounted for using the purchase method.' (both years); 'unvested stock options'; Item 14 'The remaining information required by this Item'. | '... [amount] in 2026' (or no year, as in the commitments note); the MD&A footnote to list [wording masked] as the note does; 'primarily due to a'; 'Acquisitions are accounted for using the acquisition method.'; 'outstanding stock options'; Item 14 'The information required by this Item'. |
Why it matters
Cosmetic; no reader decision changes.
Exposure
None.
Our workings
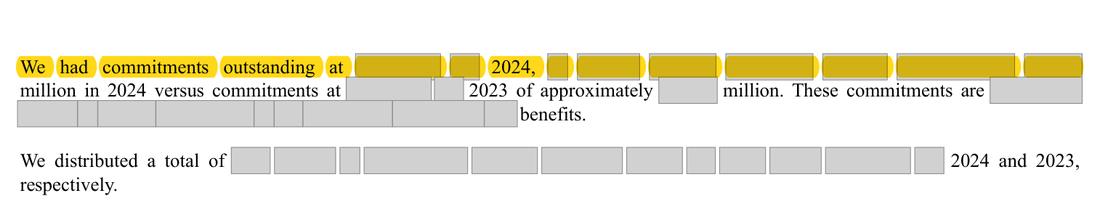
Each slip is shown by one extract. The commitments note states the same commitment without a year; the segment note footnote lists [wording masked] among the excluded items; the stock compensation note shows all outstanding options exercisable at the year end. The rest of the business-combination paragraph (acquisition-date fair values, contingent consideration) describes the acquisition method, so only the name is out of date. The prior-year 10-K carried four of the slips: commitments outstanding at [date] described as commitments to acquire equipment in 2024 (Form 10-K 2024 (prior year) p.37), the 'purchase method' (Form 10-K 2024 (prior year) unnumbered page), the [n] outstanding options called 'unvested' although all were exercisable, and Item 14 'remaining' information (Form 10-K 2024 (prior year) p.46). None changes an audited figure.
Management’s best defense, and our reply
Management could say these are template carry-overs that no reader would misread. That is fair, which is why they are listed as drafting slips only.
The fix
- Correct the six wordings as set out under 'should be'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Year label: commitments at the end of 2025 are for 2026 | Document | Form 10-K 2025, unnumbered page |
| 2 | MD&A footnote omits the held-for-sale write-down | Document | Form 10-K 2025, unnumbered page |
| 3 | Segment note footnote includes it | Document | Form 10-K 2025, page 77 |
| 4 | Missing word | Document | Form 10-K 2025, page 38 |
| 5 | Options described as unvested | Document | Form 10-K 2025, page 46 |
| 6 | Stock compensation note: all [n] options exercisable | Document | Form 10-K 2025, unnumbered page |
| 7 | Item 14 says 'remaining' although no Item 14 information precedes it | Document | Form 10-K 2025, page 46 |
| 8 | The fiscal 2025 critical accounting estimates still name the 'purchase method' | Document | Form 10-K 2025, unnumbered page |
| 9 | The prior-year 10-K gives the commitments at [date] | Document | Form 10-K 2024 (prior year), page 37 |
| 10 | and dates them to 2024, the year already ended - the same slip as in the fiscal 2025 10-K | Document | Form 10-K 2024 (prior year), page 37 |
| 11 | The prior-year 10-K used the same superseded name | Document | Form 10-K 2024 (prior year), unnumbered page |
| 12 | The prior-year equity plan table also called the outstanding options 'unvested' | Document | Form 10-K 2024 (prior year), page 46 |
| 13 | The prior-year option note shows all [n] outstanding options exercisable at the same [amount] price | Document | Form 10-K 2024 (prior year), unnumbered page |
| 14 | The prior-year Item 14 also referred to 'remaining' information when the 10-K gives none | Document | Form 10-K 2024 (prior year), page 46 |
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.