5.02 The revenue policy keeps the drivers' wages wording the SEC staff questioned in 2019, although the company undertook to replace it
Company B · a US-listed transportation and logistics company · Compliance or disclosure gap
In brief
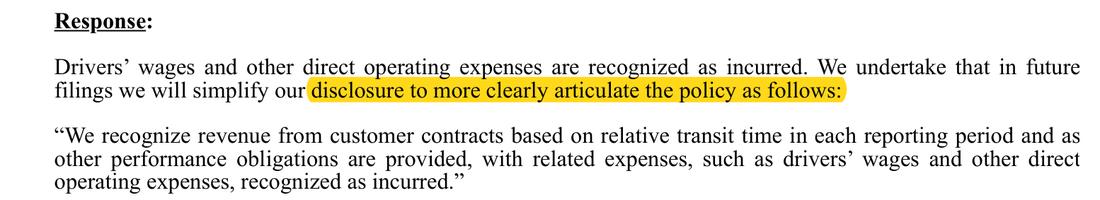
In [date] the SEC staff asked why the revenue policy said drivers' wages and other direct operating expenses are recognized proportionally rather than as incurred. The company replied that those expenses are recognized as incurred and undertook to replace the policy wording in future filings with a sentence on relative transit time. The revenue recognition policy in this 10-K, in the prior-year 10-K and in the [date] Form 10-Q still carries the original wording, and the promised sentence appears nowhere in the report. The staff's 2025 review of the same policy note closed without raising it again.
The evidence, as filed
5 further page extracts: screenshot withheld to protect the company’s identity. The rows below say what each shows.
What the filing shows, and what the rule requires
| What the filing shows | What the rule requires |
|---|---|
Note 1 Revenue Recognition: 'Revenue, drivers' wages, and other direct operating expenses generated by our Segment 1 and Segment 2 [wording masked] performed'. The undertaken sentence (revenue 'based on relative transit time', expenses recognized as incurred) is absent; same wording in the prior-year 10-K. | The policy as undertaken to the staff: revenue recognized based on relative transit time in each reporting period and as other performance obligations are provided, with related expenses such as drivers' wages and other direct operating expenses recognized as incurred. |
The rule
Exchange Act Rule 12b-20
there shall be added such further material information, if any, as may be necessary to make the required statements, in the light of the circumstances under which they are made not misleading
Version: Text in force at the date of this review · Source: 17 CFR 240.12b-20 (eCFR, current)
Why it applies here. The undertaken sentence appears nowhere in the report. No amount is said to be misstated; the point is the policy description and an open undertaking. The staff's 2025 review closed without raising it.
Why it matters
- The audited policy note keeps wording the company told the staff it would replace.
- A later review that tracks prior undertakings could raise it again; no fine or restatement is expected.
How often the SEC staff raises this. In 1,100 SEC staff comment letters on fiscal 2023 and 2024 Forms 10-K, released January 2025 to October 2026, revenue recognition and disclosure drew 68 of the 1,774 numbered comments (3.8%): topic 7 of 25 by frequency.
Exposure
A renewed SEC staff comment on a later review, with a request to revise in future filings; no fine or restatement expected for a policy-wording point.
Our workings
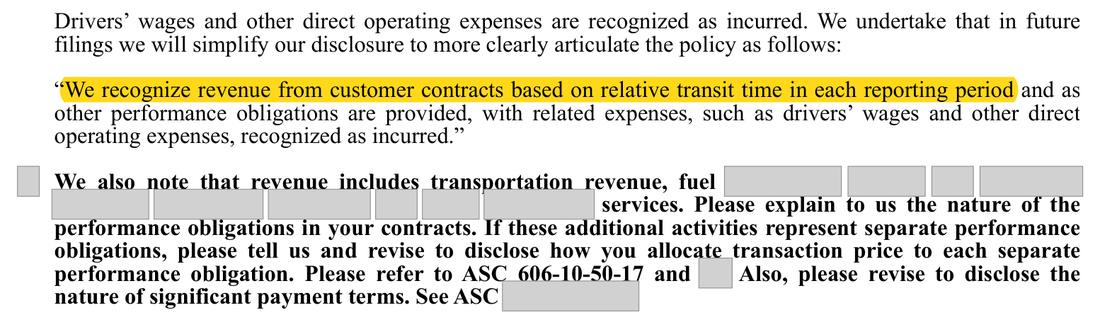
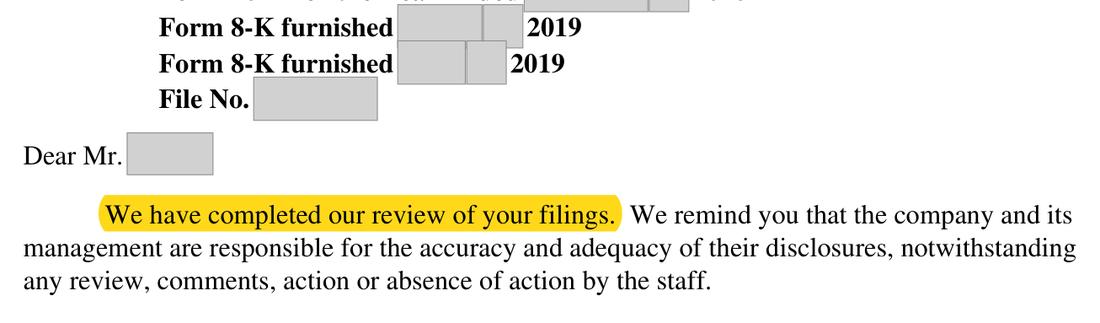
the staff letter of [date] (comment 4, on the fiscal 2018 10-K) questioned the proportional recognition of drivers' wages and direct expenses. The company's response of [date] stated that those expenses are recognized as incurred and undertook that in future filings it would simplify the disclosure to a stated sentence; the staff closed that review on [date]. The fiscal 2019 10-K (filed [date]) kept the proportional wording, and so do the fiscal 2024 and fiscal 2025 [n]-Ks; only the segment names changed ([former segment name] became Segment 1). In [date] the staff reviewed the fiscal 2024 10-K, commented on the Segment 3 paragraph of the same Revenue Recognition note, and closed its review on [date] without returning to the drivers' wages wording.
a written undertaking to the staff, not limited to any one filing and not withdrawn in the later correspondence, remains undelivered, and the policy note keeps a description of expense recognition that the company itself told the staff needed to be restated more clearly. For wages earned by the mile the two descriptions may give the same figures, so no amount is said to be misstated: the point is the accuracy of the policy description and the open undertaking, not a measurement error.
Management’s best defense, and our reply
Management could say that the economic effect is nil: drivers are paid largely by the mile, so wages recognized in proportion to miles completed are in substance recognized as incurred, and trips in transit at a period end are a day or two of activity. It could add that the staff reviewed this very Revenue Recognition note in 2025, commented only on the Segment 3 paragraph and closed its review, which suggests the staff no longer regards the 2019 point as open. However, the 2019 undertaking was given in writing, without limit to any one filing, to close the staff's comment; the staff's closing letters state that the company remains responsible for its disclosures notwithstanding any absence of action by the staff, and nothing in the 2025 correspondence released the undertaking. The wording costs one sentence to correct, so the undertaking should be honored.
The fix
- Replace the first sentence of the Revenue Recognition policy with the undertaken wording in the next Form 10-Q and Form 10-K: 'We recognize revenue from customer contracts based on relative transit time in each reporting period and as other performance obligations are provided, with related expenses, such as drivers' wages and other direct operating expenses, recognized as incurred.'
Note 1, Revenue Recognition, page 60: first sentence
Also: the wording the company undertook to the SEC staff on [date]
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The staff's comment 4 on the revenue recognition policy | Document | |
| 2 | The company's answer and its undertaking to the staff | Document | |
| 3 | The policy sentence the company undertook to use | Document | |
| 4 | This 10-K still carries the wording the staff questioned | Document | Form 10-K 2025, page 60 |
| 5 | The staff closed the 2019 review after the company's undertaking | Document | |
| 6 | The staff's 2025 review addressed the same Revenue Recognition note (Segment 3 paragraph only) | Document | |
| 7 | The 2025 review closed without returning to the drivers' wages wording | Document | |
| 8 | The [date] Form 10-Q still carries the wording | Document | |
| 9 | The prior-year revenue policy carries the same wording the company undertook in 2019 to replace | Document | Form 10-K 2024 (prior year), page 60 |
Absence check
- Document
- Form 10-K 2025
- Where it would appear
- Revenue Recognition
- What is missing
- The undertaken sentence: revenue based on relative transit time, with drivers' wages and other direct operating expenses recognized as incurred
- Pages looked at
- p.59-103
- Result
- 'drivers' wages' hits only p.60, in the old proportional wording itself; 'as incurred' hits unnumbered page (variable lease payments expensed as incurred), not the revenue policy; 'relative transit' and 'transit time' have no hits.
Prepared by Pramanex from the company’s public SEC filings, without the company’s involvement, to show how a 10-K Pre-filing Check reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other attestation or assurance engagement, and not legal advice. An SEC-style question is a question, not a conclusion.
Want this on your own 10-K, before you file?
Start with three free findings on your latest 10-K, or book a fixed-price 10-K Pre-filing Check.
Your next 10-K will be in draft before the audit is done.
Have it read before you file.
Start with three free findings on your latest 10-K, or book a fixed-price 10-K check. Drafts only under NDA, inside your insider trading policy.